That House That’s Been Sitting Could Be Your Best Shot at a Deal

BLOGJune 22, 2026


Open up a home search and you'll see them. Listings that have been on the market for two months. Three. Some longer.

Most buyers scroll right past them, assuming something’s wrong with the house. But that instinct could be costing you, since the longer a home sits, the more motivated the seller usually gets.

Where Some Buyers Are Finding Better Deals

If affordability has been your #1 hurdle to buying, here’s a surprisingly simple strategy that could help you finally get your foot in the door. Start with the homes that have been sitting the longest. That’s often where the best deals are.

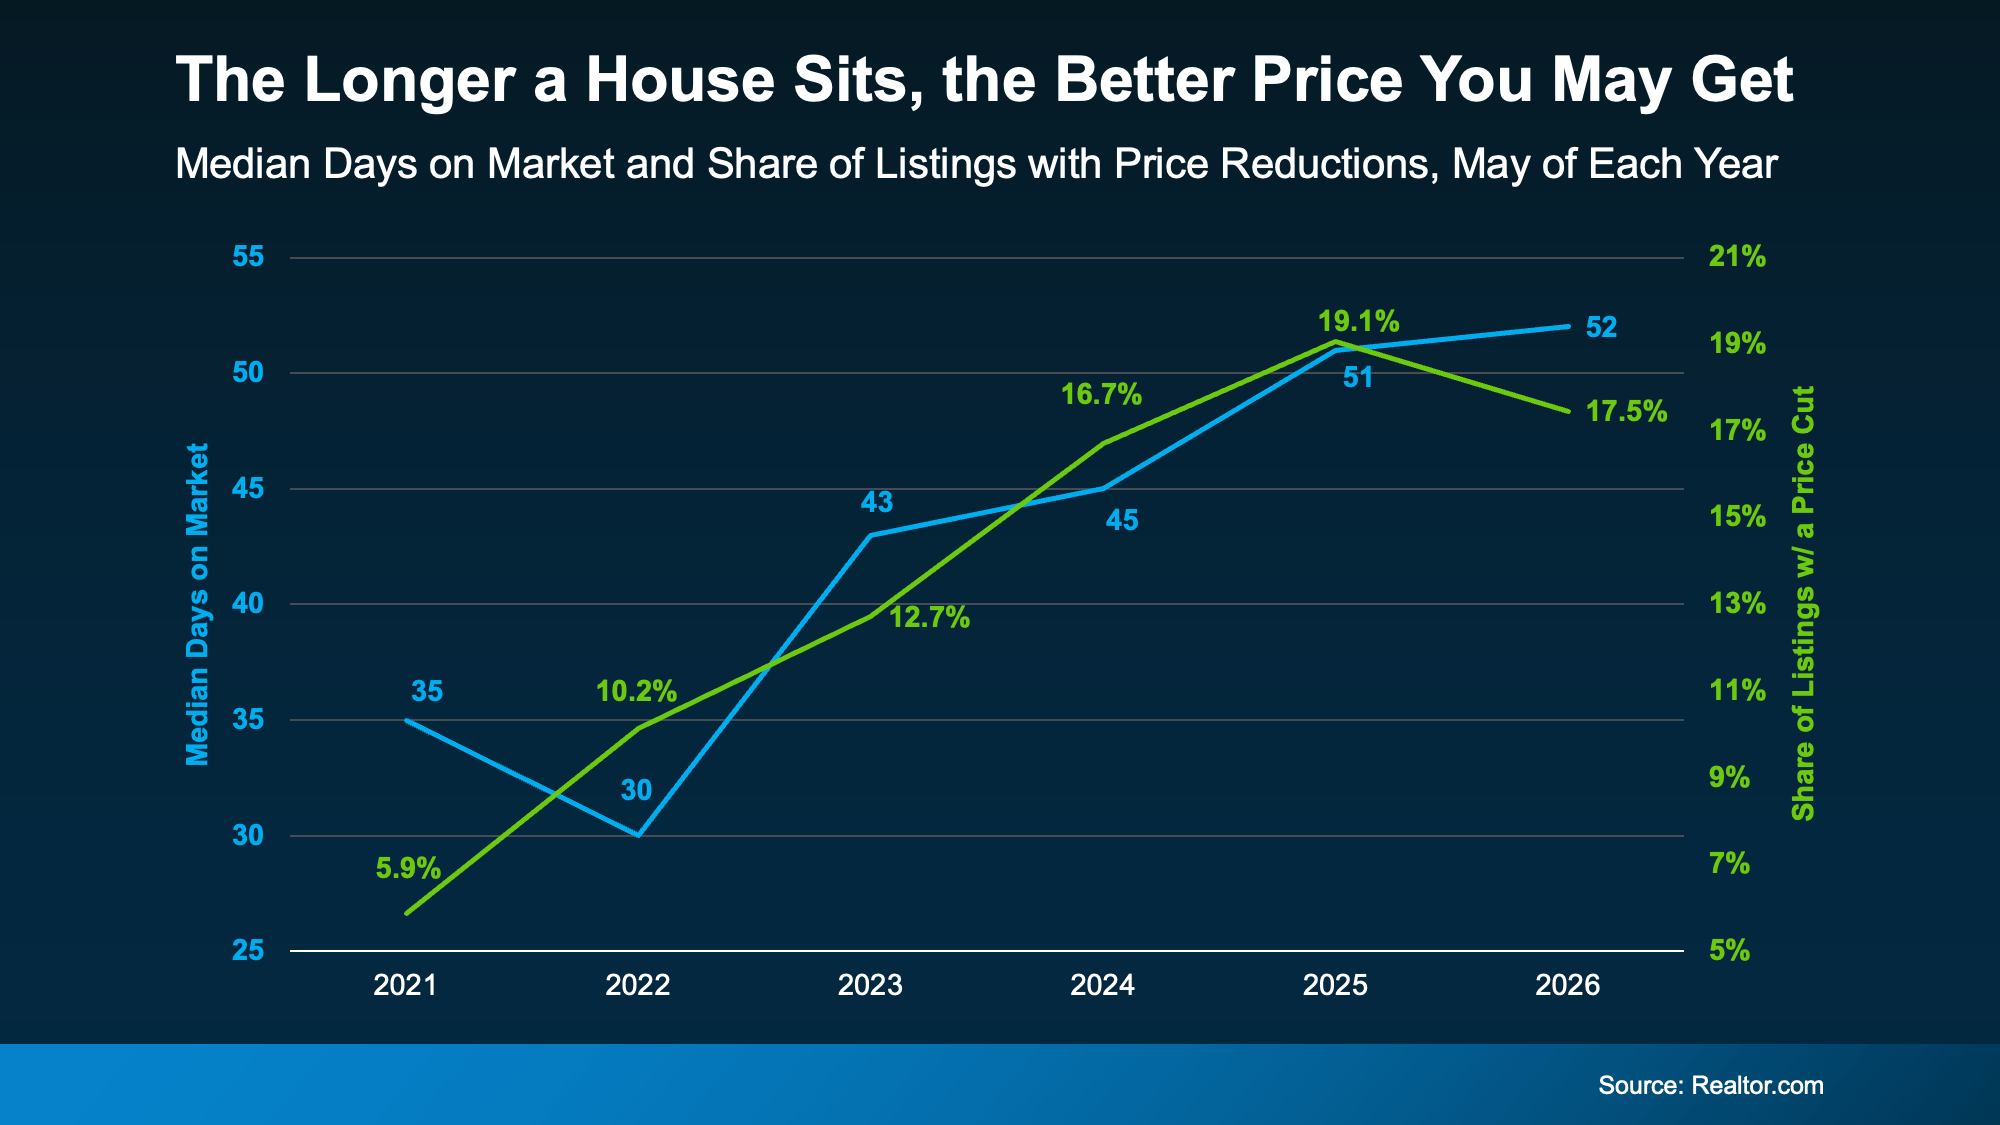
Here’s why. Data from Realtor.com shows there’s a connection between longer time on the market and lower sales prices. Basically, the longer a house sits, the more likely it is that the seller will reduce the price (see graph below):

a graph with numbers and lines

The blue line tracks how long homes stay on the market, while the green line tracks the share of homes getting a price reduction. As one climbs, so does the other.  

And if you focus on these homes that are just sitting and waiting, the opportunity for you is bigger than you may think right now.

Redfin data shows there’s $347 billion worth of stale listings on the market right now – more than ever before for this time of year. So, ask your agent to filter listings for you from oldest to newest. The home that fits your budget might already be there. Just further down the list than you thought.

Lingering Doesn’t Always Mean Something’s Wrong 

Let’s say you do that and something catches your eye. Still, you might be questioning why the home has been sitting in the first place. Just remember, sometimes it has nothing to do with the home itself.

According to Redfin, common causes are:

  • The asking price was set too high to start

  • The home didn’t show well online

  • There are a lot of homes for sale in the area, so it just got buried

So, nothing that’s necessarily a dealbreaker, or even anything that’s wrong with the home itself. If there’s a real issue, a thorough inspection will surface it. And that’s information you can use to negotiate. Not a reason to assume it’s a house worth skipping over.

How To Turn a Lingering Listing into a Win

So how do you capitalize on a lingering listing? According to USA Today, you have two main levers to pull.

The first is price. Work with your agent to study what comparable homes recently sold for, then build an offer around that. Coming in below asking price is fair game when a home has been sitting.

The second is concessions. If a seller won’t budge much on price, they may still help in other ways, like covering some closing costs, repair credits, or even a mortgage rate buydown that lowers your monthly payment.

A local agent has the context to tell which homes are the real opportunities and which are skippable.

Bottom Line

A house sitting on the market isn’t always a glaring red flag. In today’s market, it may be your best opportunity yet.

For help deciding which lingering listings are actually worth a second look, let’s connect.

The information contained, and the opinions expressed, in this article are not intended to be construed as investment advice. Keeping Current Matters, Inc. does not guarantee or warrant the accuracy or completeness of the information or opinions contained herein. Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision. Keeping Current Matters, Inc. will not be liable for any loss or damage caused by your reliance on the information or opinions contained herein.

June 2, 2025

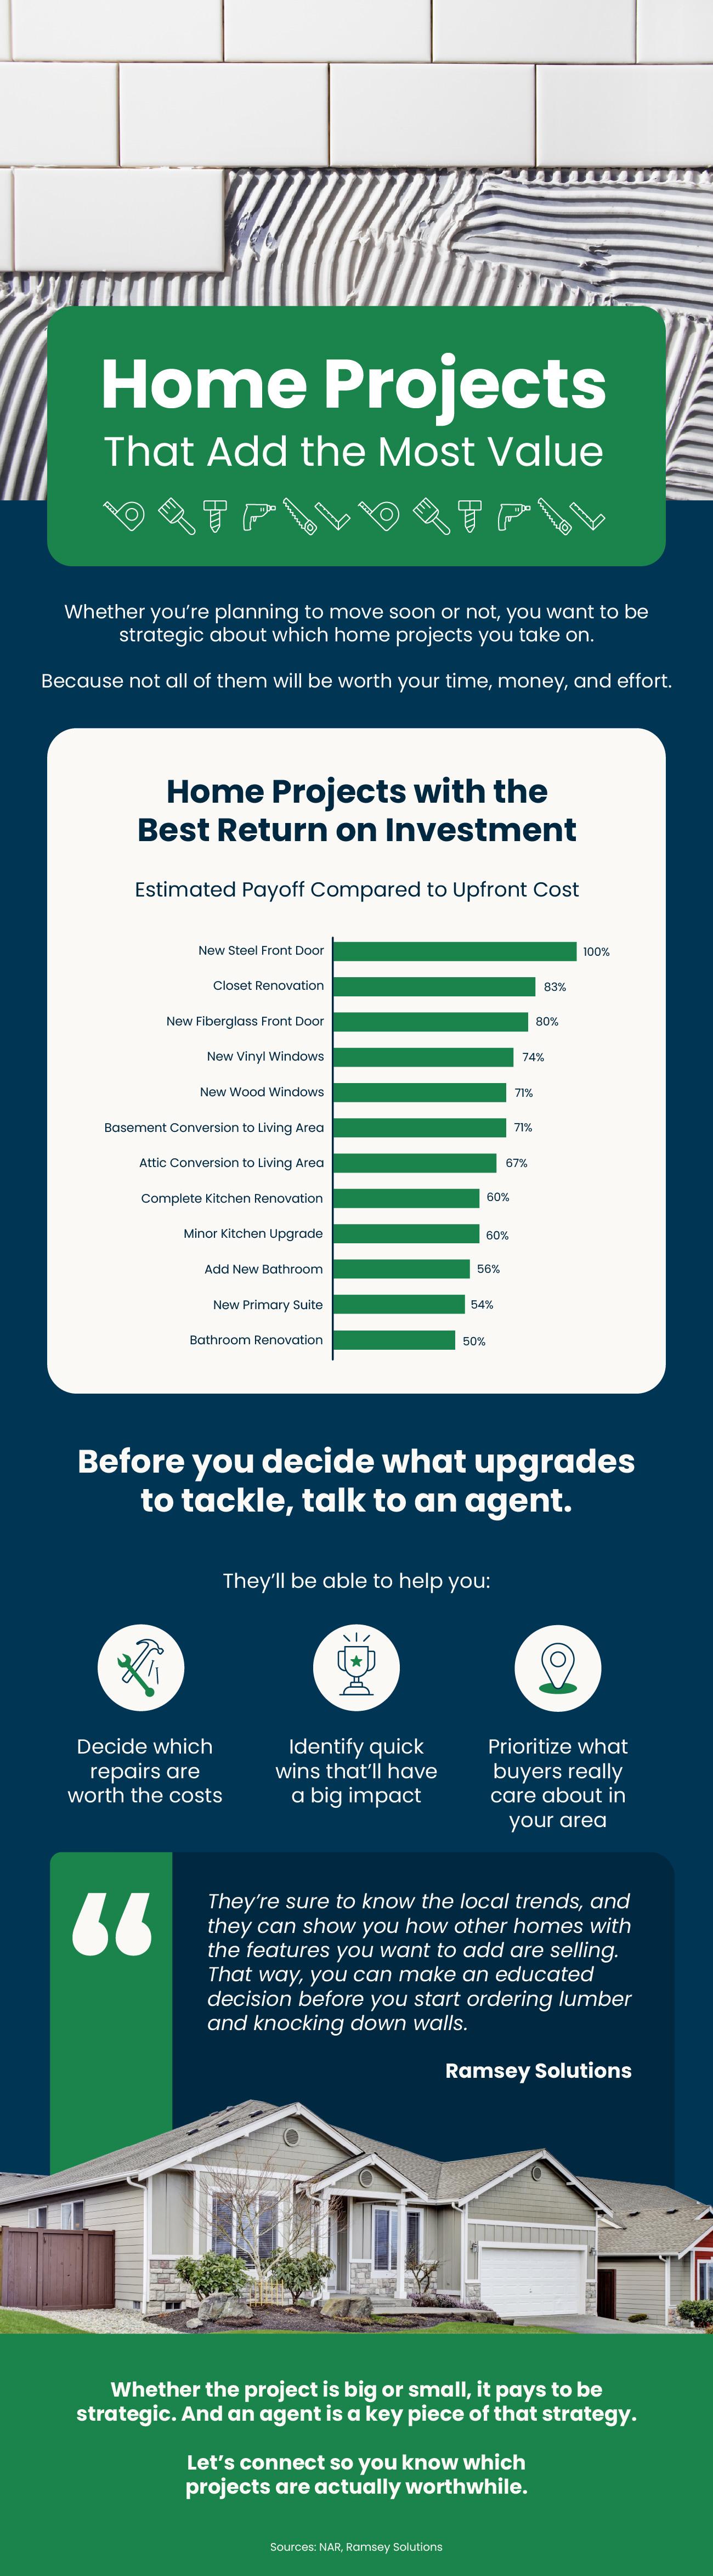
Home Projects That Add the Most Value

Home Projects That Add the Most Value

INFOGRAPHICMay 30, 2025


a screenshot of a phone

Some Highlights

  • Whether you’re planning to move soon or not, you want to be strategic about which home projects you take on. ​Because not all of them will be worth it.
  • Before you decide what upgrades to tackle, talk to an agent who knows what’s in demand in your area and where you’re most likely to recoup the costs.
  • Let’s connect so you know which projects are actually worthwhile.​

The information contained, and the opinions expressed, in this article are not intended to be construed as investment advice. Keeping Current Matters, Inc. does not guarantee or warrant the accuracy or completeness of the information or opinions contained herein. Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision. Keeping Current Matters, Inc. will not be liable for any loss or damage caused by your reliance on the information or opinions contained herein.

Posted in Market Updates
June 2, 2025

Is It Better To Rent or Buy a Home?

Is It Better To Rent or Buy a Home?

BLOGMay 29, 2025

You’ve probably asked yourself lately: Is it even worth trying to buy a home right now?

With high home prices and stubborn mortgage rates, renting can seem like the safer choice right now. Or maybe your only choice. That’s a very real feeling. And perhaps buying today isn’t your best move; it’s not for everyone right away. You should only buy a home when you’re ready and able to do it, and if the timing is right for you.

But here’s the thing you need to know about renting.

While it may feel like a safer bet today – and in some areas might even be less expensive month-to-month than owning – it can really cost you more over time.

In fact, a recent Bank of America survey found that 70% of aspiring homeowners worry about what long-term renting means for their future. And they’re not wrong.

Owning a home may seem way out of reach, but if you make a plan now and steadily work toward it, homeownership comes with serious long-term financial benefits.

Homeownership Builds Wealth Over Time

Buying a home isn’t just about having a place to live – it’s a step toward building your future wealth.

Why? Home prices typically rise over time, which means the longer you wait, the more expensive it is to buy. And even in some markets where home prices are softening today, the overall long-term trend speaks for itself (see graph below):
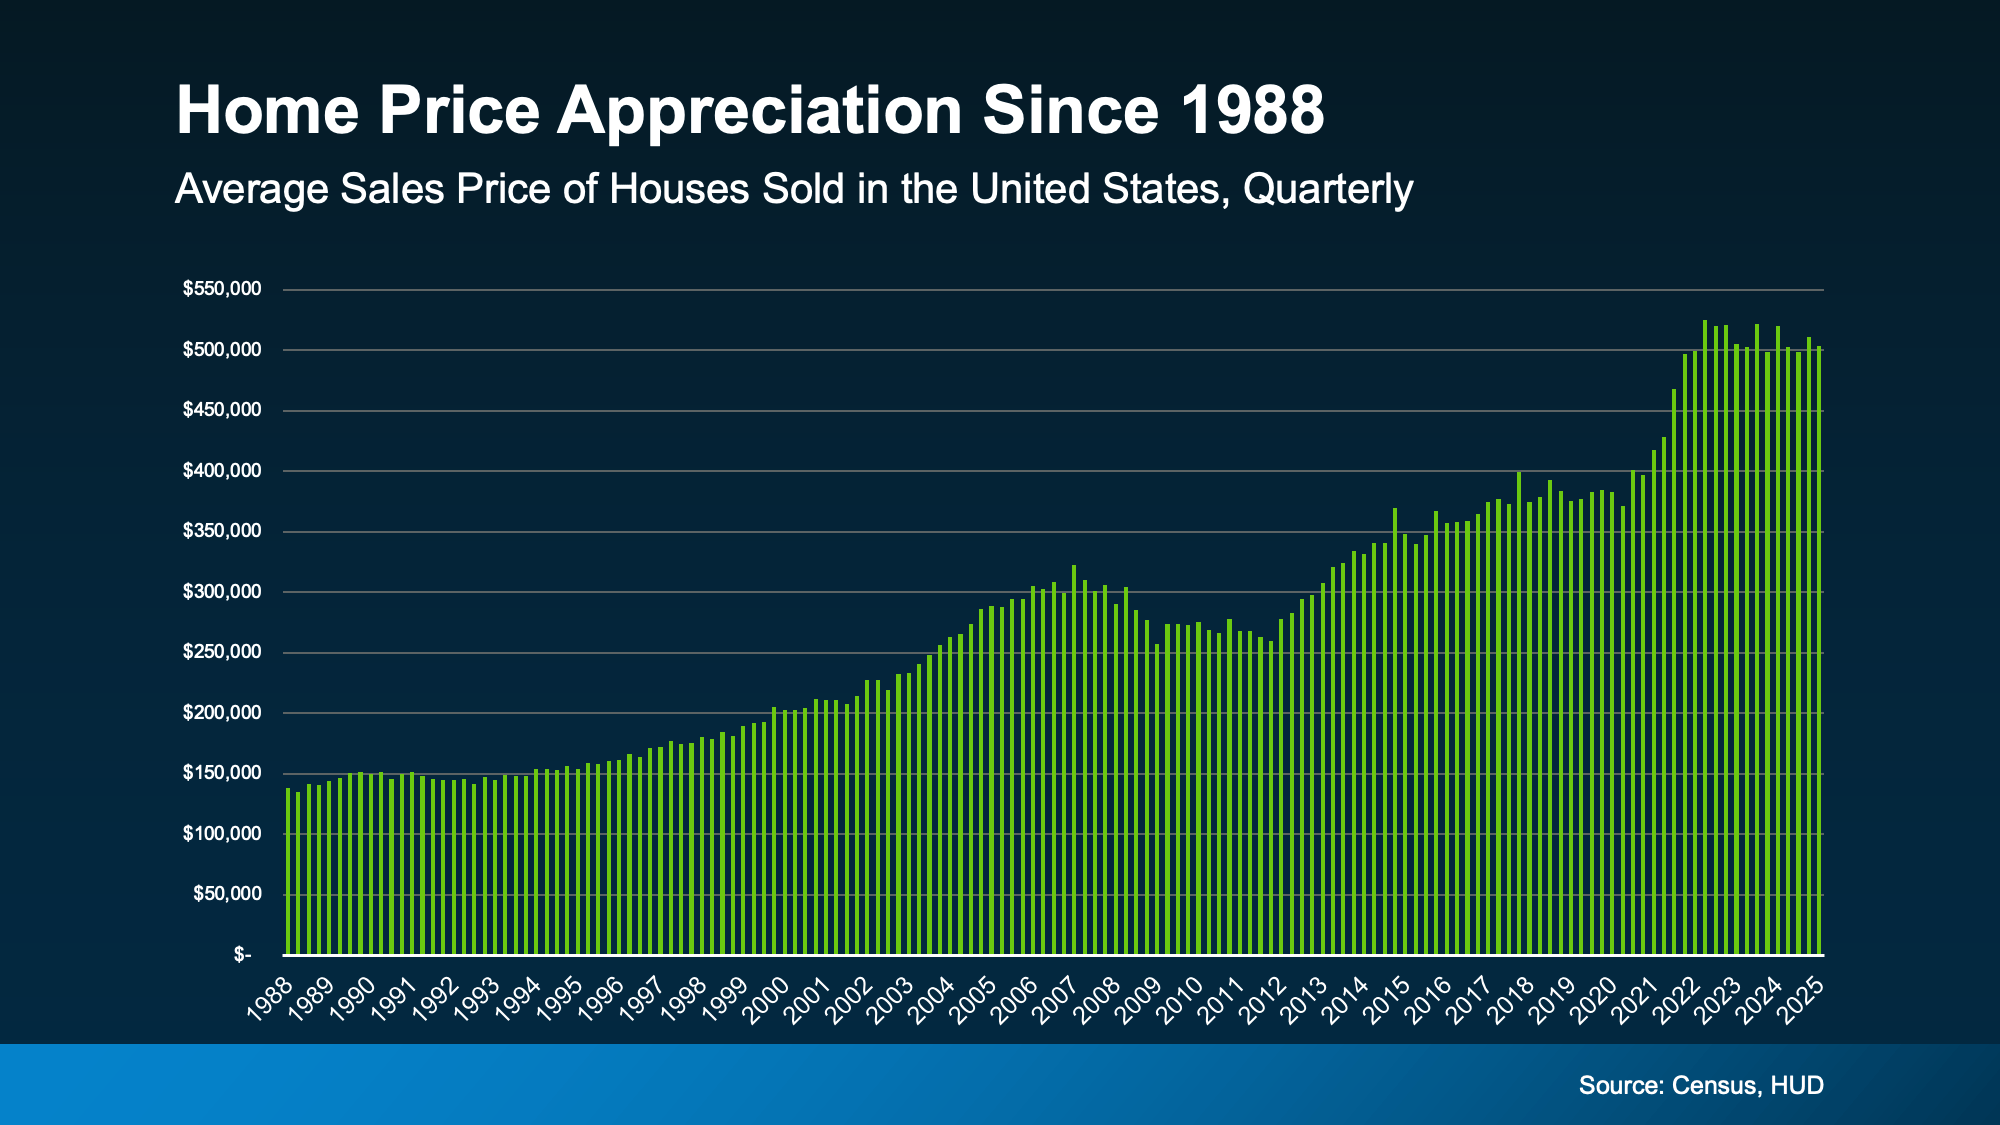
a graph of a price of houses sold in the united statesAnd as home values rise, so does your equity when you’re a homeowner. That’s the difference between what your home is worth and what you owe. So, with every mortgage payment, that equity grows. Over time, that becomes part of your net worth.

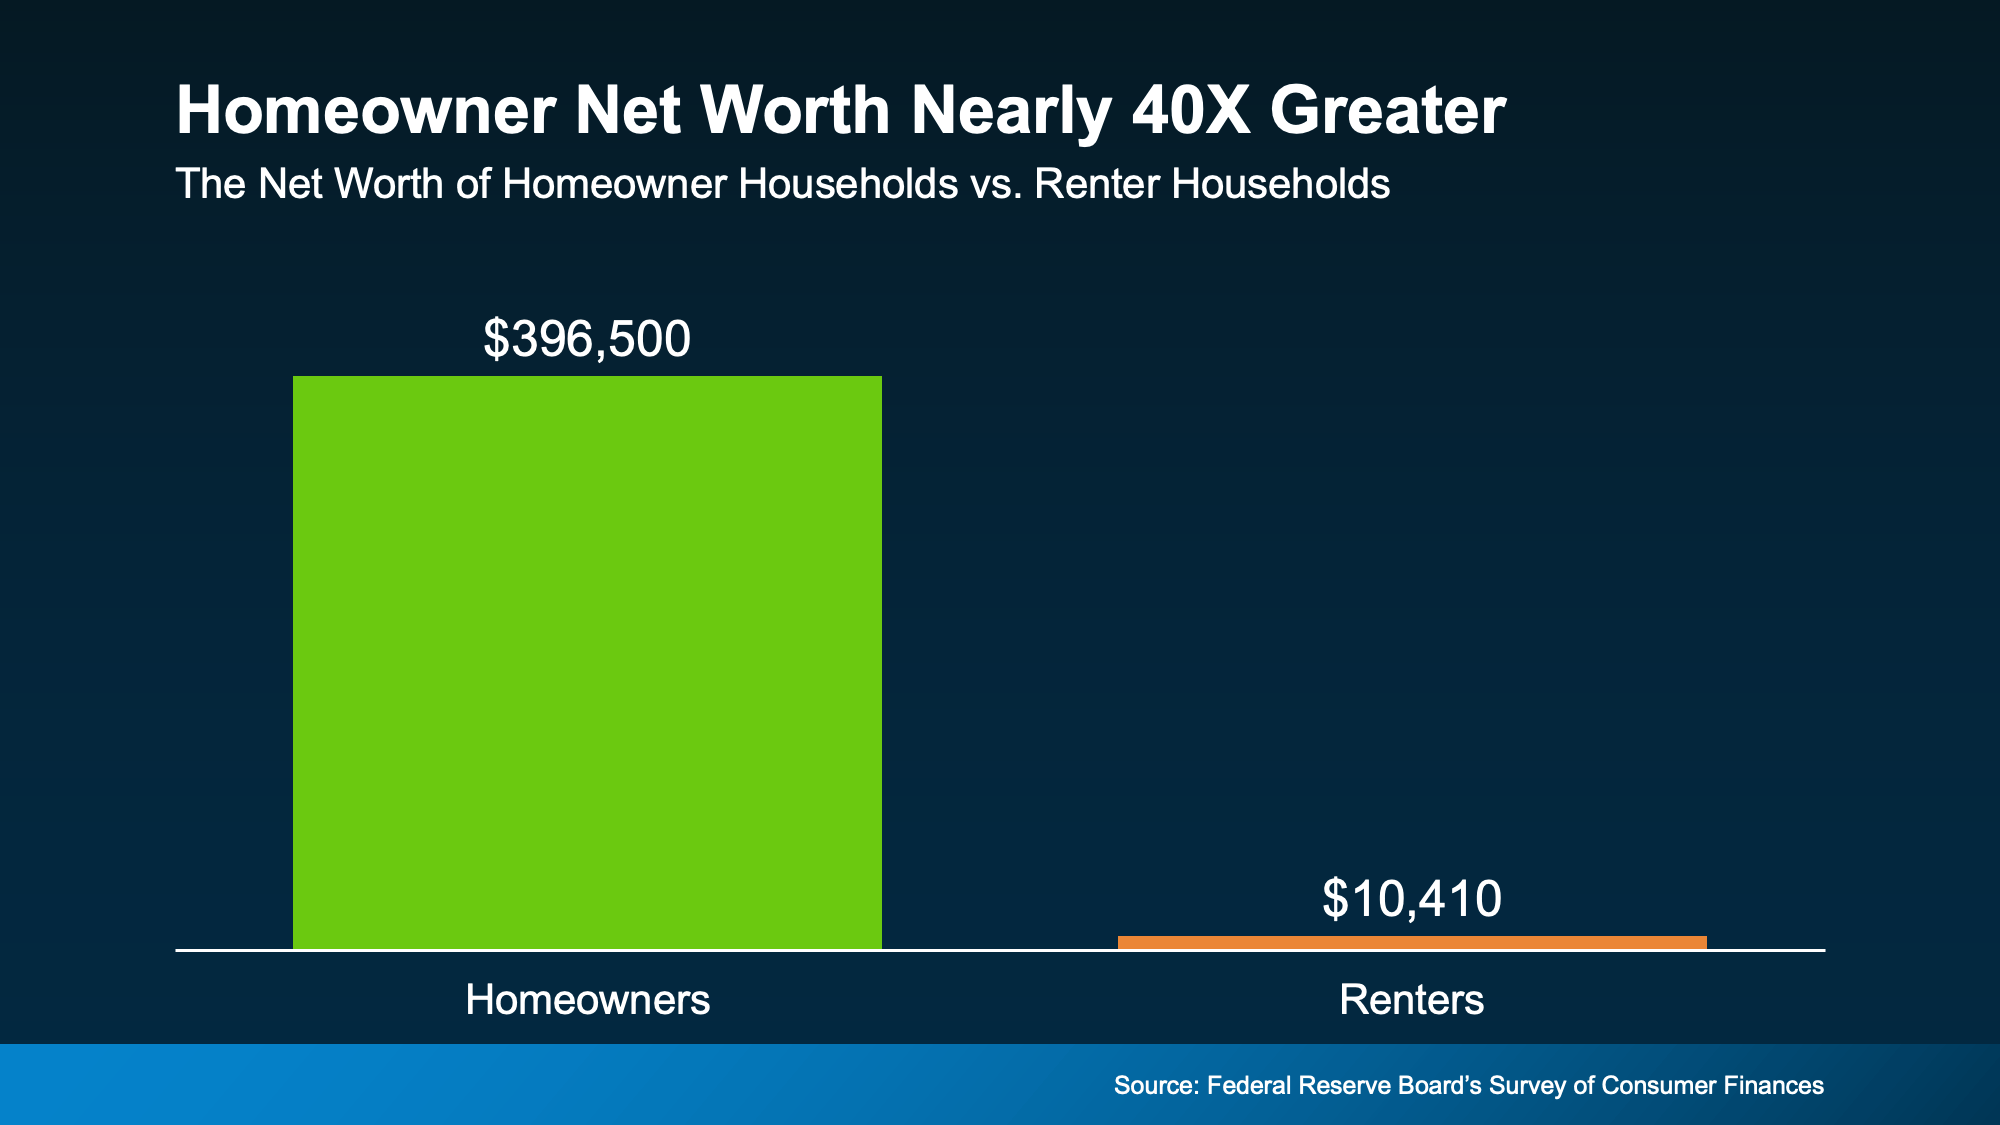
Today, the average homeowner’s net worth is nearly 40X greater than that of a renter. That’s a shocking difference, and the dollars in the visual below don’t lie (see graph below):
a green rectangle with white textAnd it’s one of the big reasons why Forbes says:

“While renting might seem like [the] less stressful option . . . owning a home is still a cornerstone of the American dream and a proven strategy for building long-term wealth.”

The Biggest Downside of Renting

So, short-term, why does renting feel like a simpler choice? Lower monthly payments, less responsibility, no strings attached. But long-term? It can sting.

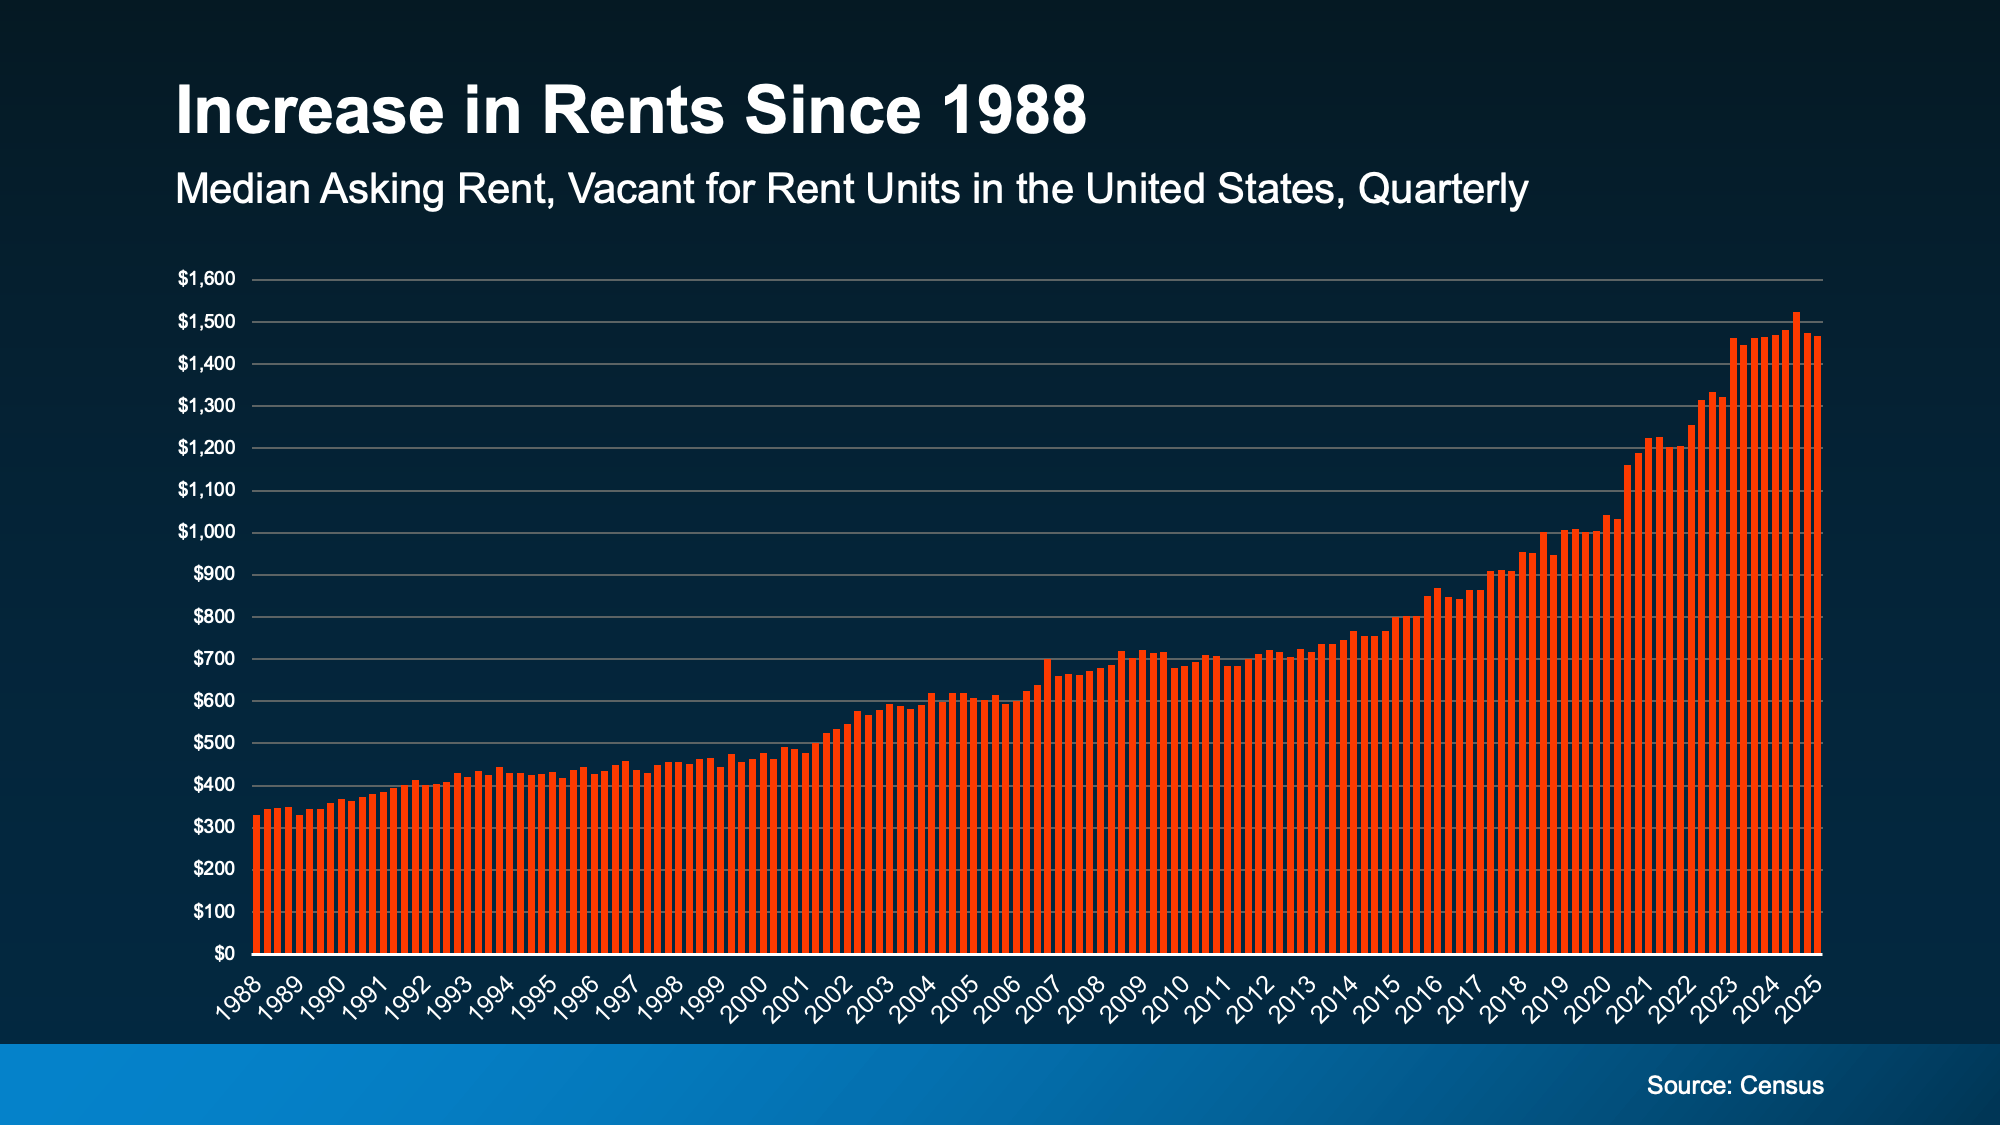
For decades, while home prices have been rising, rent has gone up too. And while rent has held rather steady more recently, history shows the overall trend is up and to the right. That makes saving for a home more complicated than ever (see graph below):
a graph of a number of peopleThat kind of financial uncertainty has a real impact. In the same Bank of America survey, 72% of potential buyers said they worry rising rent could affect their current and long-term finances.

Because rent doesn’t build wealth. It doesn’t come back to you later. It pays your landlord’s mortgage – not yours.

So, whether you rent or own, you’re paying a mortgage. The question is: whose mortgage do you want to pay?

Renting vs. Buying: What Really Matters

Think of it this way. Renting means your money is gone once you pay it. Owning means your payment builds equity – like a savings account you can live in. Sure, buying comes with responsibility. But it also comes with the kind of reward that grows over time. And that’s why you need a solid plan to get there.

As Joel Berner, Senior Economist at Realtor.com, explains:

“Households working on their budget will find it much easier to continue to rent than to go through the expenses of homeownership. However, they need to consider the equity and generational wealth they can build up by owning a home that they can’t by renting it. In the long run, buying a home may be a better investment even if the short-run costs seem prohibitive.”

Bottom Line

Renting may feel more do-able today. But over time, it could cost you more – without helping you build anything for your future.

If homeownership feels out of reach today, you’re not alone. And the first step toward getting out of the rental trap is to set a plan. Let’s connect, set your specific goals, and explore your options – so you’re ready when the time is right.

The information contained, and the opinions expressed, in this article are not intended to be construed as investment advice. Keeping Current Matters, Inc. does not guarantee or warrant the accuracy or completeness of the information or opinions contained herein. Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision. Keeping Current Matters, Inc. will not be liable for any loss or damage caused by your reliance on the information or opinions contained herein.

Posted in Market Updates
May 23, 2025

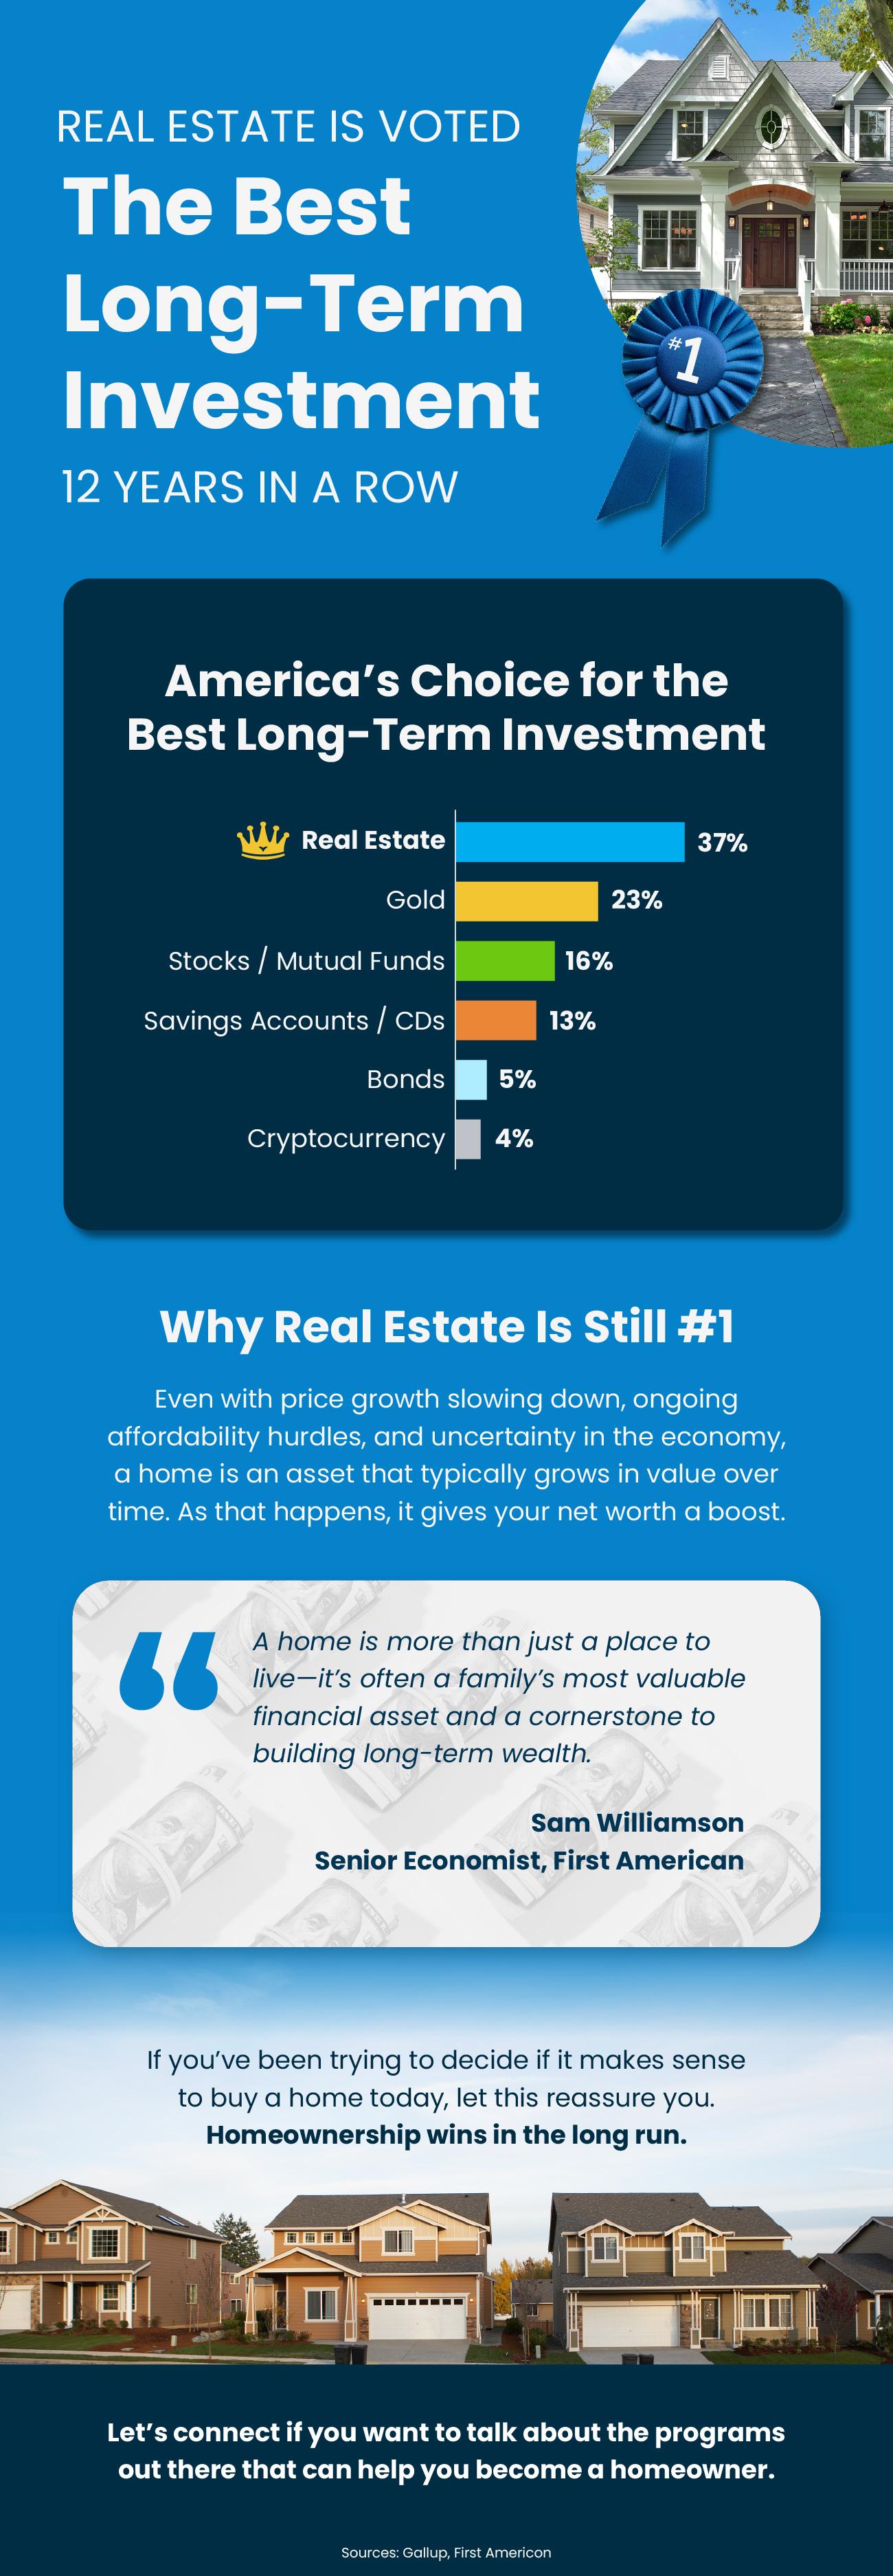
Real Estate Is Voted the Best Long-Term Investment 12 Years in a Row

Real Estate Is Voted the Best Long-Term Investment 12 Years in a Row

INFOGRAPHICMay 23, 2025

a screenshot of a cell phone

Some Highlights

  • In a recent poll from Gallup, real estate has once again been voted the best long-term investment. And it’s claimed that top spot for 12 straight years now.
  • That’s because homeownership is one of the top ways to build your wealth, even with home price growth moderating and ongoing economic uncertainty.
  • If you’ve been trying to decide if it makes sense to buy a home today, let’s connect and talk about the programs that can help you become a homeowner.

The information contained, and the opinions expressed, in this article are not intended to be construed as investment advice. Keeping Current Matters, Inc. does not guarantee or warrant the accuracy or completeness of the information or opinions contained herein. Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision. Keeping Current Matters, Inc. will not be liable for any loss or damage caused by your reliance on the information or opinions contained herein.

Posted in Market Updates
May 22, 2025

Thinking about an Adjustable-Rate Mortgage? Read This First.

Thinking about an Adjustable-Rate Mortgage? Read This First.

BLOGMay 22, 2025

3 min read

If you’ve been house hunting lately, you’ve probably felt the sting of today’s mortgage rates. And it’s because of those rates and rising home prices that many homebuyers are starting to explore other types of loans to make the numbers work. And one option that’s gaining popularity? Adjustable-rate mortgages (ARMs).

If you remember the crash in 2008, this may bring up some concerns. But don’t worry. Today’s ARMs aren’t the same. Here’s why.

Back then, some buyers were given loans they couldn’t afford after the rates adjusted. But now, lenders are more cautious, and they evaluate whether you could still afford the loan if your rate increases. So, don’t assume the return of ARMs means another crash. Right now, it just shows some buyers are looking for creative solutions when affordability is tough. 

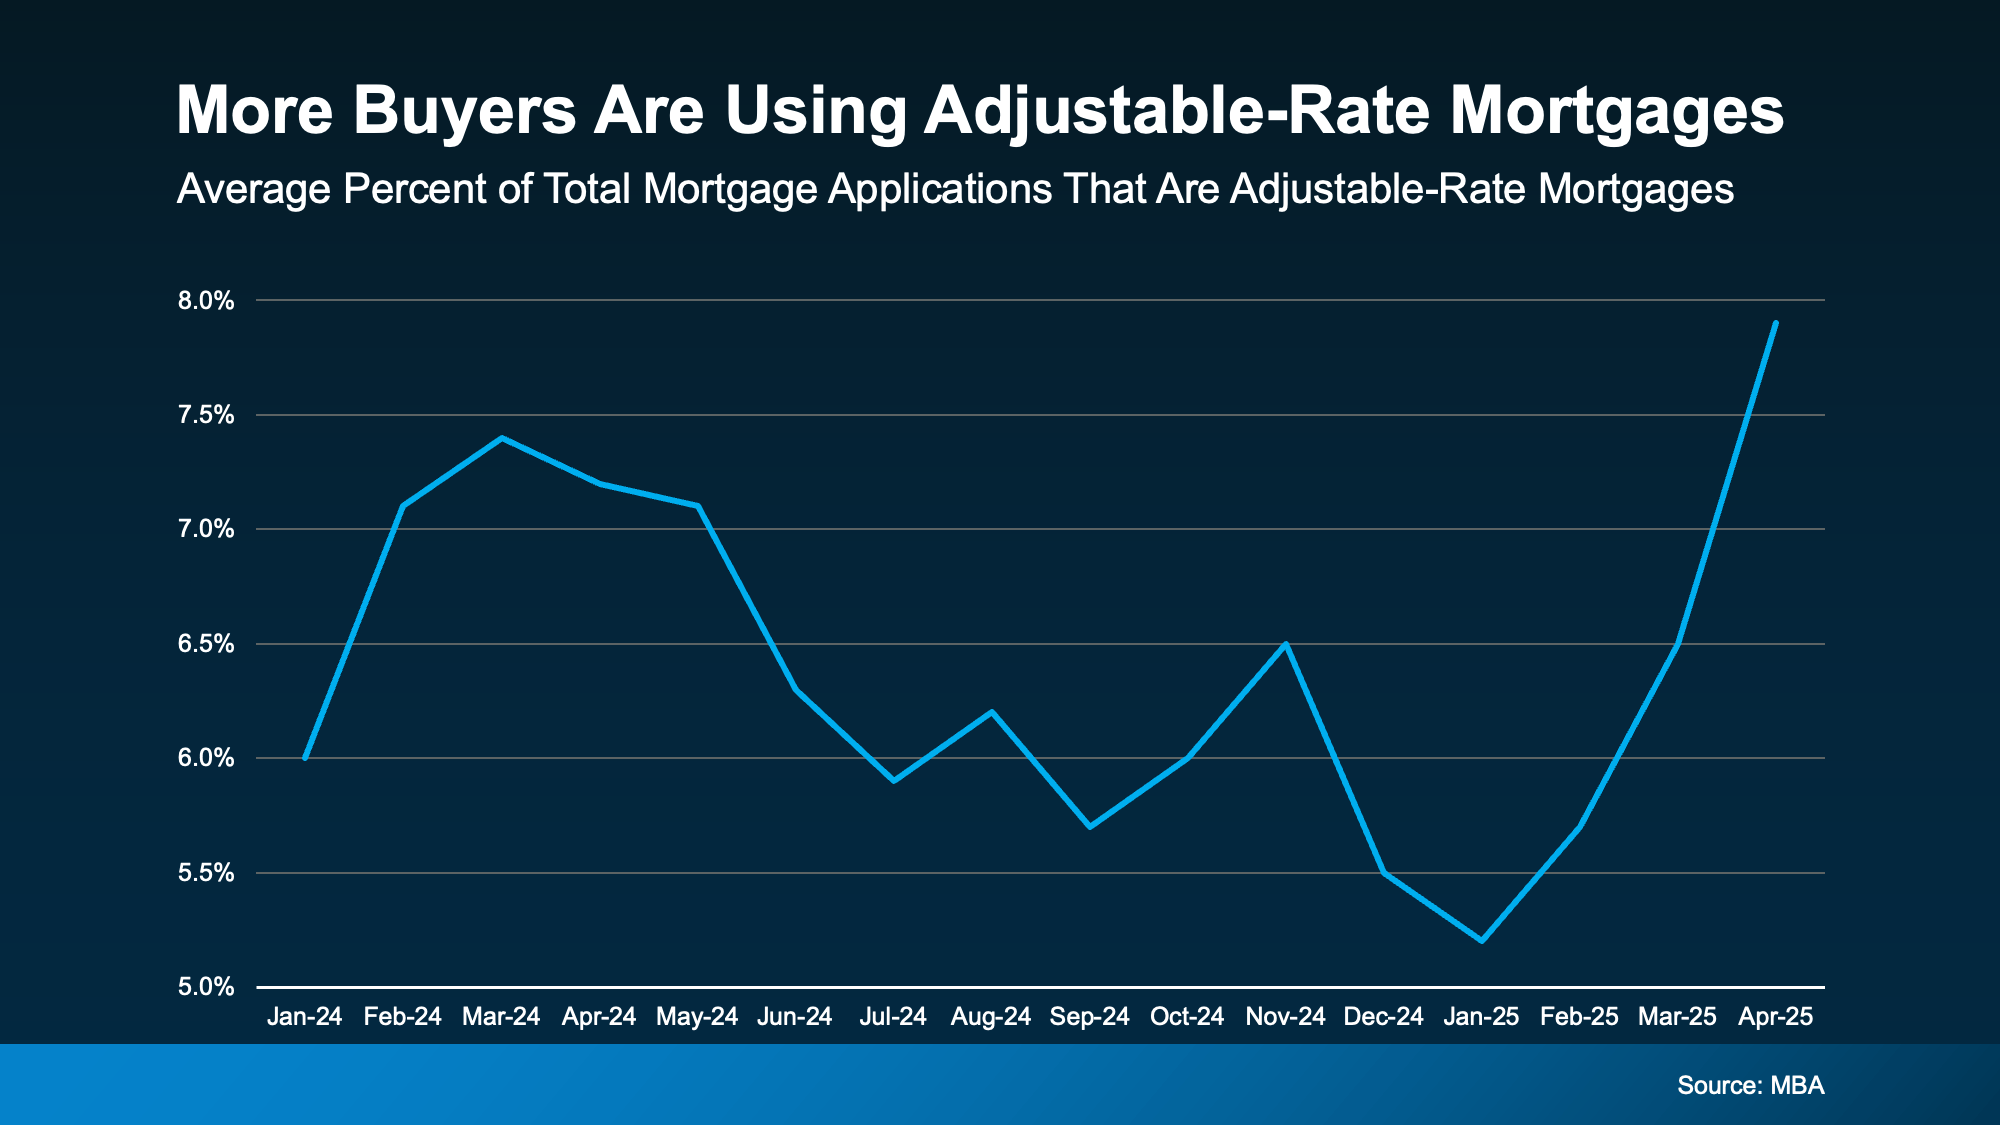
You can see the recent trend in this data from the Mortgage Bankers Association (MBA). More people are opting for ARMs right now (see graph below):

a graph showing a lineAnd while ARMs aren’t right for everyone, in certain situations they do have their benefits.

How an Adjustable-Rate Mortgage Works

Here’s how Business Insider explains the main difference between a fixed-rate mortgage and an adjustable-rate mortgage:

“With a fixed-rate mortgage, your interest rate remains the same for the entire time you have the loan. This keeps your monthly payment the same for years . . . adjustable-rate mortgages work differently. You'll start off with the same rate for a few years, but after that, your rate can change periodically. This means that if average rates have gone up, your mortgage payment will increase. If they've gone down, your payment will decrease.”

Of course, things like taxes or homeowner’s insurance can still have an impact on a fixed-rate loan, but the baseline of your mortgage payment doesn’t change much. Adjustable-rate mortgages don't work the same way.

Pros and Cons of an ARM

Here’s a little more information on why some buyers are giving ARMs another look. They offer some pretty appealing upsides, like a lower initial rate. As Business Insider explains:

"Because ARM rates are typically lower than fixed mortgage rates, they can help buyers find affordability when rates are high. With a lower ARM rate, you can get a smaller monthly payment or afford more house than you could with a fixed-rate loan."

On the flip side, just remember, if you have an ARM, your rate will change over time. As Barron’s explains there’s the potential for higher costs later:

"Adjustable-rate loans offer a lower initial rate, but recalculate after a period. That is a plus for borrowers if rates come down in the future, or if a borrower sells before the fixed period ends, but can lead to higher costs if they hold on to their home and rates go up."

So, while the upfront savings can be helpful now, you'll want to think through what could happen if you're still in that home when your initial rate ends. Because while projections show rates are expected to ease a bit over the next year or two, no forecast is guaranteed. 

That’s why it’s essential to talk with your lender and financial advisor about all your options and whether an ARM aligns with your financial goals and your comfort with risk.

Bottom Line

For the right buyer, ARMs can offer some big advantages. But they’re not one-size-fits-all. The key is understanding how they work, weighing the pros and cons, and thinking through if they’d be something that would work for you financially. And that’s why you need to talk to a trusted lender and financial advisor before you make any decisions.

The information contained, and the opinions expressed, in this article are not intended to be construed as investment advice. Keeping Current Matters, Inc. does not guarantee or warrant the accuracy or completeness of the information or opinions contained herein. Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision. Keeping Current Matters, Inc. will not be liable for any loss or damage caused by your reliance on the information or opinions contained herein.

Posted in Market Updates
May 21, 2025

More Homes for Sale Isn’t a Warning Sign – It's Your Buying Opportunity

More Homes for Sale Isn’t a Warning Sign – It's Your Buying Opportunity

BLOGMay 21, 2025

Maybe you’ve heard the number of homes for sale has reached a recent high. And it might make you question if this is the start of another housing market crash.

But the reality is, the data proves that’s just not the case. In most areas, more inventory isn’t bad news. It’s actually a sign of the market returning to a more stable, healthy place.

What’s Going on With Inventory?

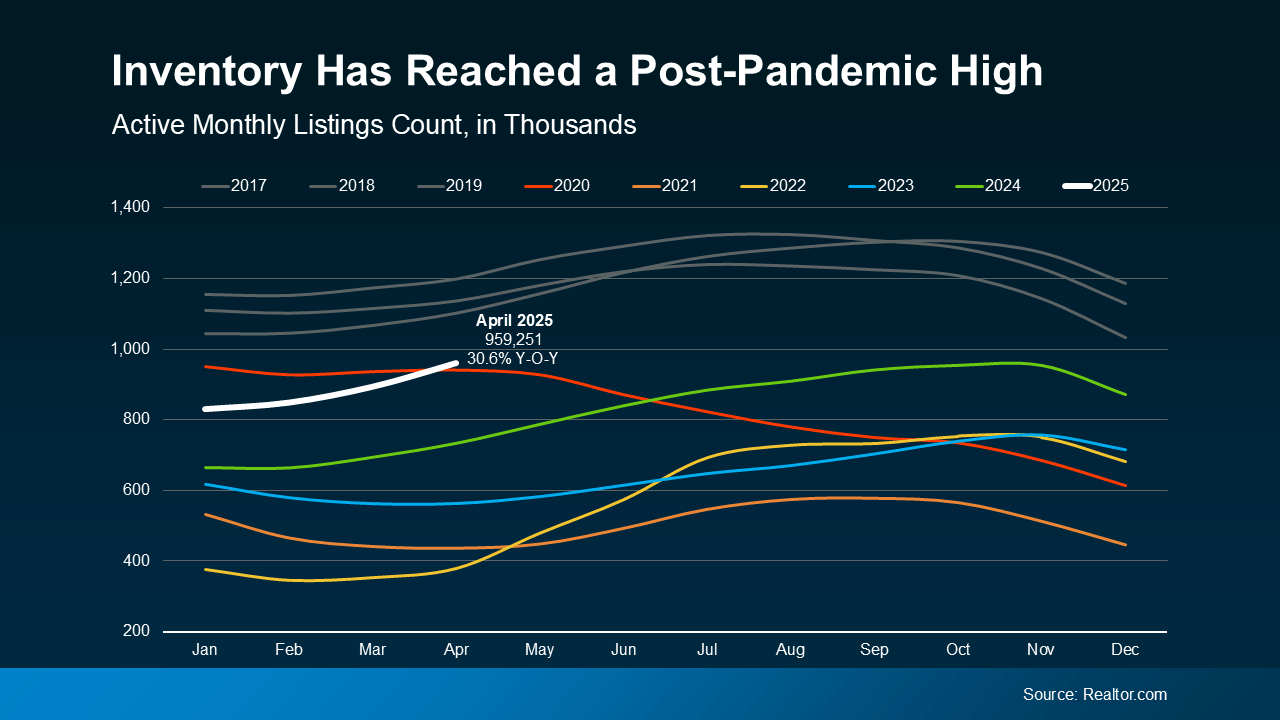
Based on the latest data from Realtor.com, inventory just hit its highest point since 2020, shown with the white line in the graph below.

But what you need to realize is, at the same time, inventory levels still haven’t returned to pre-pandemic norms (shown in gray):

a graph of different colored linesThat means there are more homes for sale now than there have been in quite some time.

And while it’s true inventory is up significantly compared to where it was over the last few years, the number of homes on the market is still well below typical levels. And that’s important context.

Why This Isn’t the Problem A Lot of People Think It Is

Some people hear inventory’s rising and immediately think about 2008. Because back then, inventory spiked just before the market crashed. But today’s situation is very different.

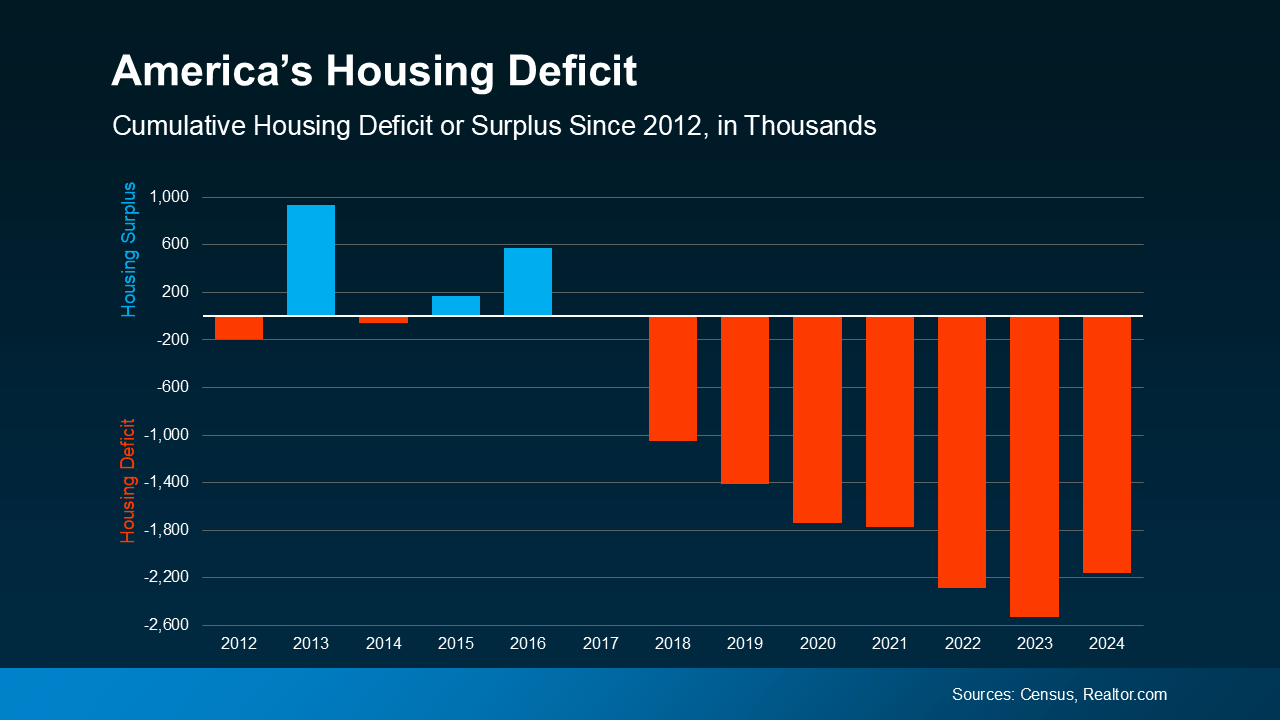
Here’s the key reason why. We don’t have a surplus of homes; we have a deficit to climb out of. What we’re dealing with is a long-term housing shortage – and it’s a big one.

The red bars in the graph below show all the years where housing starts (new builds) didn’t keep up with household formation, going all the way back to 2012. The deeper the bars in the graph, the more the housing deficit grew (see graph below):

a graph of a graph showing the value of a housing deficitAnd one of the reasons this housing shortage kept growing is because new home construction just didn’t keep up with the number of people who need to buy homes. In fact, the U.S. is actually short millions of homes at this point, and it will take years to overcome that gap. Realtor.com says:

“At a 2024 rate of construction relative to household formations and pent-up demand, it would take 7.5 years to close the housing gap.”

That means, in most areas, there isn’t a risk of having too many houses on the market right now. It’s quite the opposite – a vast majority of markets actually need more homes.

Which is why, even though inventory is rising, it’s not a problem on a national scale. It’s just helping to fill a gap that’s been growing for years.

Bottom Line

Don’t let the headlines scare you. Rising inventory isn’t a sign of a crash. It’s a step toward a more normal, stable housing market.

The information contained, and the opinions expressed, in this article are not intended to be construed as investment advice. Keeping Current Matters, Inc. does not guarantee or warrant the accuracy or completeness of the information or opinions contained herein. Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision. Keeping Current Matters, Inc. will not be liable for any loss or damage caused by your reliance on the information or opinions contained herein.

Posted in Market Updates
May 16, 2025

Housing Market Forecasts for the Second Half of 2025

Housing Market Forecasts for the Second Half of 2025

INFOGRAPHICMay 16, 2025

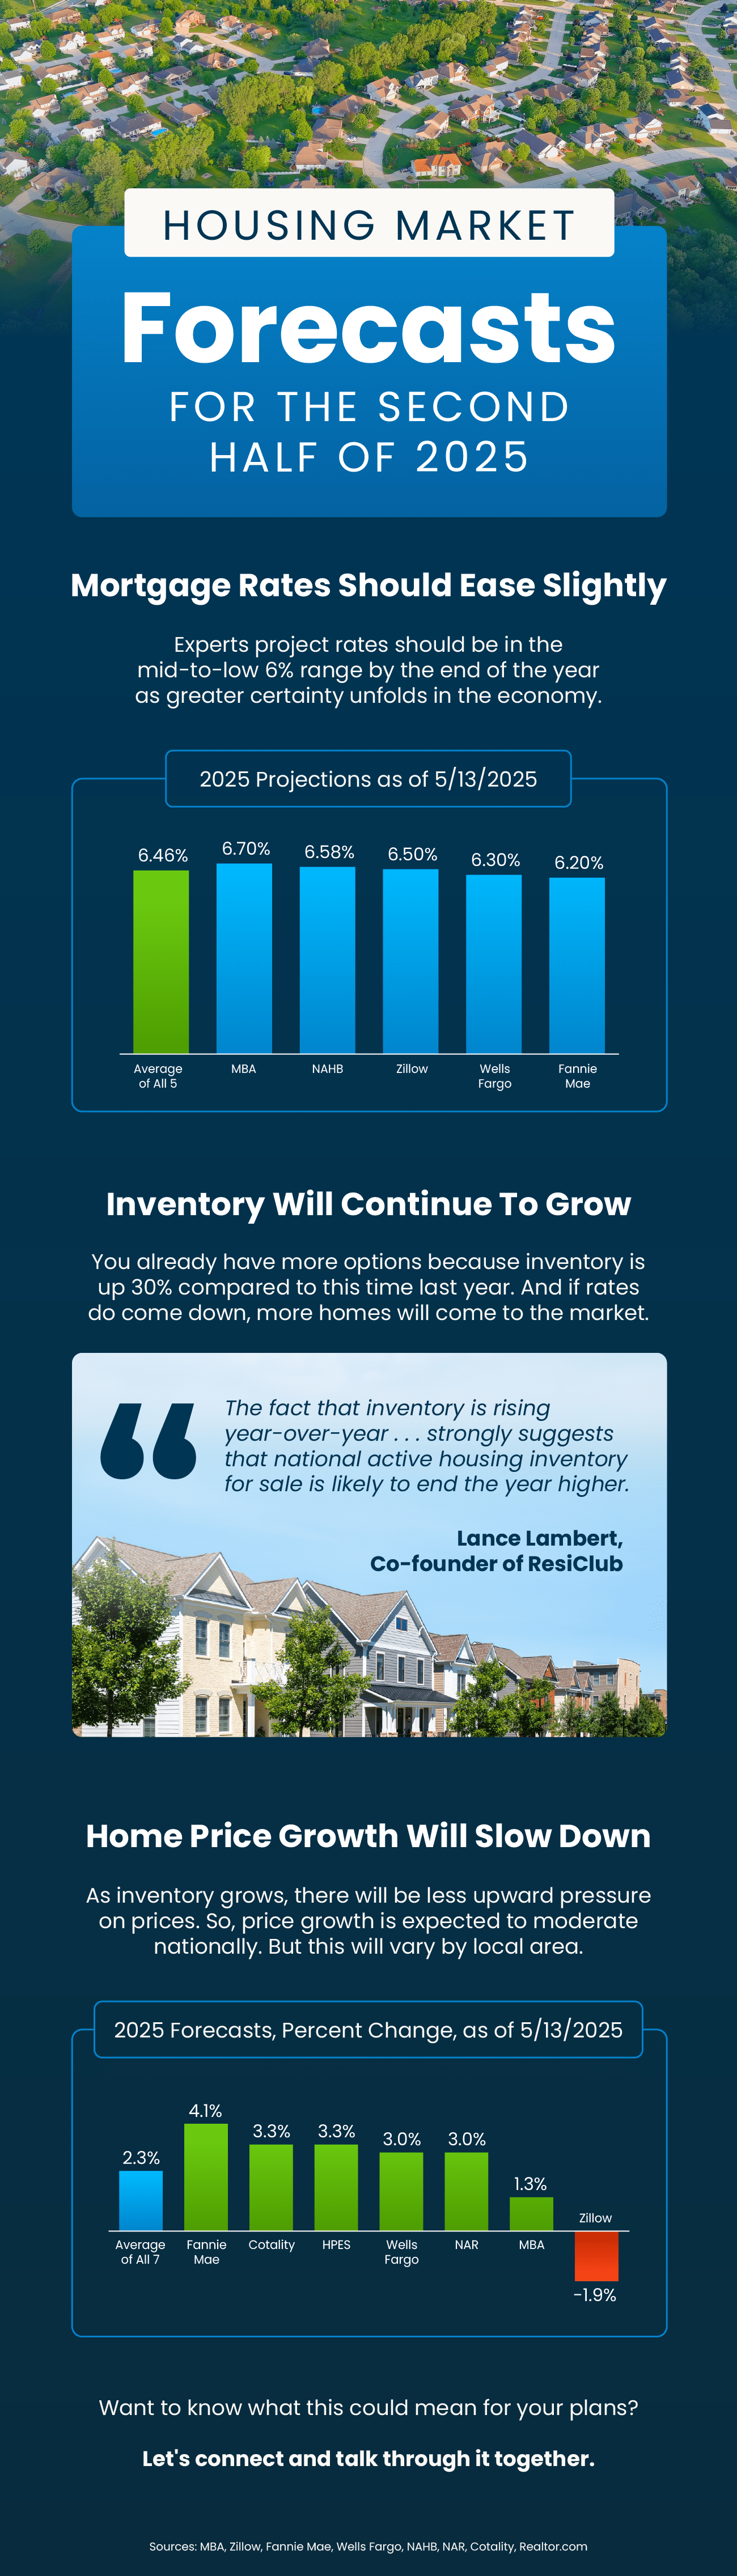
a screenshot of a mobile app

Some Highlights

• Are you wondering what to expect if you buy or sell a home in the second half of the year? Here’s what the expert forecasts tell you.

• Mortgage rates are expected to come down slightly. There will be more homes available for sale. And as inventory rises, home price growth will moderate.

• Want to know what this could mean for your plans? Let's connect and talk through it together.

The information contained, and the opinions expressed, in this article are not intended to be construed as investment advice. Keeping Current Matters, Inc. does not guarantee or warrant the accuracy or completeness of the information or opinions contained herein. Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision. Keeping Current Matters, Inc. will not be liable for any loss or damage caused by your reliance on the information or opinions contained herein.

Posted in Market Updates
May 16, 2025

Why Would I Move with a 3% Mortgage Rate?

Why Would I Move with a 3% Mortgage Rate?

BLOGMay 15, 2025

If you have a 3% mortgage rate, you’re probably pretty hesitant to let that go. And even if you’ve toyed with the idea of moving, this nagging thought may be holding you back: “why would I give that up?”

But when you ask that question, you may be putting your needs on the back burner without realizing it. Most people don’t move because of their mortgage rate. They move because they want or need to. So, let’s flip the script and ask this instead: 

What are the chances you’ll still be in your current house 5 years from now?

Think about your life for a moment. Picture what the next few years will hold. Are you planning on growing your family? Do you have adult children about to move out? Is retirement on the horizon? Are you already bursting at the seams?

If nothing’s going to change, and you love where you are, staying put might make perfect sense. But if there’s even a slight chance a move is coming, even if it’s not immediate, it’s worth thinking about your timeline.

Because even a year or two can make a big difference in what your next home might cost you.

What the Experts Say About Home Prices over the Next 5 Years

Each quarter, Fannie Mae asks more than 100 housing market experts to weigh in on where they project home prices are headed. And the consensus is clear. Home prices are expected to rise through at least 2029 (see graph below):

a graph of a graph showing the price of risingWhile those projections aren’t calling for big increases each year, it's still an increase. And sure, some markets may see flatter prices or slower growth, or even slight dips in the short term. But look further out. In the long run, prices almost always rise. And over the next 5 years, the anticipated increase – however slight – will add up fast.

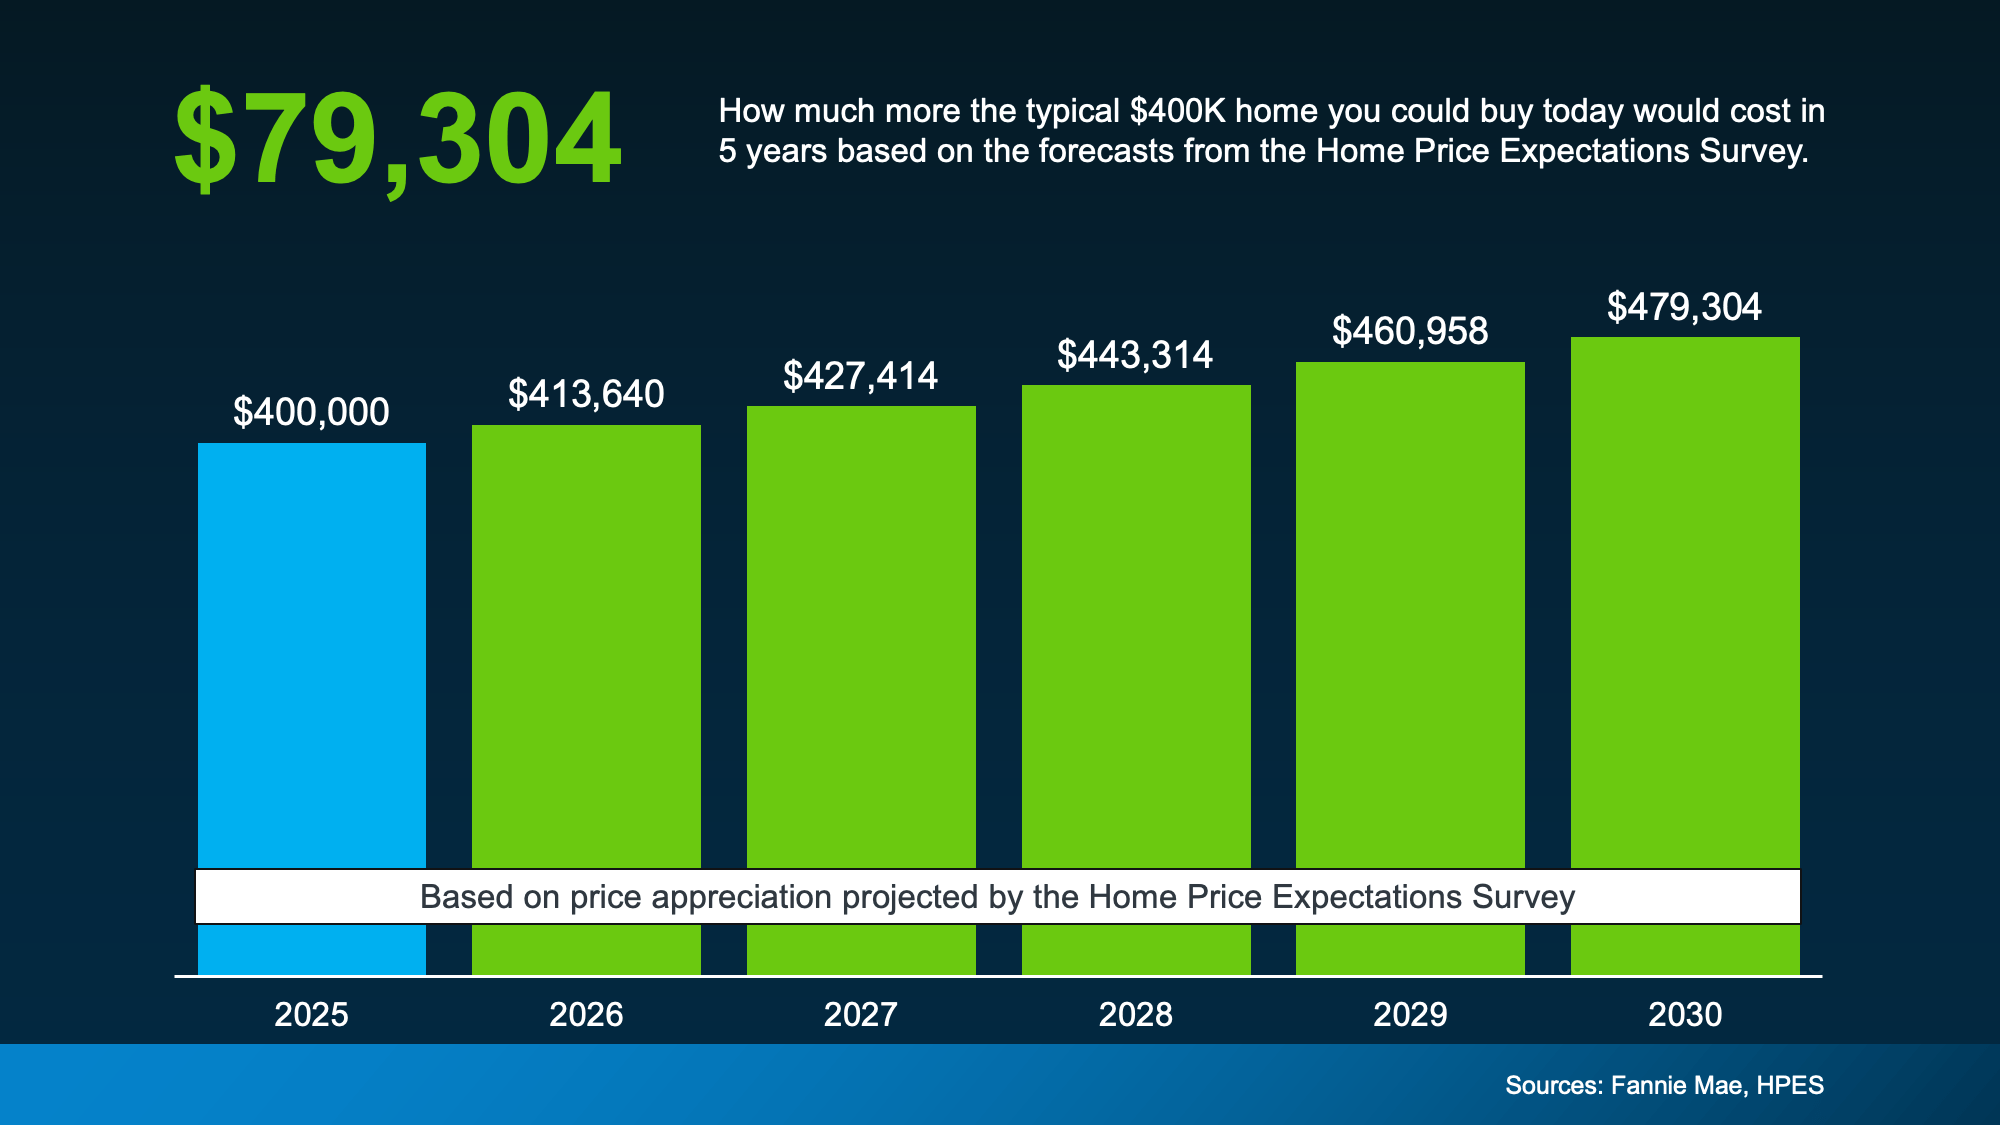
Here’s an example. Let's say you'll be looking to buy a roughly $400,000 house when you move. If you wait and move 5 years from now, based on these expert projections, it could cost nearly $80,000 more than it would now (see graph below):

That means the longer you wait, the more your future home will cost you. 
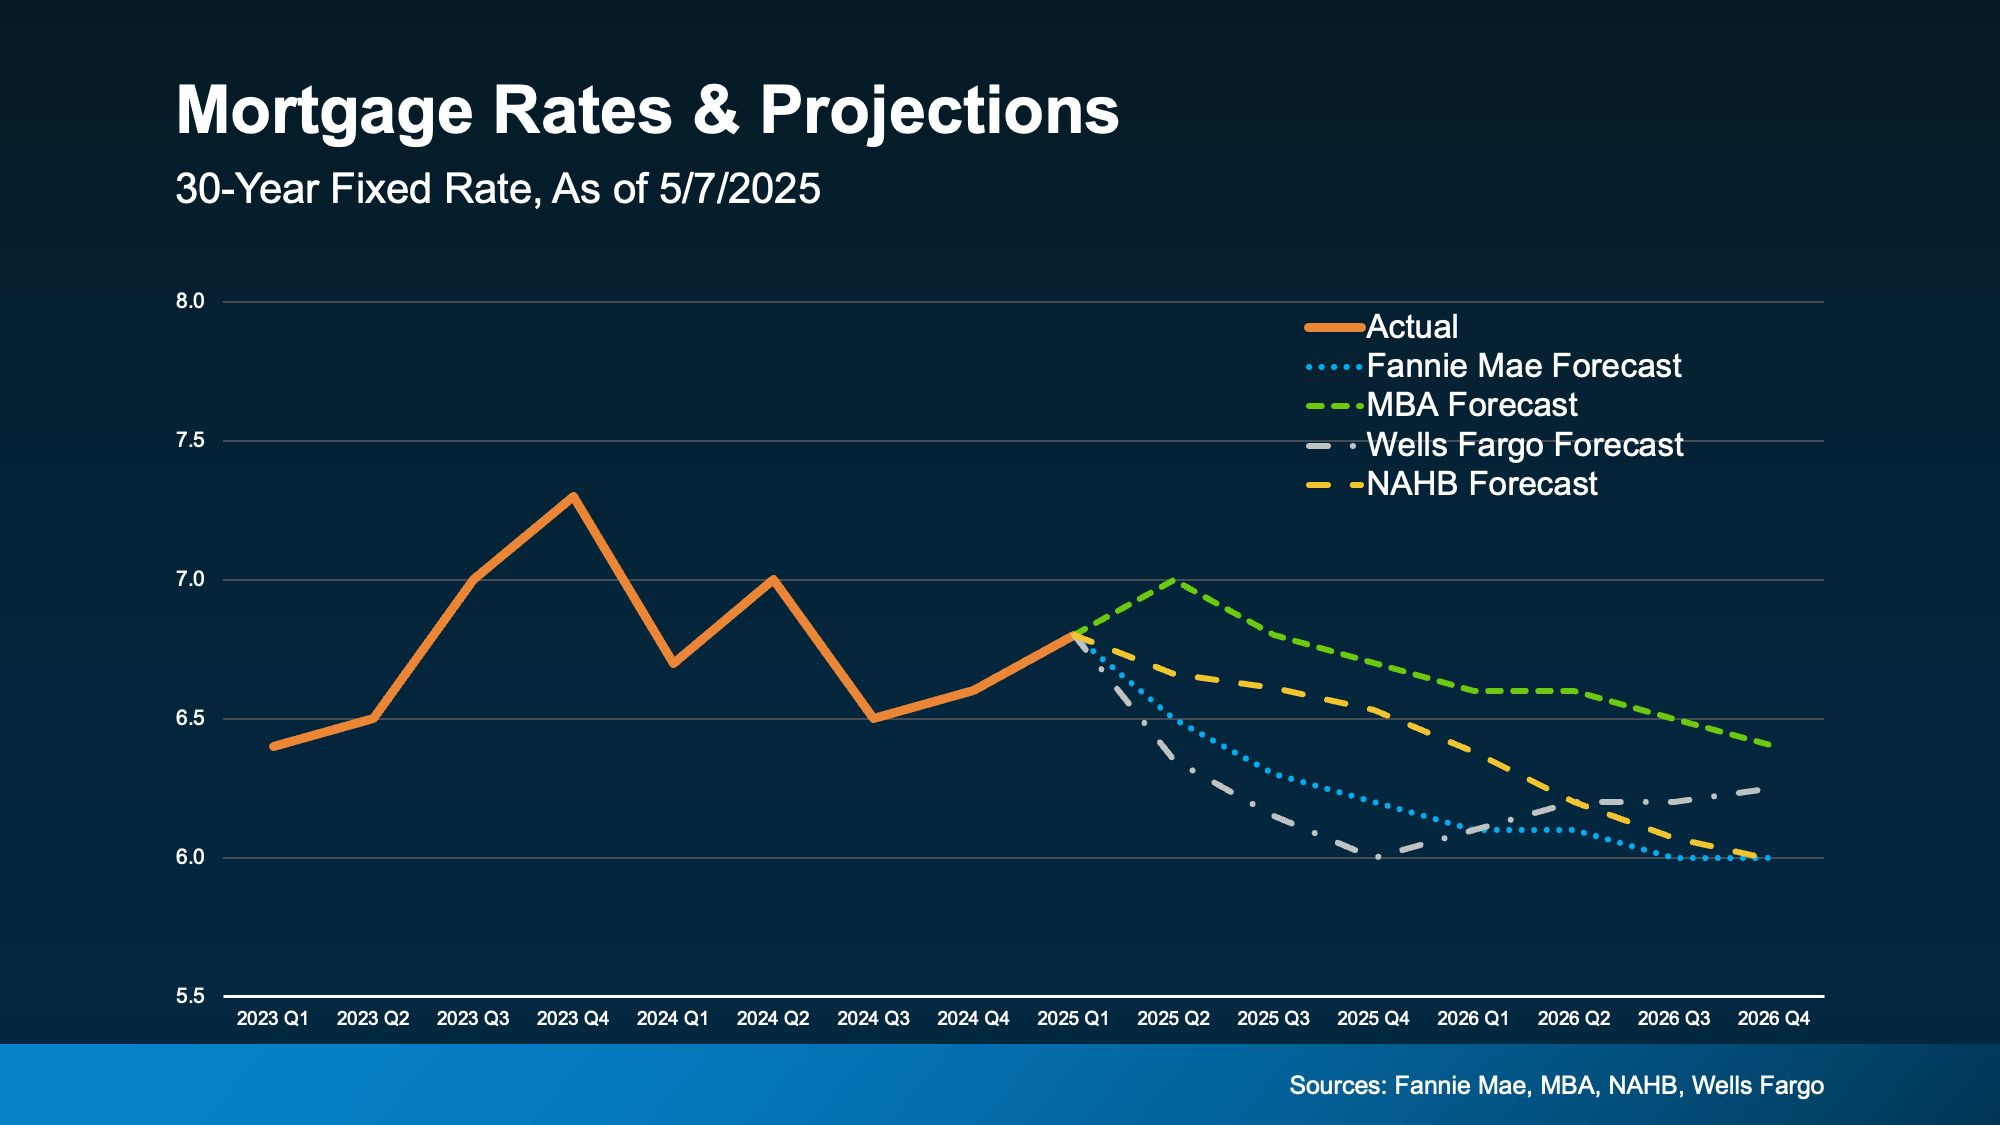
If you know a move is likely in your future, it may make sense to really think about your timeline. You certainly don't have to move now. But financially, it may still be worth having a conversation about your options before prices inch higher. Because while rates are expected to come down, it’s not by much. And if you’re holding out in hopes we’ll see the return of 3% rates, experts agree it’s just not in the cards (see graph below): 

a graph with lines and numbersSo, the question really isn’t: “why would I move?” It’s: “when should I?” – because when you see the real numbers, waiting may not be the savings strategy you thought it was. And that’s the best conversation you can have with your trusted agent right now.

Bottom Line

Keeping that low mortgage rate is smart – until it starts holding you back.

If a move is likely on the horizon for you, even if it’s a few years down the line, it’s worth thinking through the numbers now, so you can plan ahead.

What other price point do you want to see these numbers for? Let’s have that conversation, so I can show you how the math adds up. That way, you can make an informed decision about your timeline.

The information contained, and the opinions expressed, in this article are not intended to be construed as investment advice. Keeping Current Matters, Inc. does not guarantee or warrant the accuracy or completeness of the information or opinions contained herein. Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision. Keeping Current Matters, Inc. will not be liable for any loss or damage caused by your reliance on the information or opinions contained herein.

Posted in Market Updates
May 14, 2025

Don’t Let Student Loans Hold You Back from Homeownership

Don’t Let Student Loans Hold You Back from Homeownership

BLOGMay 14, 2025

Did you know? According to a recent study, 72% of people with student loans think their debt will delay their ability to buy a home. Maybe you’re one of them and you're wondering:

  • Do you have to wait until you’ve paid off those loans before you can buy your first home?
  • Or is it possible you could still qualify for a home loan even with that debt?

Having questions like these is normal, especially when you’re thinking about making such a big purchase. But you should know, you may be putting your homeownership goals on the backburner unnecessarily.

Can You Qualify for a Home Loan if You Have Student Loans?

In the simplest sense, what you want to know is can you still buy your first home if you have student debt. Here’s what Yahoo Finance says:

" . . . student loans don’t have to get in your way when it comes to becoming a homeowner. With the right approach and an understanding of how debt impacts your home-buying options, buying a house when you have student loans is possible."

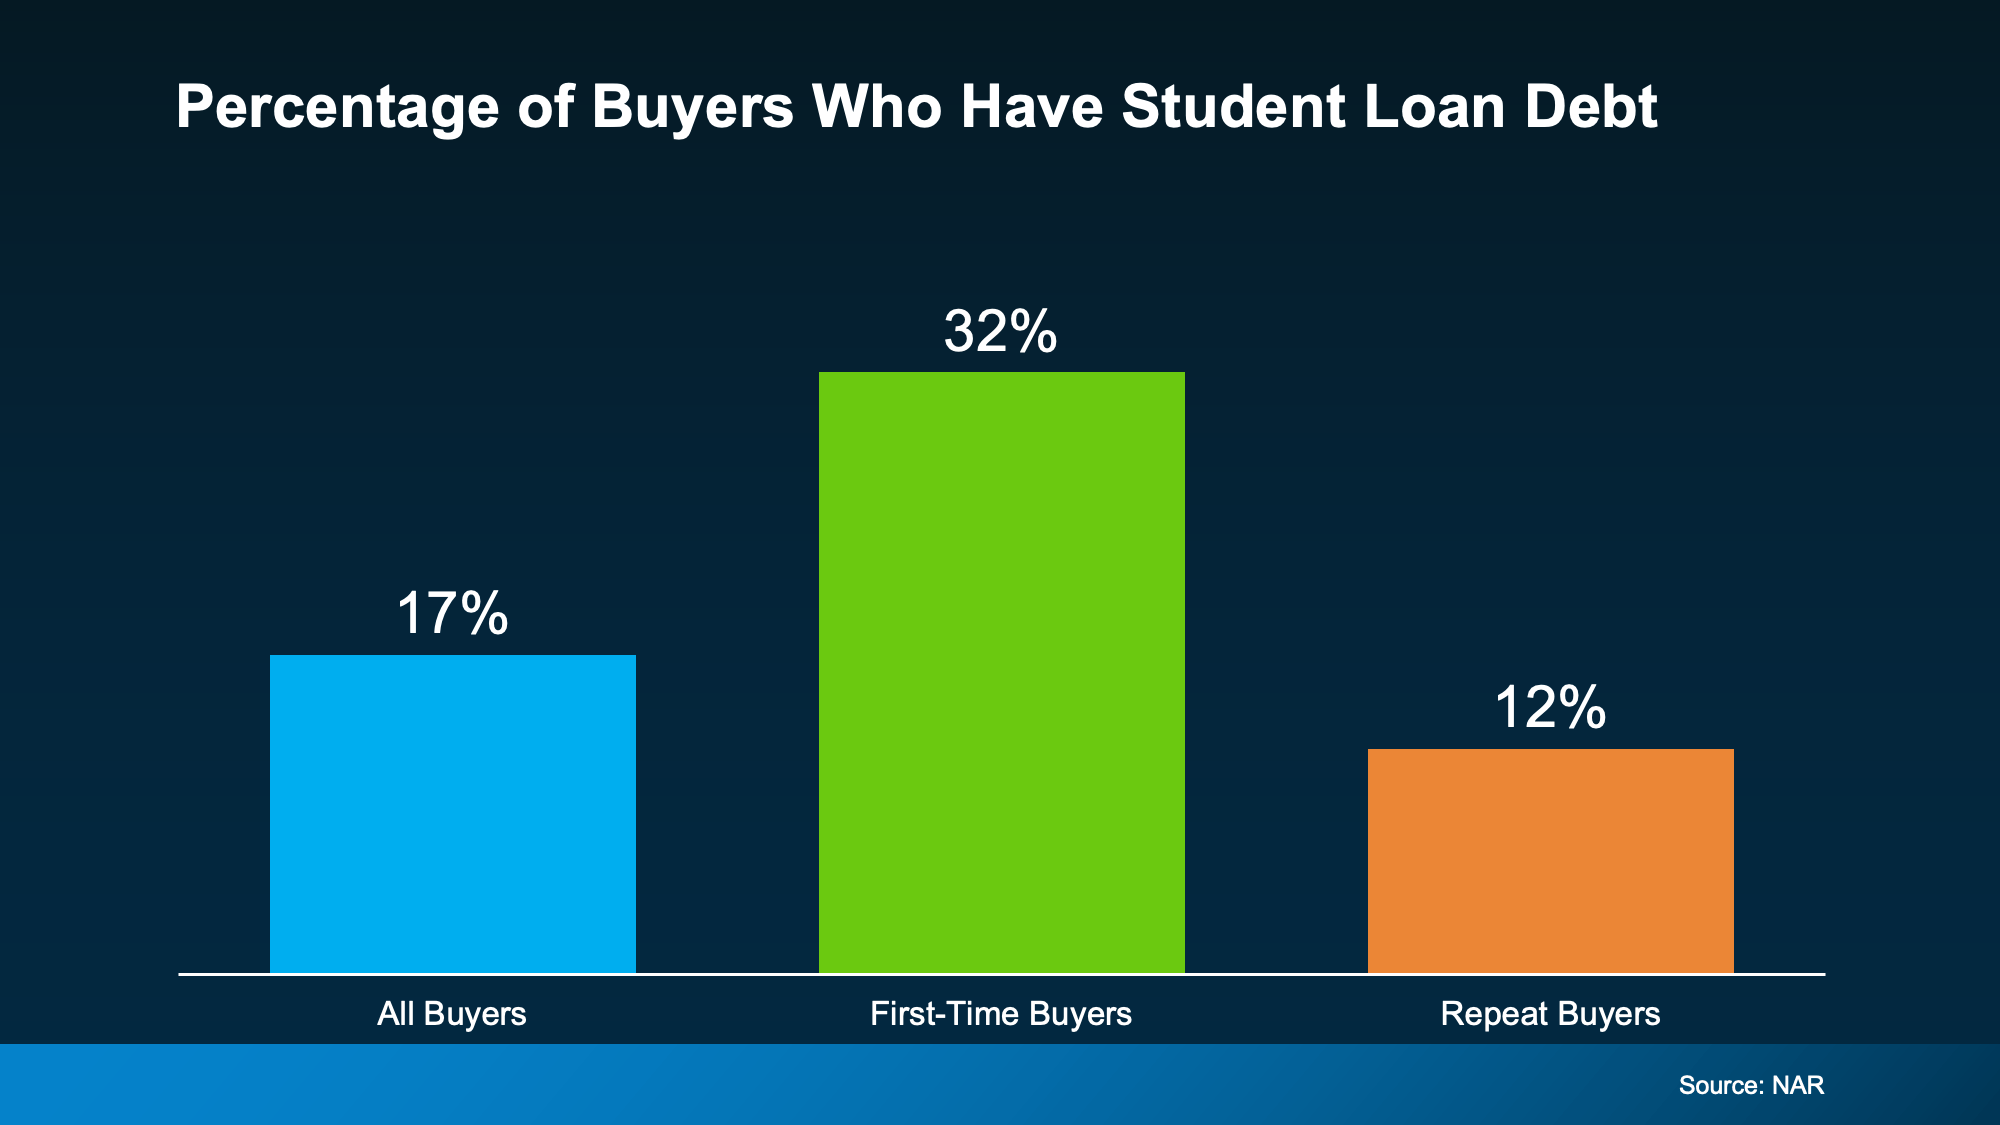
And the data backs this up. An annual report from the National Association of Realtors (NAR), shows that 32% of first-time buyers had student loan debt (see graph below): 

a graph of a student loanWhile everyone’s situation is unique, your goal may be more doable than you realize. Plenty of people with student loans have been able to qualify for and buy a home. Let that reassure you that it is still possible, even as a first-time buyer. And just in case it’s helpful to know, the median student loan debt was $30,000. As an article from Chase says:

“It’s important to note that student loans usually don’t affect your ability to qualify for a mortgage any differently than other types of debt you have on your credit report, such as credit card debt and auto loans.”

If your income is steady and your overall finances are solid, homeownership can still be within reach. So, having student loans doesn’t necessarily mean you have to wait to buy a home.

Bottom Line

Having student loans doesn’t mean buying a home is off the table. Before you count yourself out, talk to a lender to get a clearer picture of what you can afford and how close you are to taking the first step toward homeownership.

The information contained, and the opinions expressed, in this article are not intended to be construed as investment advice. Keeping Current Matters, Inc. does not guarantee or warrant the accuracy or completeness of the information or opinions contained herein. Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision. Keeping Current Matters, Inc. will not be liable for any loss or damage caused by your reliance on the information or opinions contained herein.

Posted in Market Updates
May 13, 2025

Why Buyers Are More Likely To Get Concessions Right Now

Why Buyers Are More Likely To Get Concessions Right Now

BLOGMay 13, 2025

Especially in areas where inventory is rising, both homebuilders and sellers are sweetening the deal for buyers with things like paid closing costs, mortgage rate buy-downs, and more. In the industry, it’s called a concession or an incentive.

What Are Concessions and Incentives?

When a seller or builder gives you something extra to help with your purchase, that’s called either a concession or an incentive. 

  • A concession is something a seller gives up or agrees to in order to reach a compromise and close a deal. 
  • An incentive, on the other hand, is a benefit a builder or seller advertises and offers up front to attract and encourage buyers.

Today, some of the most common ones are:

  • Help with closing costs
  • Mortgage rate buy-downs (to temporarily lower your rate)
  • Discounts or price reductions
  • Upgrades or appliances
  • Home warranties
  • Minor repairs

For buyers, getting any of these things thrown in can be a big deal – especially if you’re working with a tight budget. As the National Association of Realtors (NAR) says: 

“. . . they can help reduce the upfront costs associated with purchasing a home.”

Builders Are Making It Easier To Buy

It’s not just one builder willing to toss in a few extras. A lot of builders are using this tactic lately. As Zonda says:

“Incentives continued to be popular in March, offered by builders on 56% of to-be-built homes and 74% of quick move-in (QMI) homes, which can likely be occupied within 90 days.”

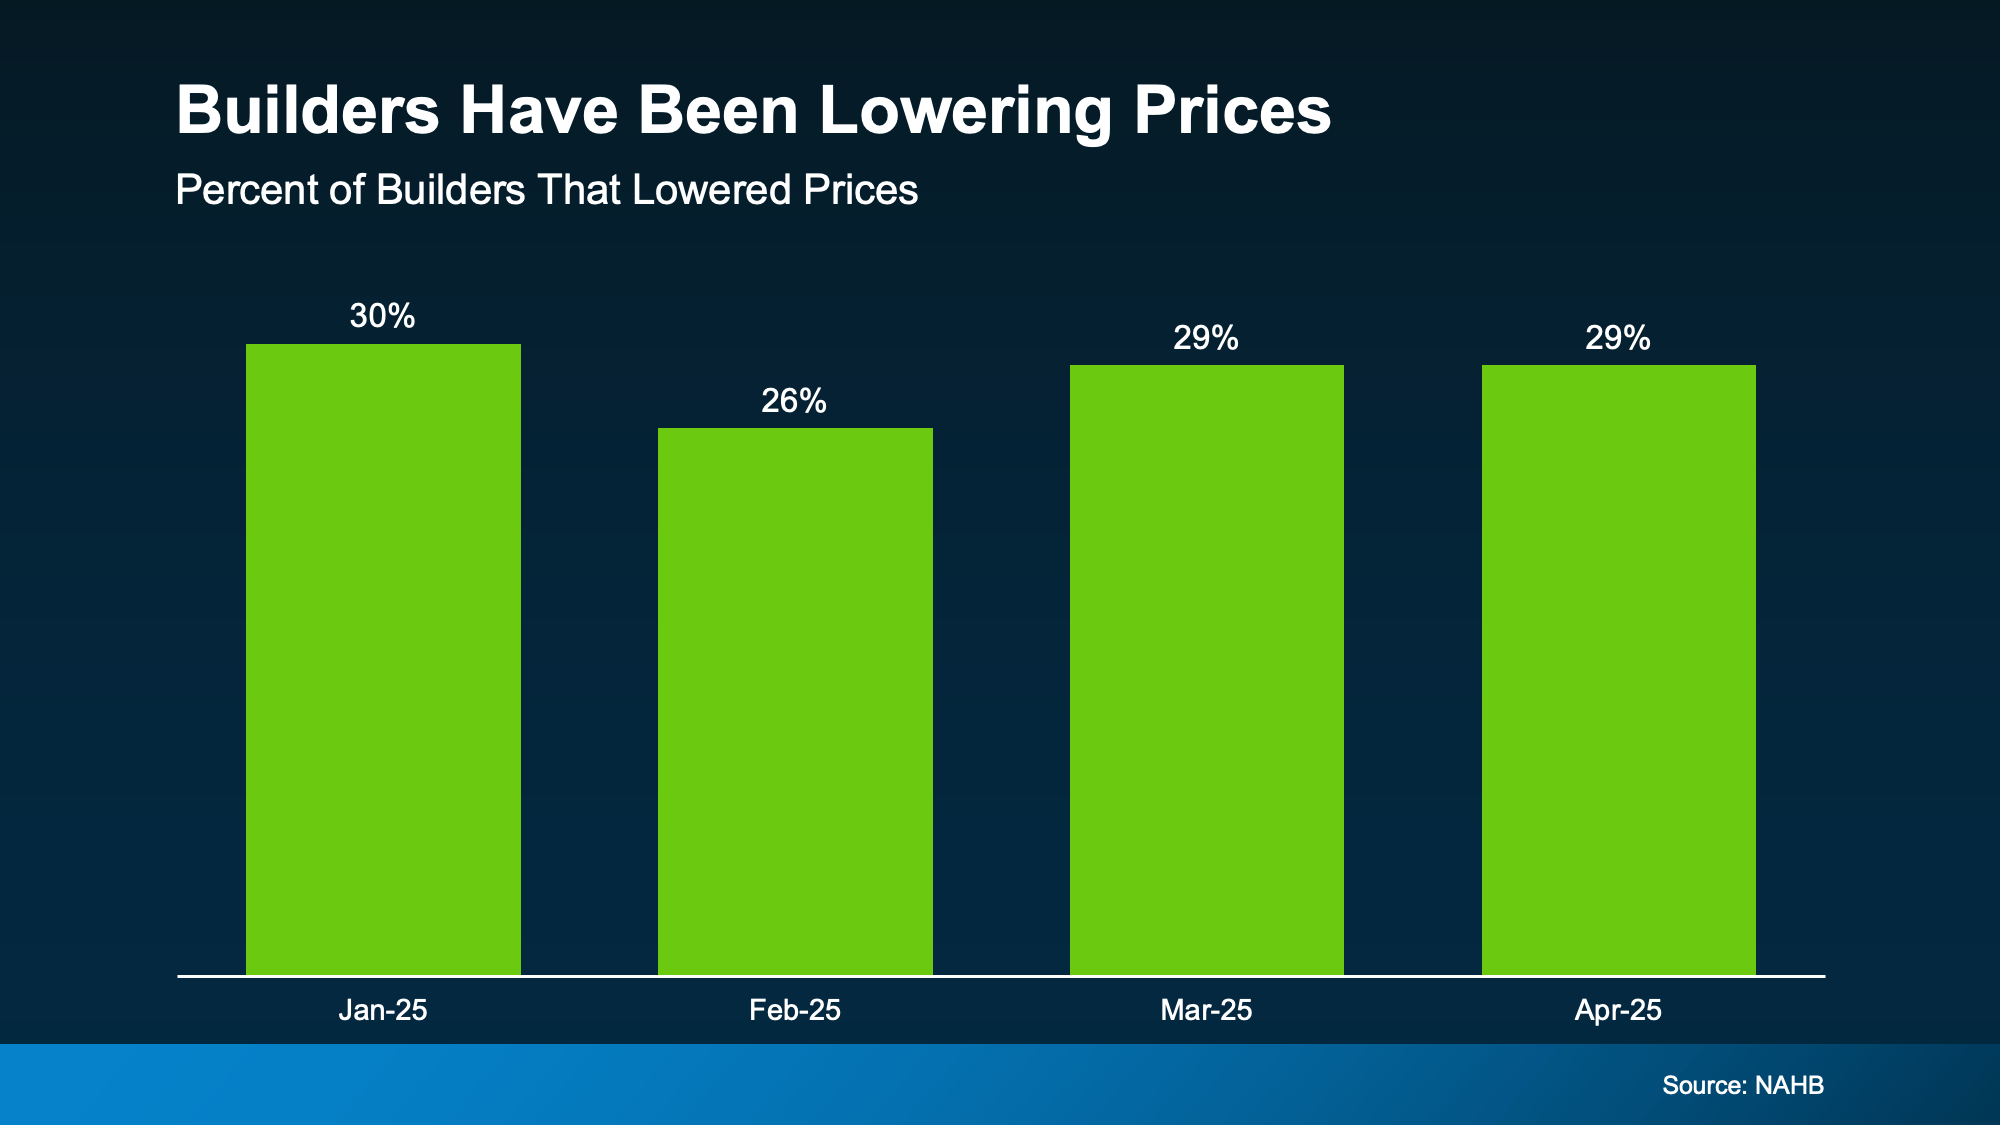
That’s because they don’t want to sit on inventory for too long. They want it to sell. And according to the National Association of Home Builders (NAHB), one of the strategies many builders are using to keep that inventory moving (and not just sitting) is a price adjustment (see graph below): 

a graph of green rectangular barsAround 30% of builders lowered prices in each of the first four months of the year. While that also means most builders aren’t lowering prices, it also shows some are willing to negotiate with buyers to get a deal done.

This isn’t a sign of trouble in the market, it’s an opportunity for you. The fact that the majority of builders offer incentives and roughly 3 in 10 are lowering prices means if you're looking at a newly built home, your builder will probably try to make it easier for you to close the deal. 

Existing Home Sellers Are Offering More, Too

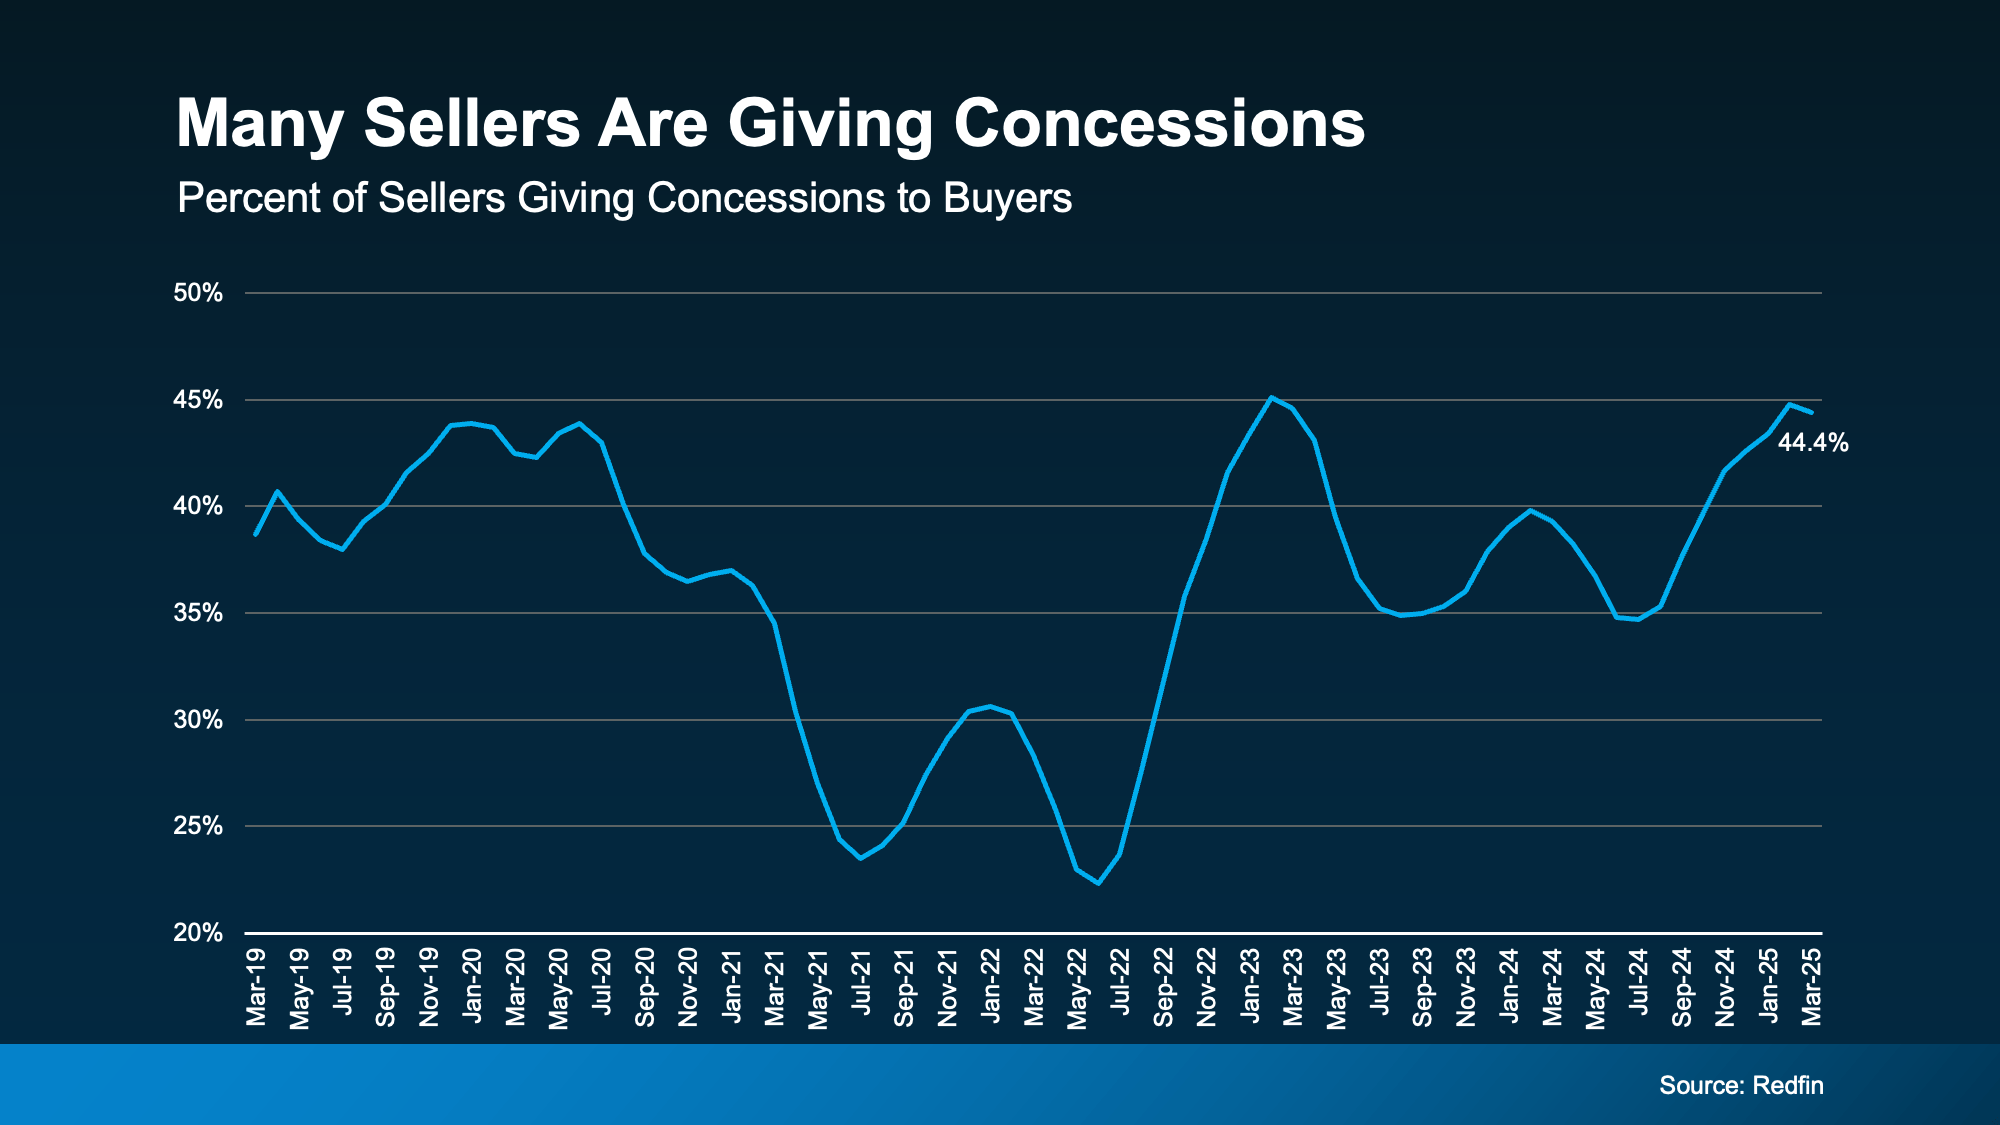
More existing homes (one that someone has lived in before) have been hitting the market, too – which means sellers are facing more competition. That’s why over 44% of sellers of existing homes gave concessions to buyers in March (see graph below):

a graph showing the price of a stock marketAnd, if you look back at pre-pandemic years on this graph, you’ll see 44% is pretty much returning to normal. After years of sellers having all the power, the market is balancing again, which can work in your favor as a buyer.

But remember, concessions don’t always mean a big discount. While more sellers are compromising on price, that’s not always the lever they pull. Sometimes it’s as simple as the seller paying for repairs, leaving appliances behind for you, or helping with your closing costs.

And considering that home values have risen by more than 57% over the course of the past 5 years, small concessions are a great way for sellers to make a house more attractive to buyers while still making a profit.

Bottom Line

Whether you’re looking at a newly built home or something a little older, there’s a good chance you can benefit from concessions or incentives.

If a seller or builder offered you something extra, what would make the biggest difference to help you move forward?

Let’s talk about it and see if it’s realistic based on inventory and competition in our local market.

The information contained, and the opinions expressed, in this article are not intended to be construed as investment advice. Keeping Current Matters, Inc. does not guarantee or warrant the accuracy or completeness of the information or opinions contained herein. Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision. Keeping Current Matters, Inc. will not be liable for any loss or damage caused by your reliance on the information or opinions contained herein.

Posted in Market Updates
May 12, 2025

Home Projects That Boost Value

Home Projects That Boost Value

BLOGMay 12, 2025

Whether you’re planning to move soon or not, it’s smart to be strategic about which home projects you take on. Your time, energy, and money matter – and not all upgrades offer the payoff you might expect. As U.S. News Real Estate explains:

". . . not every home renovation project will increase the resale value of a home. Before you invest in a swimming pool or new addition, you should consider whether the project will pay itself off by getting prospective buyers in the door when it’s time to sell."

That’s why, before you pick up a power tool or call a contractor, your first step should be talking to a local agent.

Planning Ahead Pays Off

If you plan to move relatively soon, you’ll want to get a jump start on your to-do list. And even if moving isn’t on your radar yet, life can change quickly – and a new job, a growing family, or shifting priorities can fast-track your plans. You don’t want to be scrambling to fix up your home if your timeline changes.

Smart updates now = fewer headaches later.

By planning ahead, you can spread out the work over time, which is easier on your wallet and your stress levels. Plus, you’ll get to enjoy the upgrades while you’re still living there and have the peace of mind your house is ready to impress when it's time to list.

What Buyers Want (and What’s Actually Worth Doing)

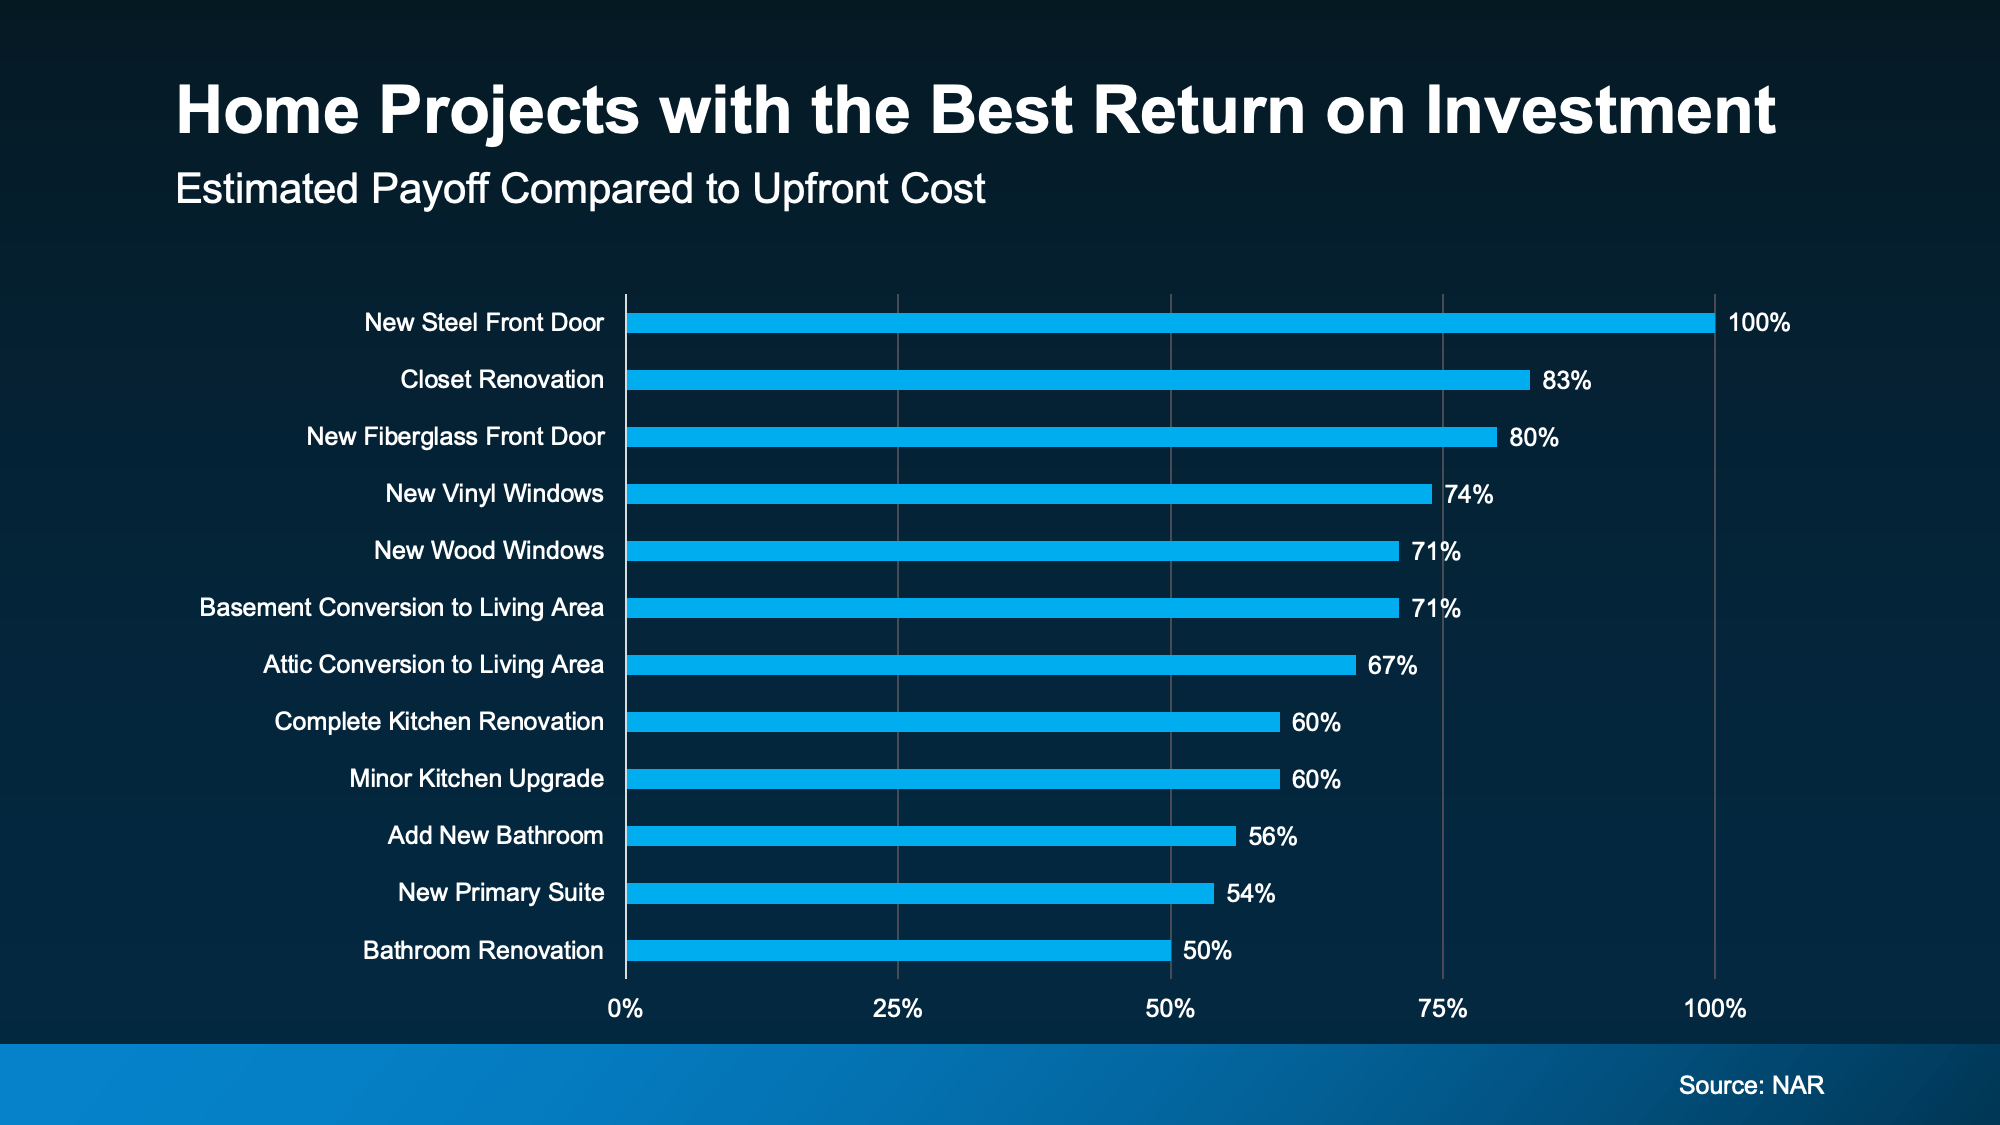
If you’re not sure which projects are worth your time and money – here's some information that can help. A study from the National Association of Realtors (NAR) shows which upgrades typically offer the best return on your investment (ROI) (see graph below):

a graph of a costIf an update you're already thinking about overlaps with those high-ROI upgrades, great. Odds are it'll improve your quality of life now and your home’s value later.

But don’t take this list as law. This is based on national data and is the sort of thing that's going to vary based on what’s most sought-after where you live. That’s where your agent comes in. As an article from Ramsey Solutions says:

“The best way to gauge what you can expect in terms of resale value on home improvements—especially if you’re planning to sell soon—is to talk to a real estate agent who is an expert in your market. They’re sure to know the local trends, and they can show you how other homes with the features you want to add are selling. That way, you can make an educated decision before you start ordering lumber and knocking down walls.”

You'll just want to make sure you don't overdo it. Too many high-end updates can make your home the priciest in the neighborhood. That might sound great, but it can actually turn buyers away if it's outside their expected price range for the area. The right agent will help you make smart updates that buyers will love, without going overboard. 

Whether the project is big or small, it pays to be strategic. And an agent is a key piece of that strategy.

Bottom Line

It doesn’t matter whether you plan to move soon or not, it can still pay off to make strategic updates that’ll help you love your home now and stand out later.

What’s one upgrade you’ve been thinking about – and wondering if it’s worth it? Let’s make sure it’ll pay off when the time comes.

The information contained, and the opinions expressed, in this article are not intended to be construed as investment advice. Keeping Current Matters, Inc. does not guarantee or warrant the accuracy or completeness of the information or opinions contained herein. Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision. Keeping Current Matters, Inc. will not be liable for any loss or damage caused by your reliance on the information or opinions contained herein.

Posted in Market Updates