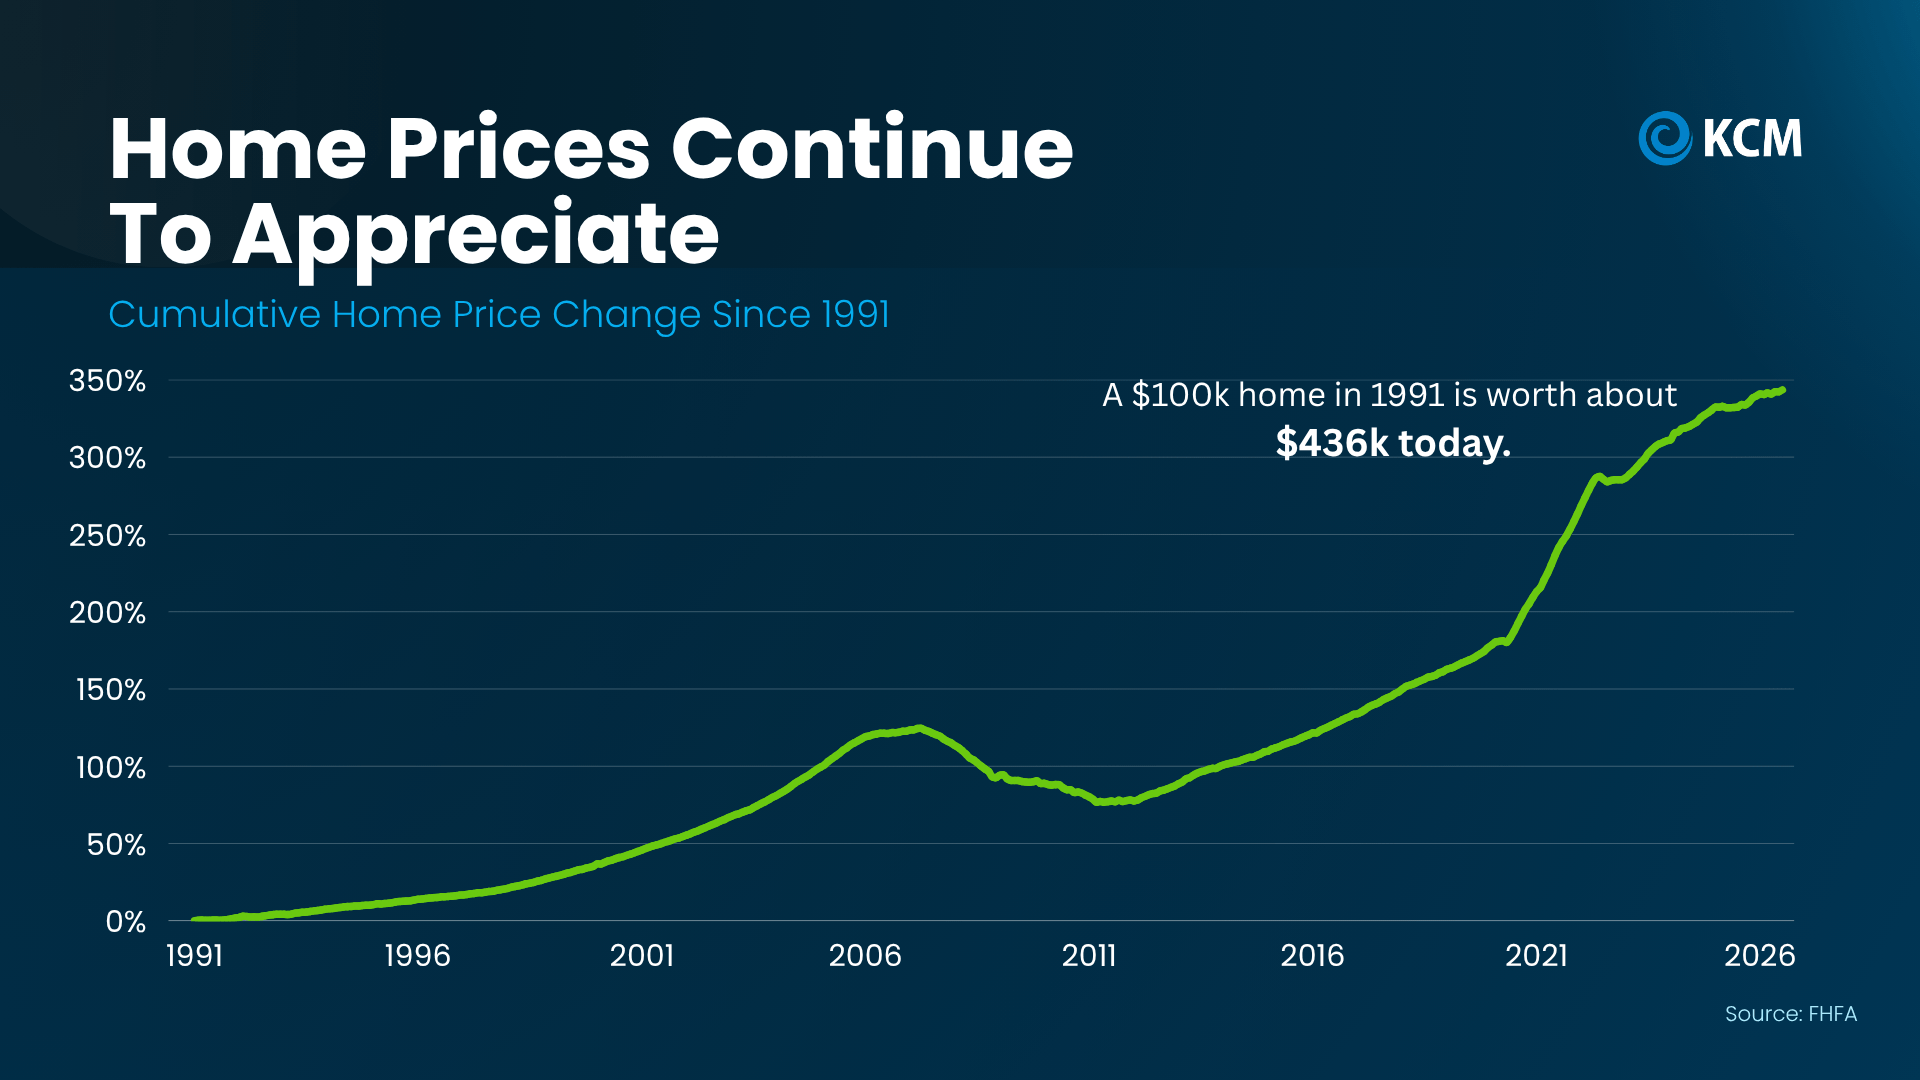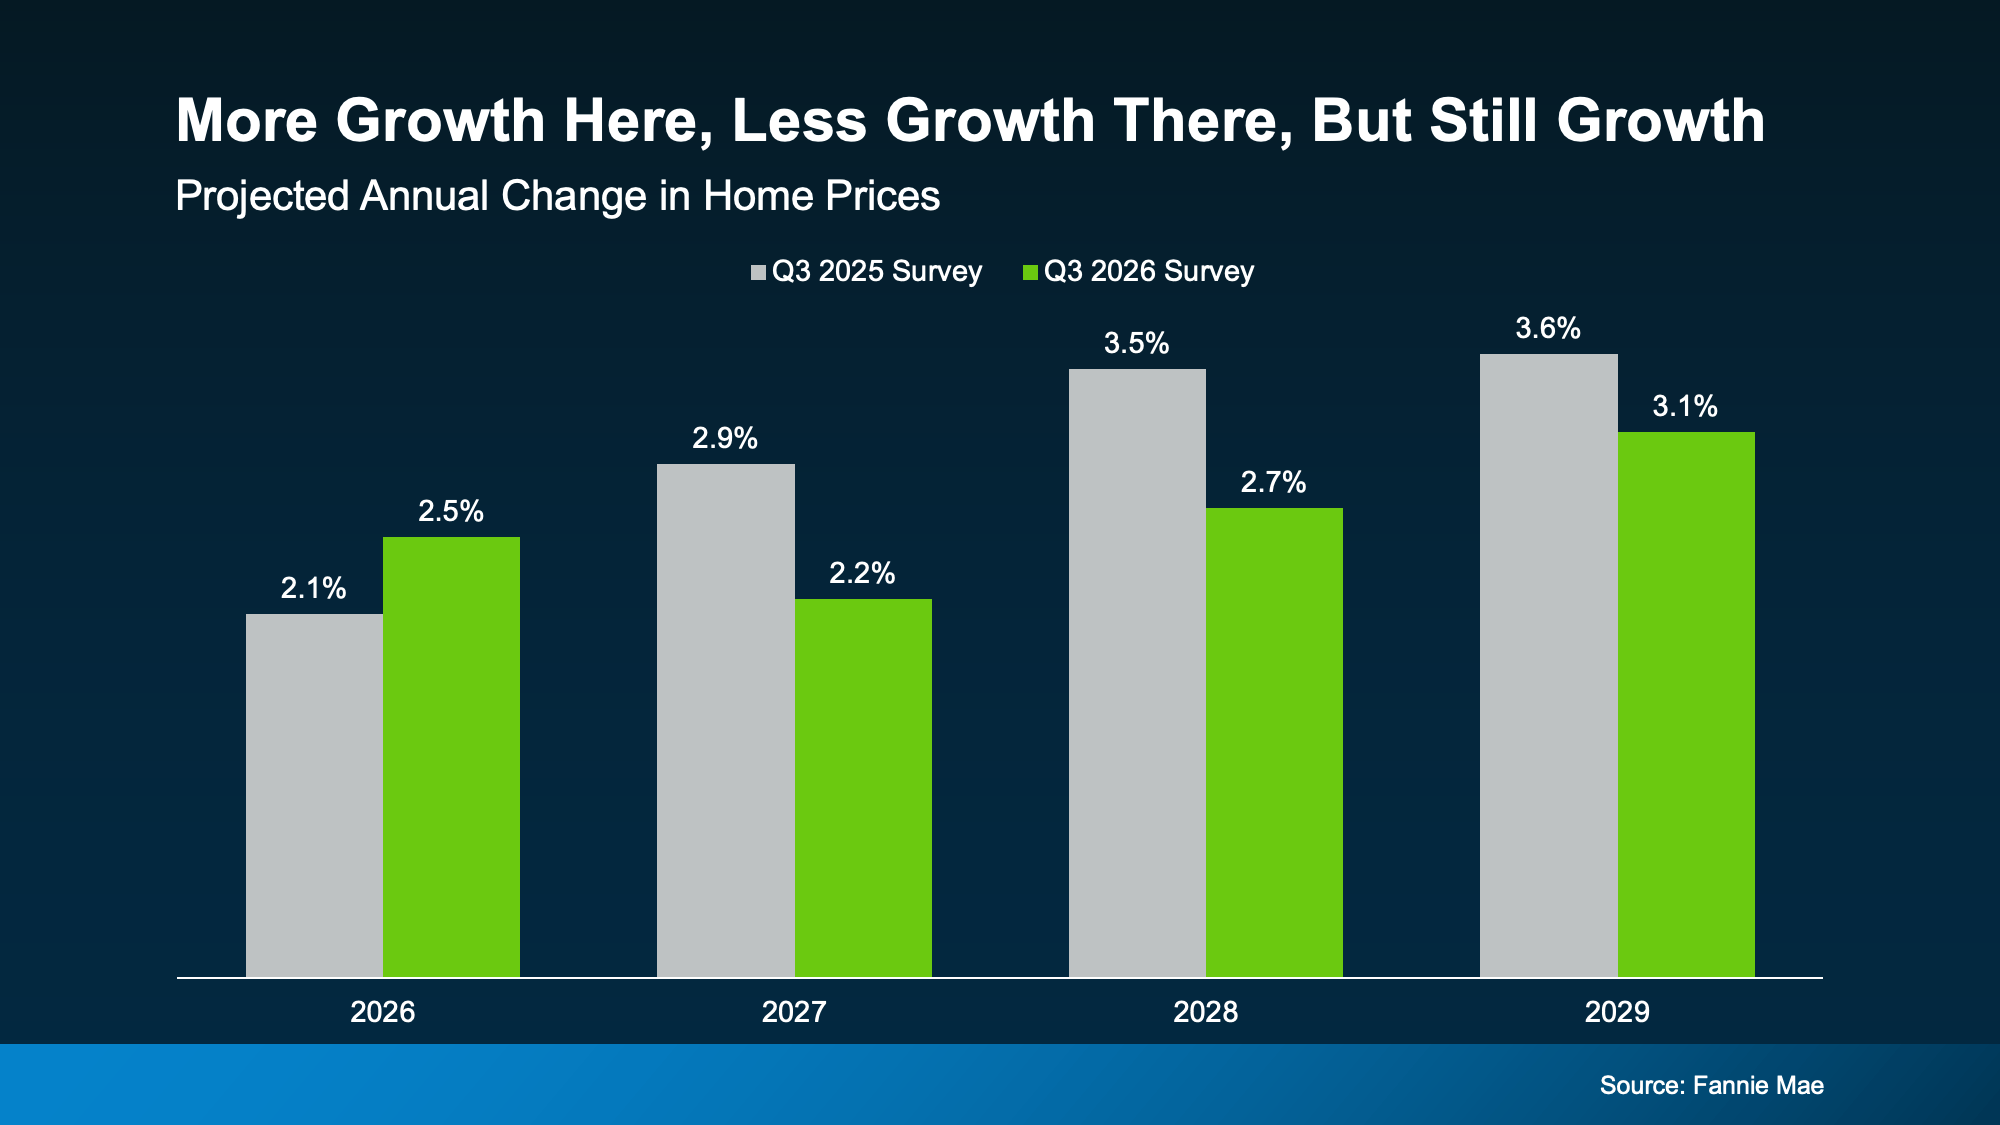
That House That’s Been Sitting Could Be Your Best Shot at a Deal

BLOGJune 22, 2026


Open up a home search and you'll see them. Listings that have been on the market for two months. Three. Some longer.

Most buyers scroll right past them, assuming something’s wrong with the house. But that instinct could be costing you, since the longer a home sits, the more motivated the seller usually gets.

Where Some Buyers Are Finding Better Deals

If affordability has been your #1 hurdle to buying, here’s a surprisingly simple strategy that could help you finally get your foot in the door. Start with the homes that have been sitting the longest. That’s often where the best deals are.

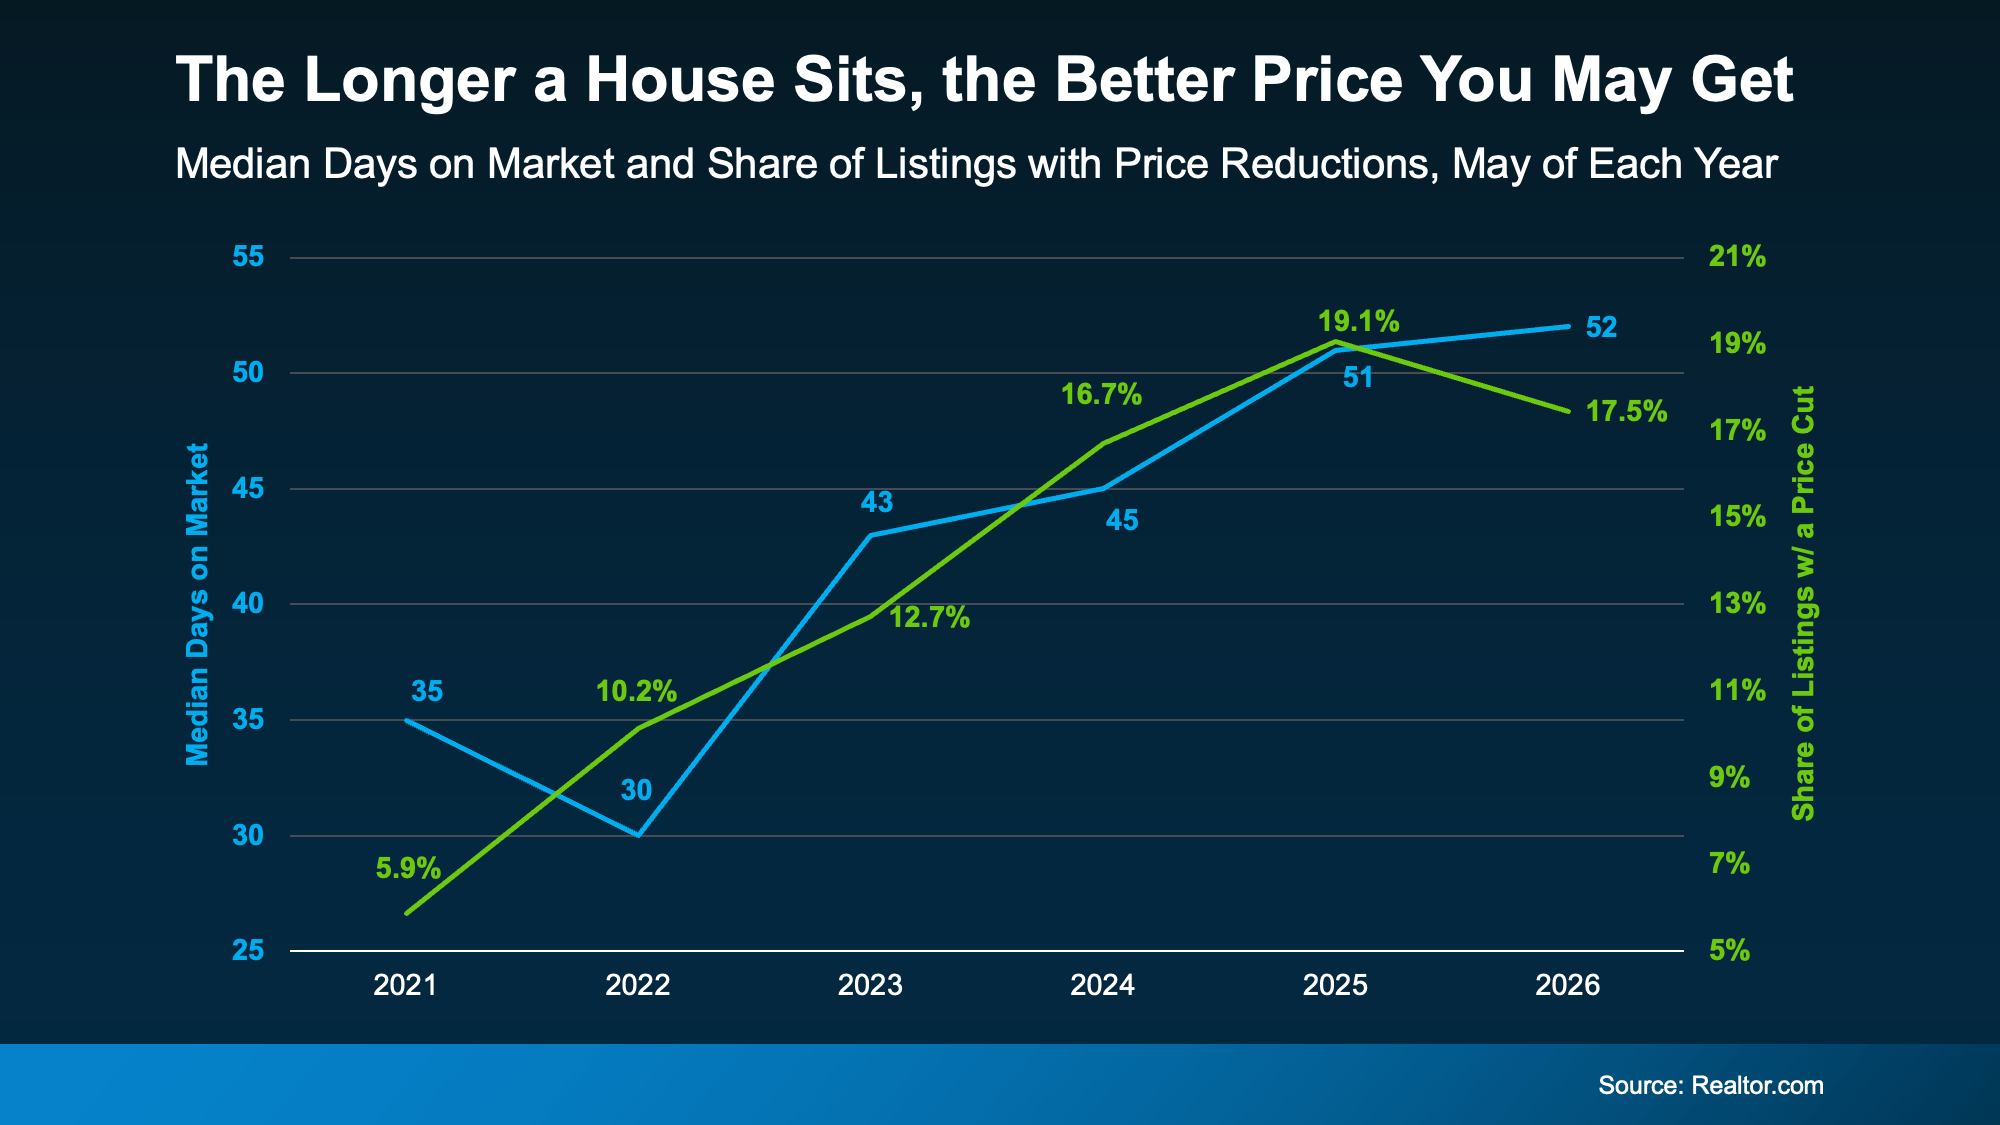
Here’s why. Data from Realtor.com shows there’s a connection between longer time on the market and lower sales prices. Basically, the longer a house sits, the more likely it is that the seller will reduce the price (see graph below):

a graph with numbers and lines

The blue line tracks how long homes stay on the market, while the green line tracks the share of homes getting a price reduction. As one climbs, so does the other.  

And if you focus on these homes that are just sitting and waiting, the opportunity for you is bigger than you may think right now.

Redfin data shows there’s $347 billion worth of stale listings on the market right now – more than ever before for this time of year. So, ask your agent to filter listings for you from oldest to newest. The home that fits your budget might already be there. Just further down the list than you thought.

Lingering Doesn’t Always Mean Something’s Wrong 

Let’s say you do that and something catches your eye. Still, you might be questioning why the home has been sitting in the first place. Just remember, sometimes it has nothing to do with the home itself.

According to Redfin, common causes are:

  • The asking price was set too high to start

  • The home didn’t show well online

  • There are a lot of homes for sale in the area, so it just got buried

So, nothing that’s necessarily a dealbreaker, or even anything that’s wrong with the home itself. If there’s a real issue, a thorough inspection will surface it. And that’s information you can use to negotiate. Not a reason to assume it’s a house worth skipping over.

How To Turn a Lingering Listing into a Win

So how do you capitalize on a lingering listing? According to USA Today, you have two main levers to pull.

The first is price. Work with your agent to study what comparable homes recently sold for, then build an offer around that. Coming in below asking price is fair game when a home has been sitting.

The second is concessions. If a seller won’t budge much on price, they may still help in other ways, like covering some closing costs, repair credits, or even a mortgage rate buydown that lowers your monthly payment.

A local agent has the context to tell which homes are the real opportunities and which are skippable.

Bottom Line

A house sitting on the market isn’t always a glaring red flag. In today’s market, it may be your best opportunity yet.

For help deciding which lingering listings are actually worth a second look, let’s connect.

The information contained, and the opinions expressed, in this article are not intended to be construed as investment advice. Keeping Current Matters, Inc. does not guarantee or warrant the accuracy or completeness of the information or opinions contained herein. Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision. Keeping Current Matters, Inc. will not be liable for any loss or damage caused by your reliance on the information or opinions contained herein.

Oct. 28, 2026

Who’s Buying Homes with Cash Right Now?

Who’s Buying Homes with Cash Right Now?

October 28, 2026·3 min read

Ryan Serhant, CEO of SERHANT, says there isn’t just 1 housing market right now. There are really 4: cash buyers, buyers who need a mortgage, homeowners with low mortgage rates, and builders.

Today, let’s zoom in on the 1st group – cash buyers.

According to the National Association of Realtors (NAR), 27% of homes sold in September were bought with all cash. That’s more than 1 in 4 buyers. And that’s a pretty big number, especially when so many people are struggling with affordability.

So where is all that cash coming from? When you hear a number like that, it's easy to picture wealthy investors buying up houses left and right. But that’s not necessarily the case. Some of those cash buyers are actually homeowners who've built up enough equity to buy their next home outright.

Here's what you should know about who's paying cash and what that really means for the market.

Who’s Paying Cash?

Cash buyers tend to fall into a few groups, according to NAR:

  • Homeowners who sold a house and are using that money to buy their next one

  • People buying a 2nd home

  • Investors

So, it’s not all those big investors social media talks about. That 1st group may include people a lot more like you. Here’s how. According to Cotality, the average homeowner with a mortgage has about $310,000 in equity.

That’s a big deal right now. Many homeowners feel stuck because they don’t want to give up the low mortgage rate they have today. But once they learn they may have enough equity to move and pay cash for their next home, today’s rates don’t matter nearly as much. Because buying in all cash means…

  • No monthly mortgage payment

  • No need to borrow at today’s mortgage rates

  • No loan approval process, so you may be able to close faster

And even if the equity won’t cover the whole purchase, putting more of it toward the next home means borrowing less. That can mean a smaller monthly payment, too.

But cash buyers like this are more common in some places than others. And how big of a segment of your local market this is, is going to depend on where you live.

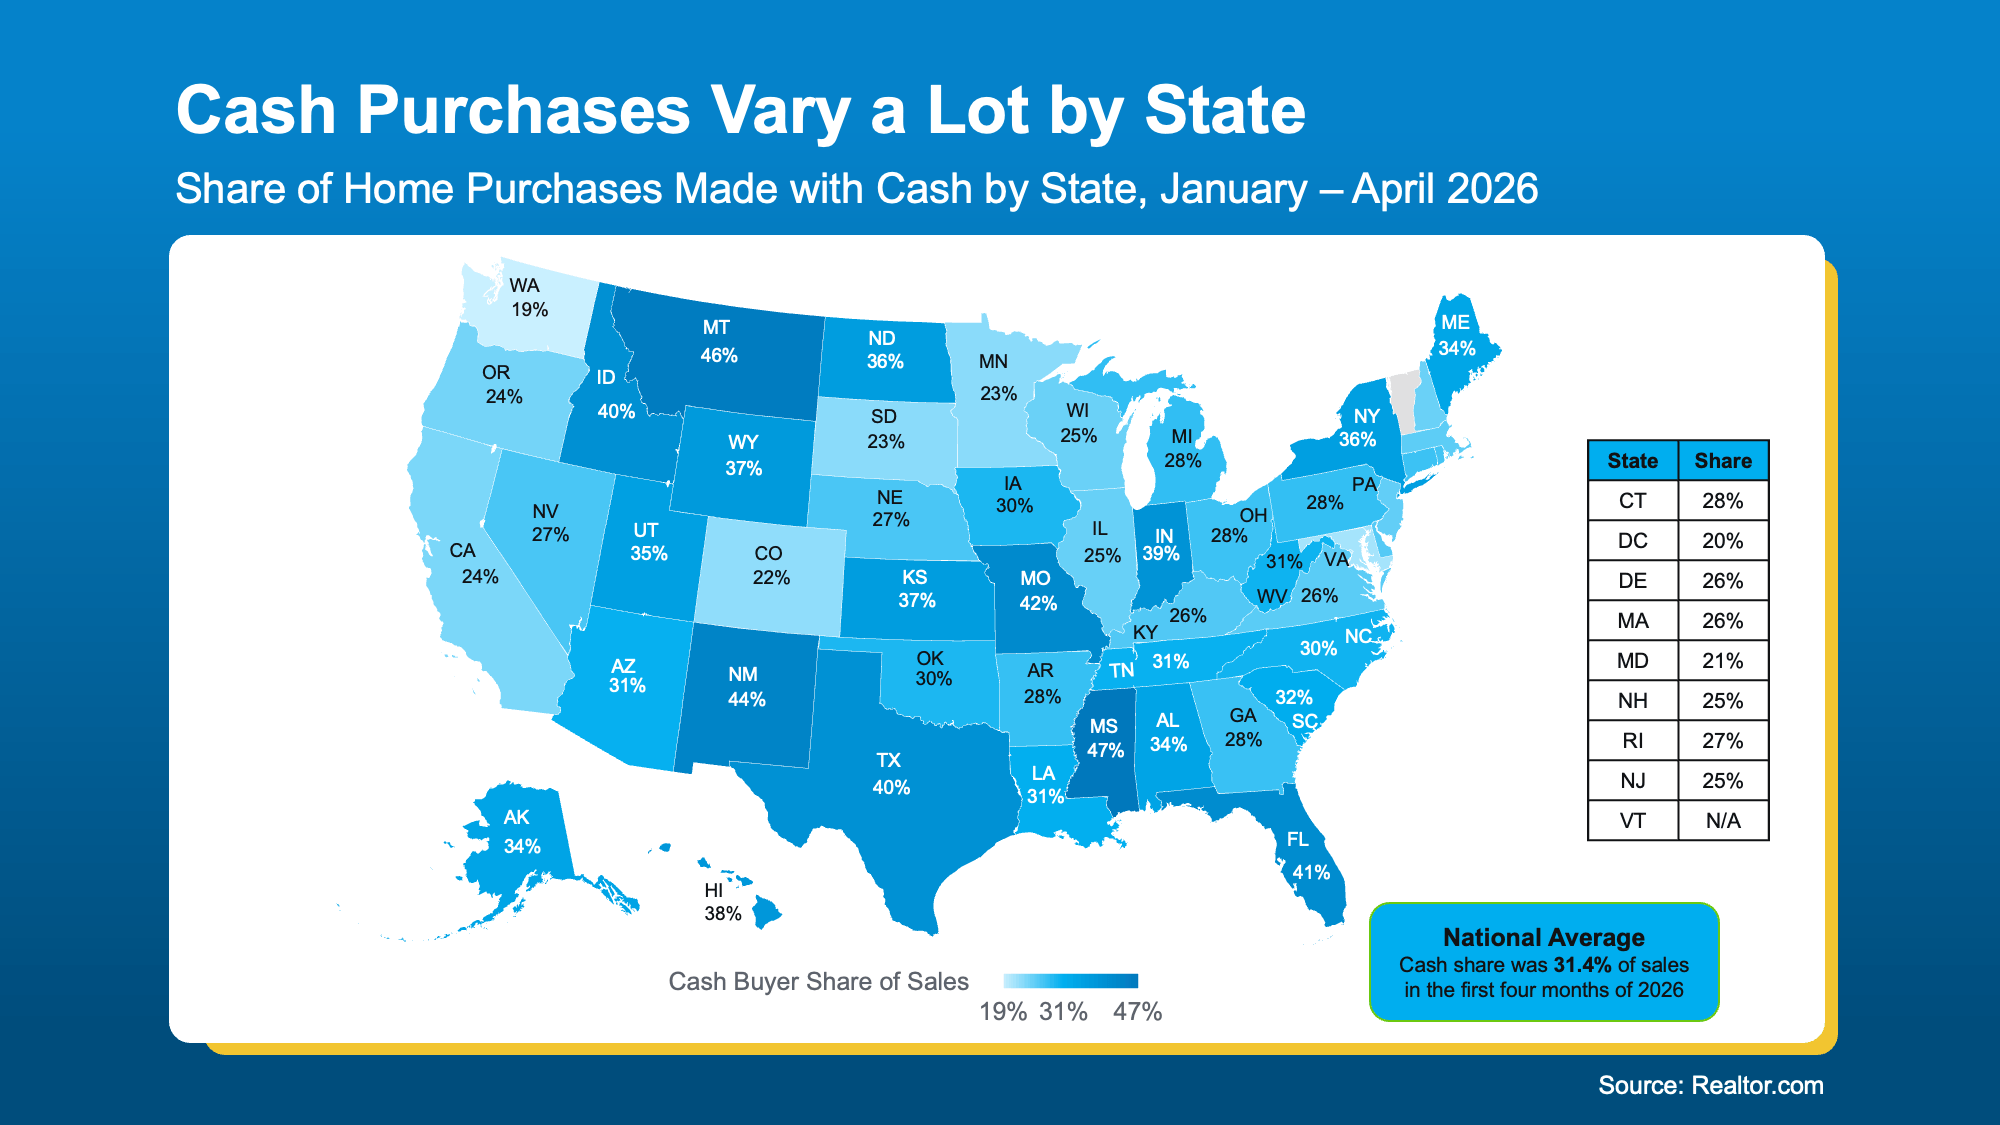
For example, Realtor.com data shows cash buyers made up almost 47% of sales in Mississippi and 46% in Montana earlier this year (see map below).

Where does your state fall?
a map of the united states

According to Realtor.com, the states with the most cash buyers reflect “a mix of affordability, wealth and buyer demographics.” Think places with lower home prices, or lots of retirees and 2nd-home buyers.

So, depending on where you live, you may see a lot more (or a lot fewer) cash buyers than the national number suggests. An agent who knows your area can tell you who’s actually buying near you.

Most Buyers Are Still Using a Mortgage

And if all of this has you thinking everyone’s paying cash, they’re not. If you’re planning to buy and need a mortgage, you’re actually in the majority.

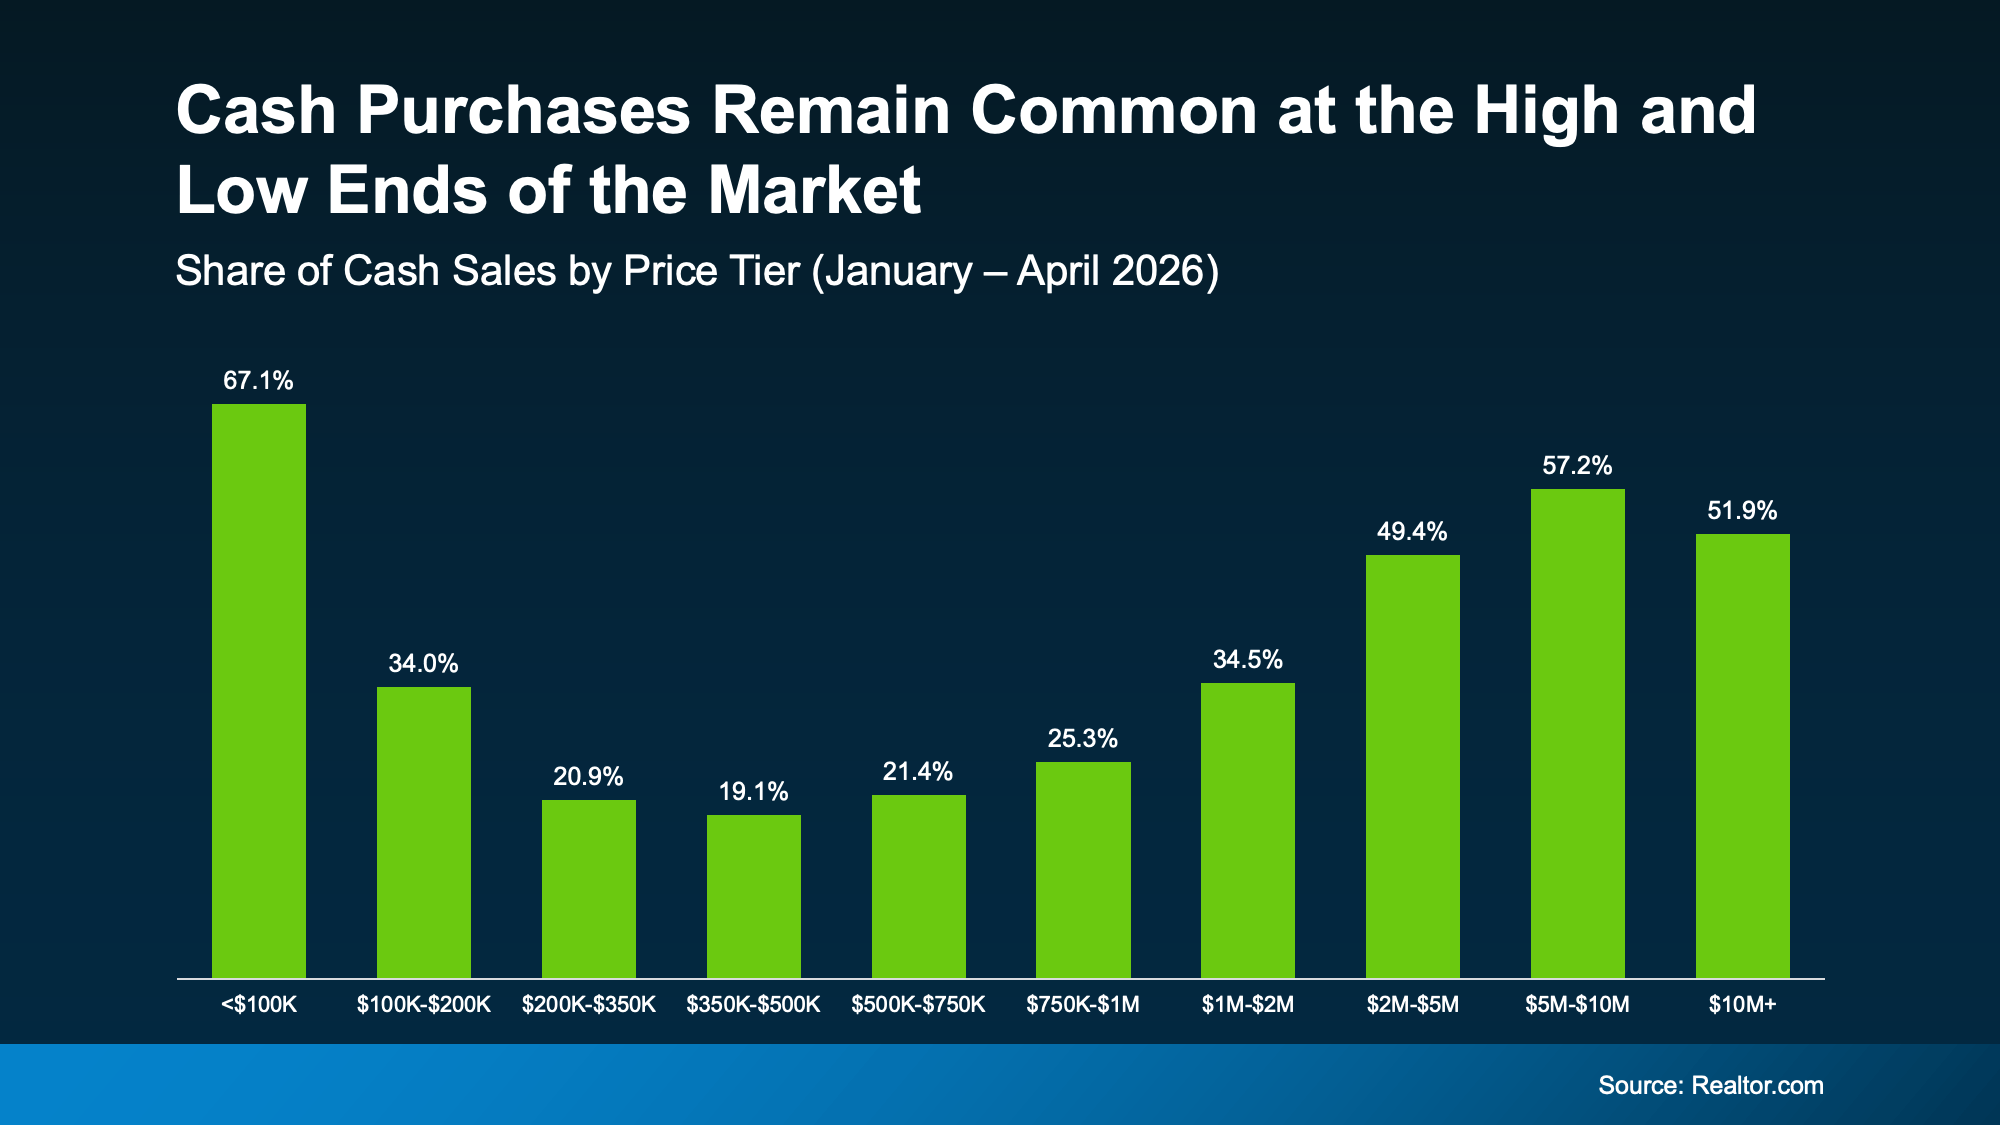
Based on NAR’s numbers, nearly 3 out of 4 home purchases still involve financing. And for homes priced between $200,000 and $750,000, only about 1 in 5 sold for cash, according to Realtor.com (see graph below):
a graph of green bars

That means most people buying in that price range are financing their purchase, too. So, there’s no need to assume you’re at a disadvantage just because you’re using a loan.

Cash Buyers and Your Move

So, what does all this mean for you? Maybe more than you think.

If you already own a house, you may have enough equity to make your next move more affordable than you realize. And if you're buying with a mortgage, remember, you're in good company. Most buyers are financing their purchases, too.

The takeaway? Don't make assumptions about what's possible based on how other people are buying homes. What really matters is your equity, your budget, and what’s happening in your local market.

Bottom Line

Cash buyers are a meaningful part of today’s market, but they aren’t the whole market.

Whether you’re hoping to put your equity to work or you’re buying with a mortgage, let’s look at how much equity you have and who’s buying in your area, so you know what your next move could look like.
The information contained, and the opinions expressed, in this article are not intended to be construed as investment advice. Keeping Current Matters, Inc. does not guarantee or warrant the accuracy or completeness of the information or opinions contained herein. Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision. Keeping Current Matters, Inc. will not be liable for any loss or damage caused by your reliance on the information or opinions contained herein.

Posted in Market Updates
Oct. 23, 2026

Confused by Home Price Headlines? Here’s Why.

Confused by Home Price Headlines? Here’s Why.

October 21, 2026·3 min read

Whether you own a house already or you’re looking to buy one, you probably care about home prices. But it’s not always easy to figure out what’s really happening right now, especially if you look at the headlines.

One says home prices are falling. The next says they’re still climbing.

So, which one’s right? It comes down to where you live.

What’s Really Going on with Asking Prices

Part of the confusion out there may be based on what’s happening to asking prices and how the media is talking about it. They’re calling attention to how asking prices are falling, but don’t give the full context or say that seasonality is at play. So here it is.

Right now, there are more homes on the market than at any other time since November 2019. And with mortgage rates rising since the spring, those homes are taking a little longer to sell. One way to help a home sell quickly in that environment is to have a lower asking price.

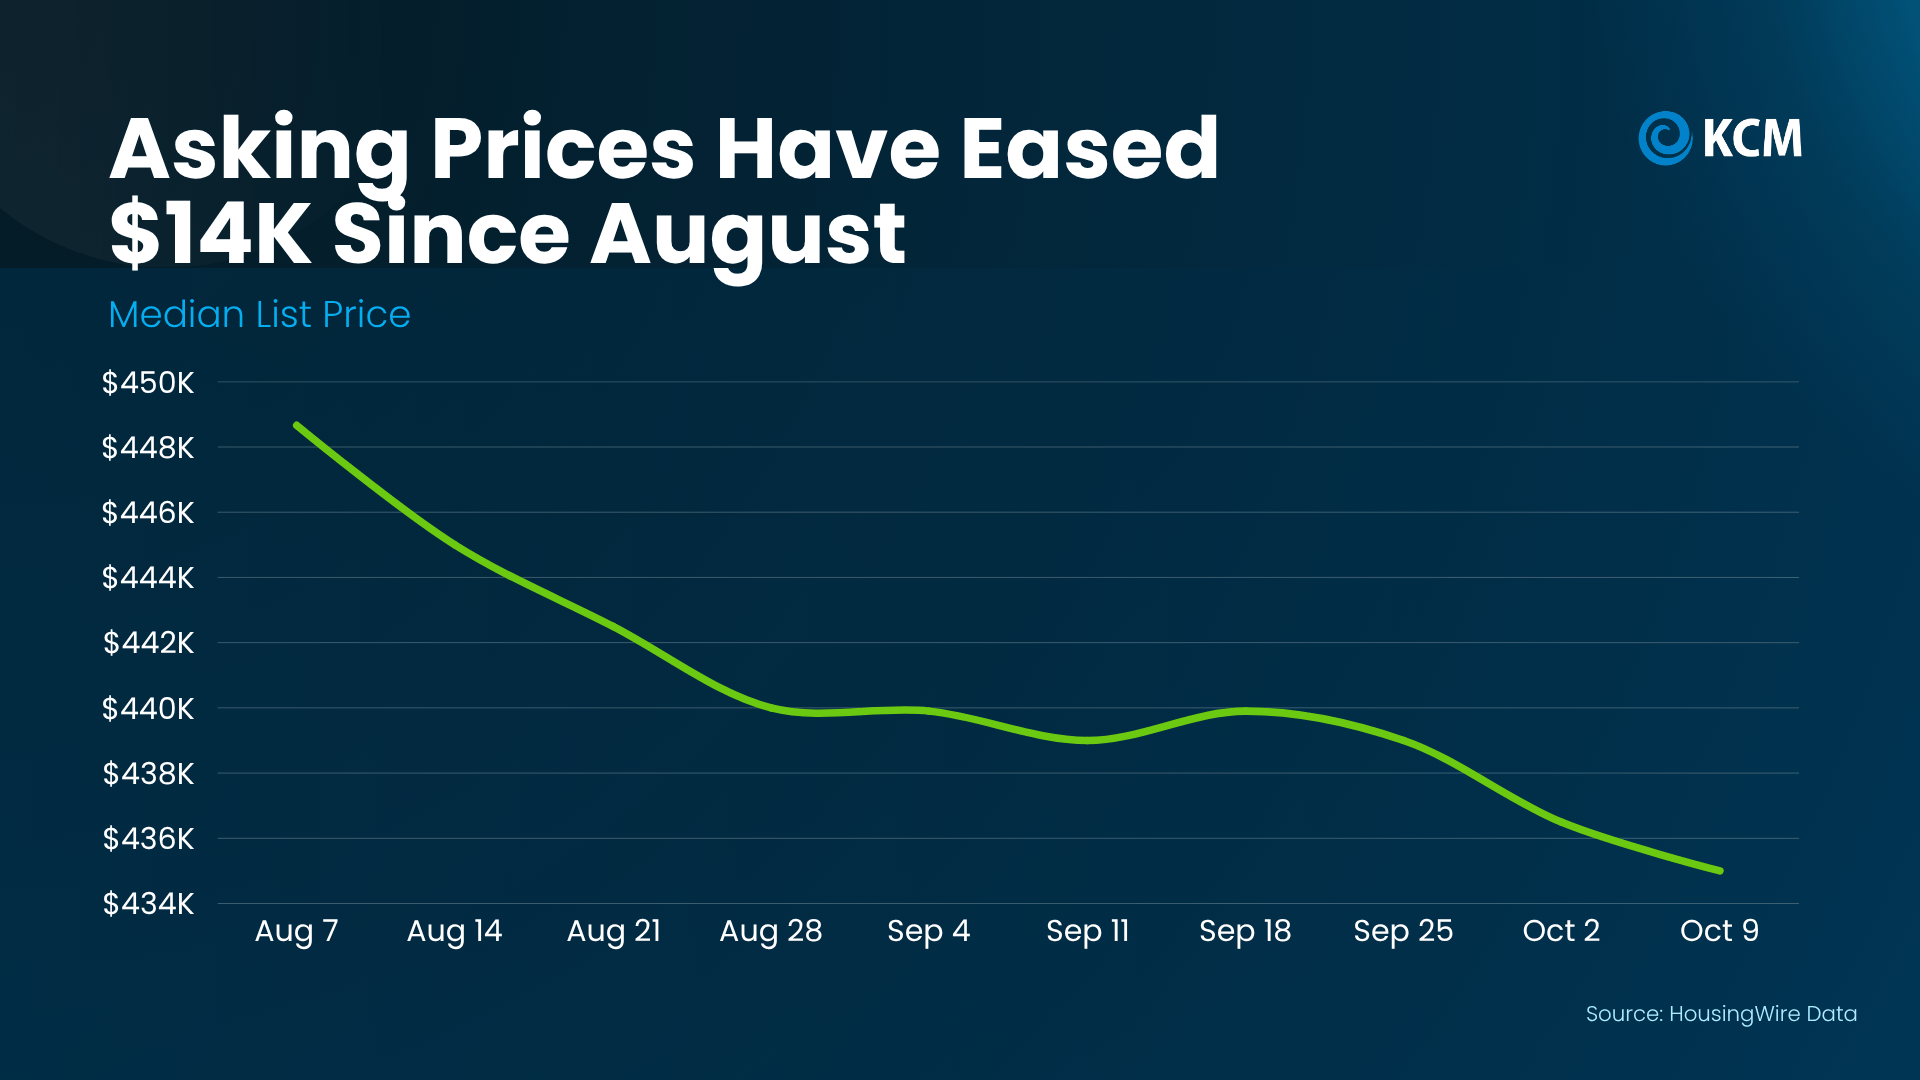
According to HousingWire Data, the median asking price is down from $449k in early August to $435k just 2 months later (see graph below):

a graph with green line

That’s a dip of about 3%, and a lot of it is normal for this time of year.

Asking prices cool off every fall once the busy summer season wraps up. With fewer buyers this time of year, sellers price a bit more competitively. Today’s rates play a role too, since sellers are pricing to match what buyers can afford right now. And that’s a good thing. Smart pricing helps homes sell.

Just keep in mind, that’s a national list price. It doesn’t show what homes near you are actually selling for. So before you react to a headline, ask a local agent what’s really happening in your area.

Where You Live Changes Everything

Realtor.com explains:

“While national headlines might suggest a buyer’s market is taking hold, the reality on the ground depends heavily on where and what you’re trying to buy. Local trends can diverge sharply from national averages, especially when you factor in price range, property type, and post-pandemic market dynamics.”

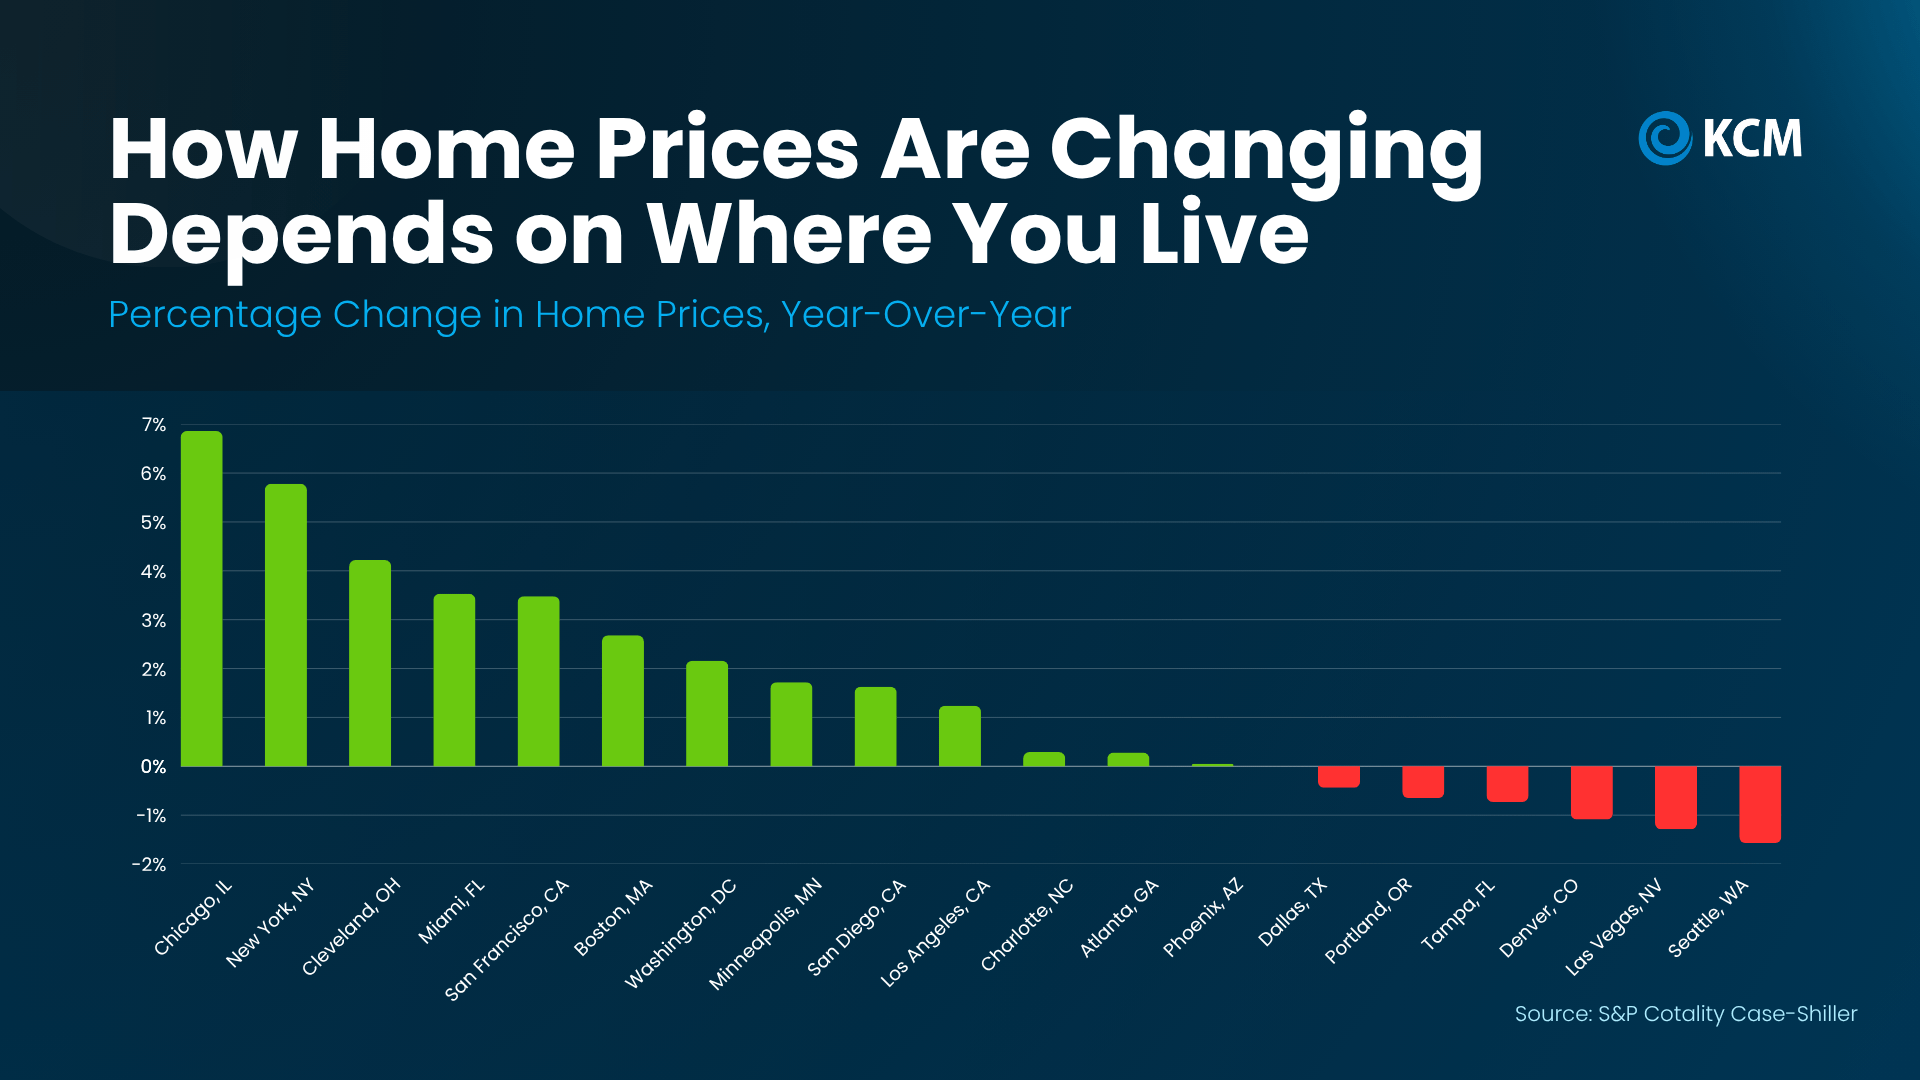
The latest numbers from S&P Cotality Case-Shiller Index show how true that is. Over the past year, sales prices in Chicago rose almost 7%. In Seattle, they dipped about 1.6%. That’s a gap of nearly 9 percentage points between two major cities (see graph below):

a graph of a price

That gap changes your game plan. Selling in New York, where prices are up almost 6%? You may not need to cut your price. Buying in Denver or Las Vegas? You may have more room to negotiate.

Why You Don’t Need To Worry About a Crash

Just in case you’re seeing those slight declines in some markets and worried it means a bigger crash is coming, here’s what you need to remember. Even in the major metros where prices are down, the declines are 2% or less. That’s a long way from a crash like 2008. And if you look back at the graph above, there are more cities in the green than in the red.

And over time, home values have a strong track record. The Federal Housing Finance Agency (FHFA) says national prices have grown year-over-year every quarter since 2012. Go back further, and a $100k home bought in 1991 would be worth about $436k today, even with the 2008 crash factored in (see graph below):

a graph with a line going up

So, this short-term dip probably won’t stick around. The small declines we’re seeing now are in markets that overheated during the pandemic. As a whole, the market is headed back to normal – and normal means prices should rise over time.

Bottom Line

National headlines can’t tell you what your home is worth or how much room you have to negotiate. Local data can. If you’re thinking about buying or selling, let’s look at how prices are moving in your area, so you can set your price or make your offer with confidence.

The information contained, and the opinions expressed, in this article are not intended to be construed as investment advice. Keeping Current Matters, Inc. does not guarantee or warrant the accuracy or completeness of the information or opinions contained herein. Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision. Keeping Current Matters, Inc. will not be liable for any loss or damage caused by your reliance on the information or opinions contained herein.

Posted in Market Updates
Oct. 12, 2026

Why Most People Are Still Glad They Bought a Home

Why Most People Are Still Glad They Bought a Home

October 12, 2026·3 min read

With everything going on, it’s understandable if you’re wondering if you’d regret buying right now. 

Everyday expenses cost more. Mortgage rates are higher than you’d like. And when the economy feels uncertain, taking on a mortgage can feel like a much bigger leap. But here’s some perspective that may help…

Most people who already made that leap would do it again.

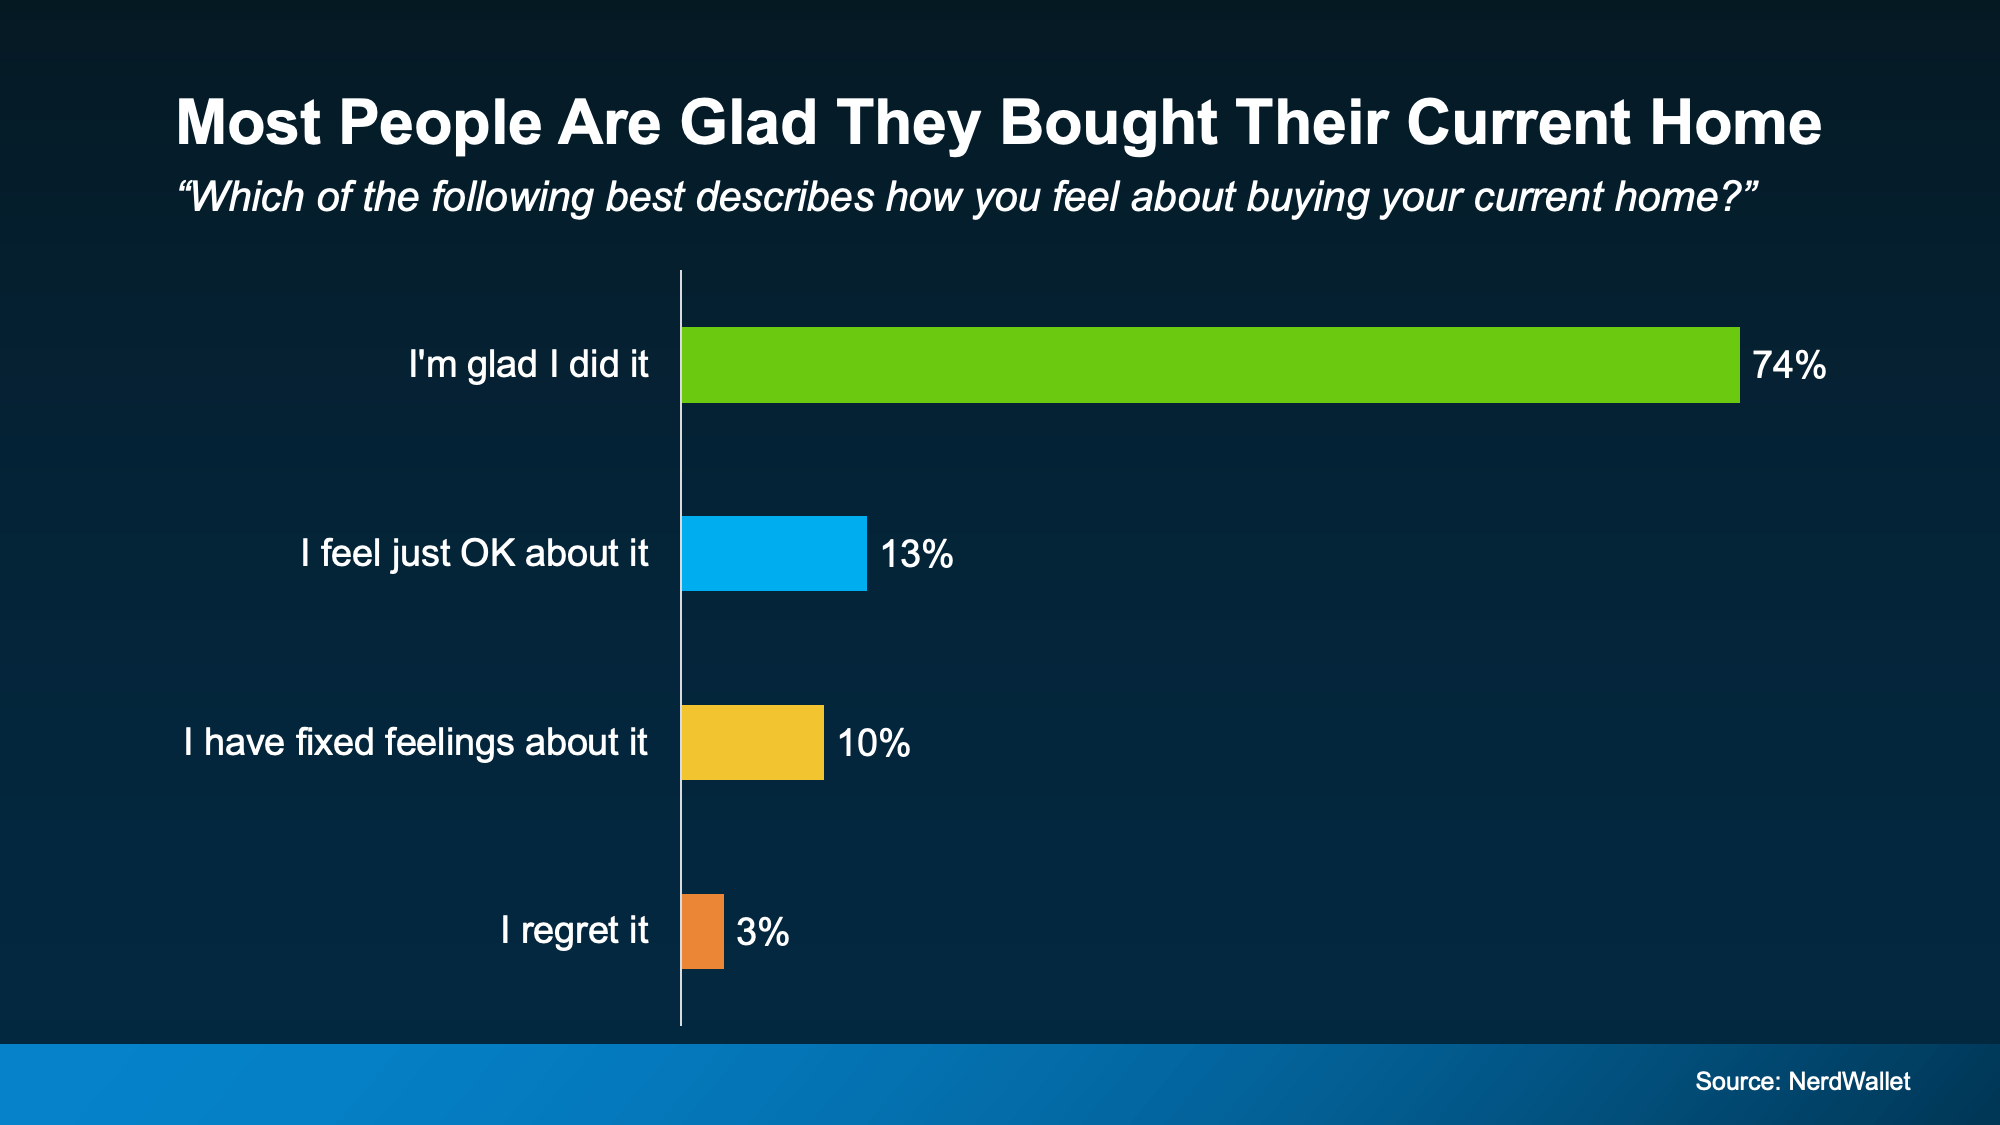
According to a recent survey from NerdWallet, the vast majority of recent buyers (74%) were glad they bought their current home. Only a very small 3% of people regret it:

a graph with text on it

And here’s a big reason why so many people feel it was worth it, even now.

Homeownership Is a Long-Term Play

When you’re deciding whether to buy, it’s easy to focus on what’s happening right now. What’s today’s mortgage rate? Are prices going up or down? Those things matter. But don’t get so caught up in buying in the perfect moment that you miss the bigger picture.

A home isn’t typically something you buy for just a year or two. It’s a longer-term play. And when you zoom out, it all starts to fall into perspective – especially if you look at home prices and equity.

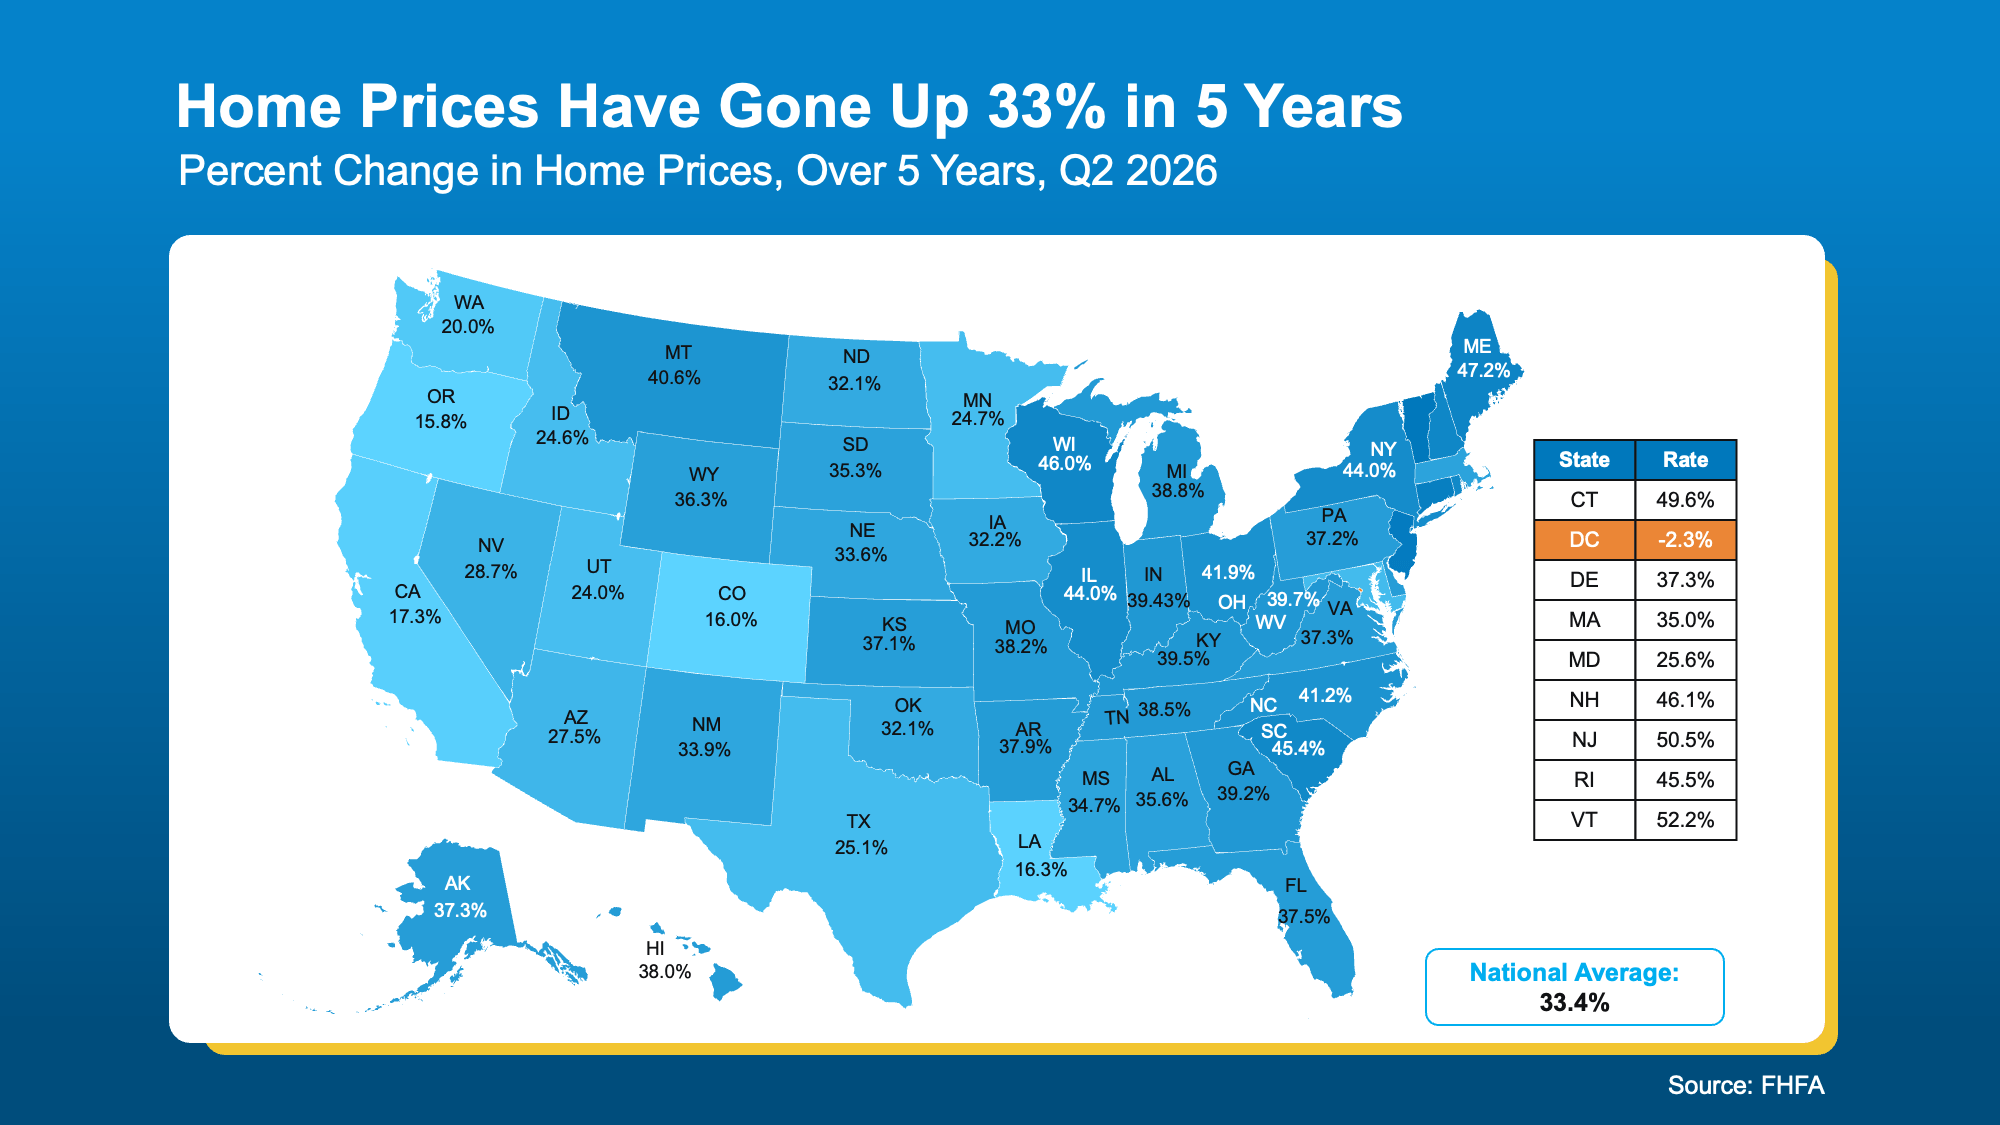
According to data from the Federal Housing Finance Agency (FHFA), home prices nationally have risen 33.4% over just the past five years (see map below):

a map of the united states

And that appreciation has helped current homeowners build some serious wealth. Research from Bankrate shows homeowners gained an average of nearly $150,000 in wealth over the past five years as equity steadily rose across 90% of major metro areas.

That’s one of the biggest benefits of homeownership. As you pay down your mortgage and your home appreciates over time, your ownership stake – your equity – can grow.

Now, Zoom Out Even Further

The five-year numbers are impressive. But the numbers get even more dramatic when you look at decades instead of individual market cycles.

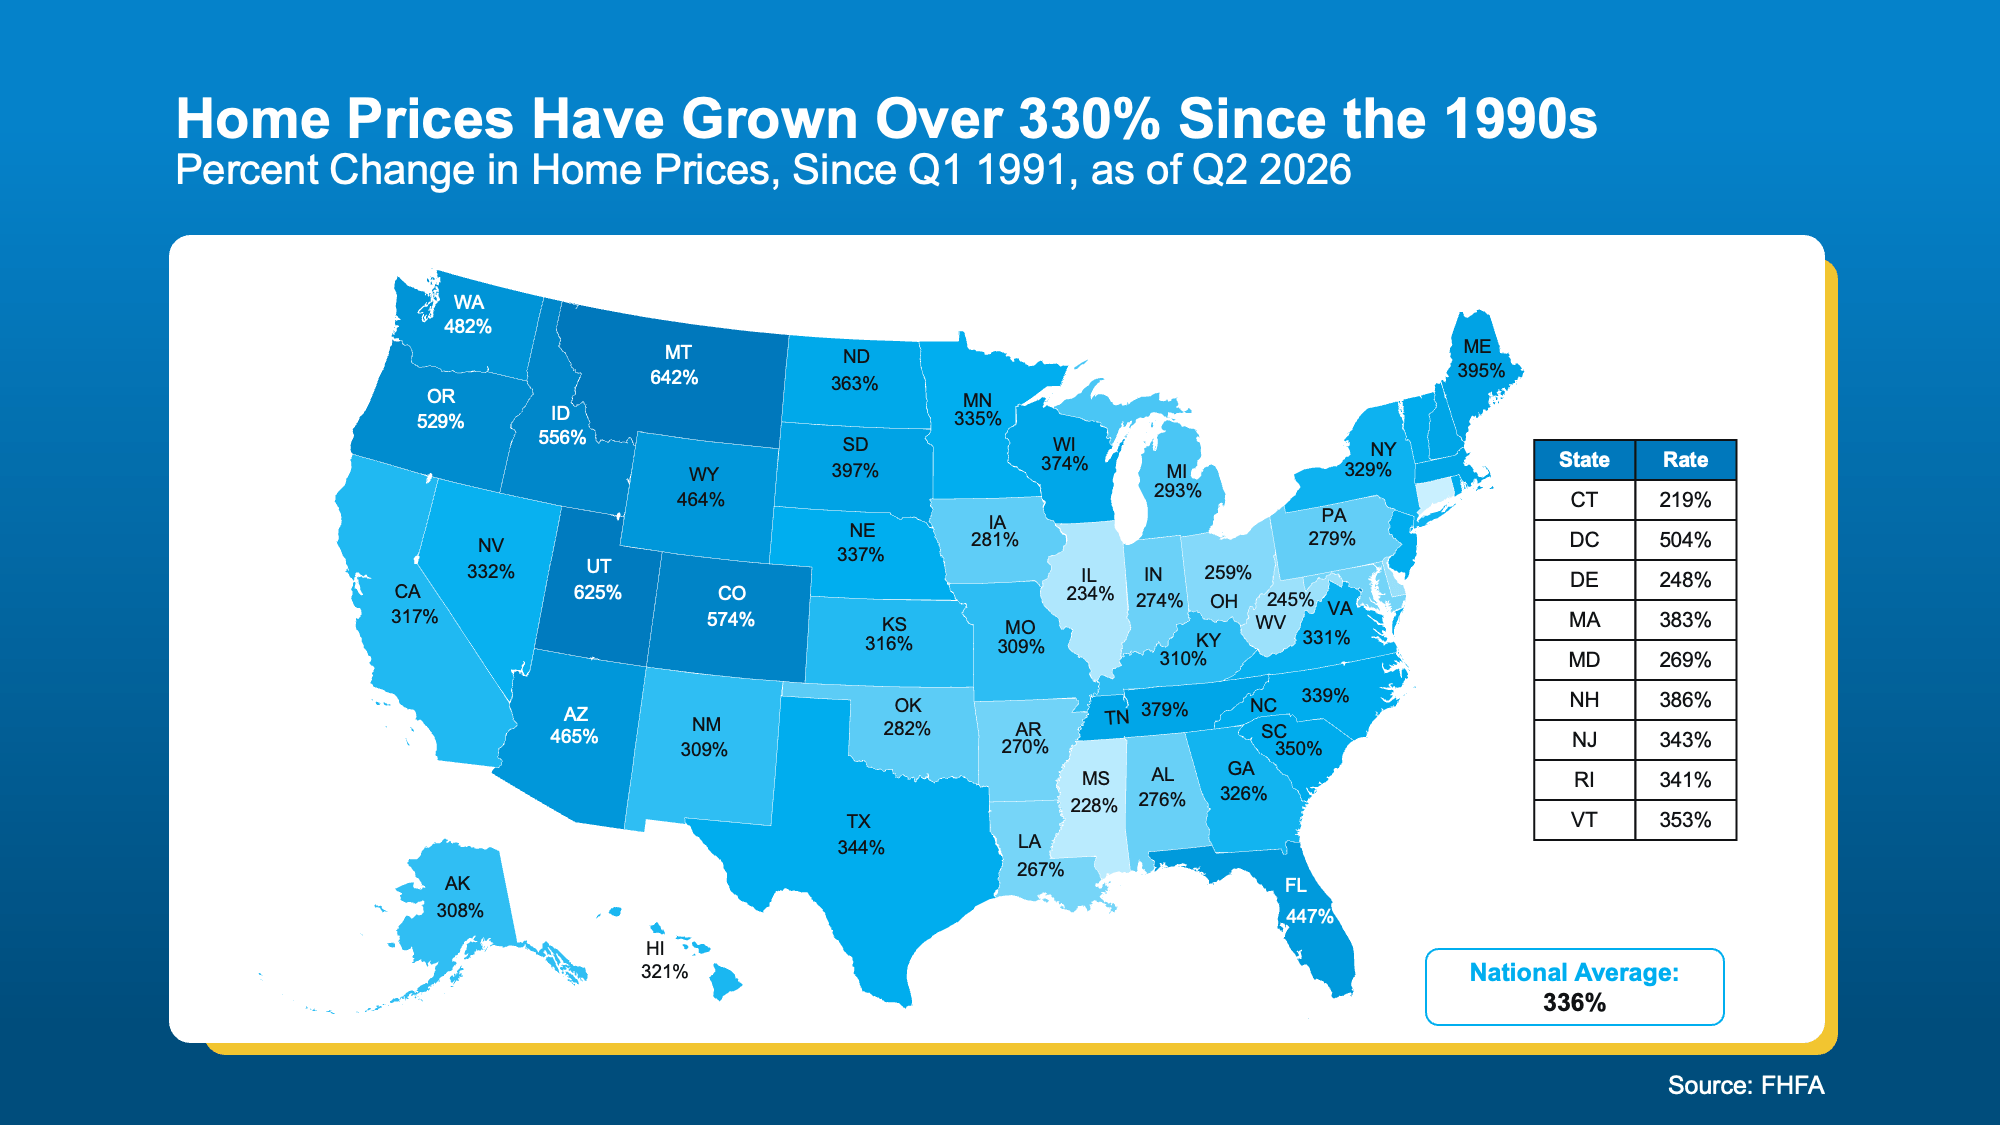
FHFA data shows home prices nationally have risen 336% since 1991. Sit with that for a second. Three hundred percent (see map below):

a map of the united states with numbers and a number of states 

That doesn't mean prices go up every single year. And it doesn't mean buying is automatically the right decision for everyone today. You should only buy when the numbers (and the payment) work for you.

What it does show is why trying to perfectly time the market can make you miss the bigger picture. 

Over time, homeowners gain a lot of equity. And that equity can eventually become a powerful financial resource. As Freddie Mac explains: 

“Your home's equity is part of your total wealth as a homeowner. If you decide to sell your home, the equity you have built over time will come back to you in the sale. . .

If it's time to upsize or downsize, you can use that cash for the down payment on your next home.”

Basically, if you can afford to do it, buying a home now could set you up for future moves.

And just in case you’re someone who’s worried about what happens if prices do fall, after you buy, remember: you’re not buying for one year.

Prices can dip. They have before. But historically, they’ve risen far more over the long run. And the longer you own your home, the more time you have to ride out those ups and downs and keep building equity.

Bottom Line

Don’t let today’s uncertainty make you lose sight of what homeownership can do over time. Most homeowners say they’d make the same choice again. And decades of home-price growth help explain why.

If you’re wondering whether buying makes sense for you right now, let’s look at the numbers together – and what owning a home could mean for you in the years ahead.

The information contained, and the opinions expressed, in this article are not intended to be construed as investment advice. Keeping Current Matters, Inc. does not guarantee or warrant the accuracy or completeness of the information or opinions contained herein. Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision. Keeping Current Matters, Inc. will not be liable for any loss or damage caused by your reliance on the information or opinions contained herein.

Posted in Market Updates
Oct. 5, 2026

Two Moves That Can Get You Into Your First Home Sooner

Two Moves That Can Get You Into Your First Home Sooner

October 5, 2026·3 min read

For a lot of first-time buyers, owning a home can feel perpetually a few years out of reach. Saving for a down payment takes time, and each year you spend renting can make owning feel further off.

But buying your first home doesn’t have to happen to feel like a far away goal. Two choices you control can bring your first home years closer, even with affordability as tight as it is right now.

How Long Buying Really Takes

First, one quick definition. "Breaking even" is the point where owning has cost you about the same as renting would have over the same period. And after that point, owning starts to cost less than renting. Kara Ng, Senior Economist at Zillow, puts it this way:

"Buyers should think about not just when they can afford to buy, but how long they'd need to stay before owning makes more financial sense than renting."

So how long does reaching that point usually take? And what are the shortcuts? Let’s do the math.

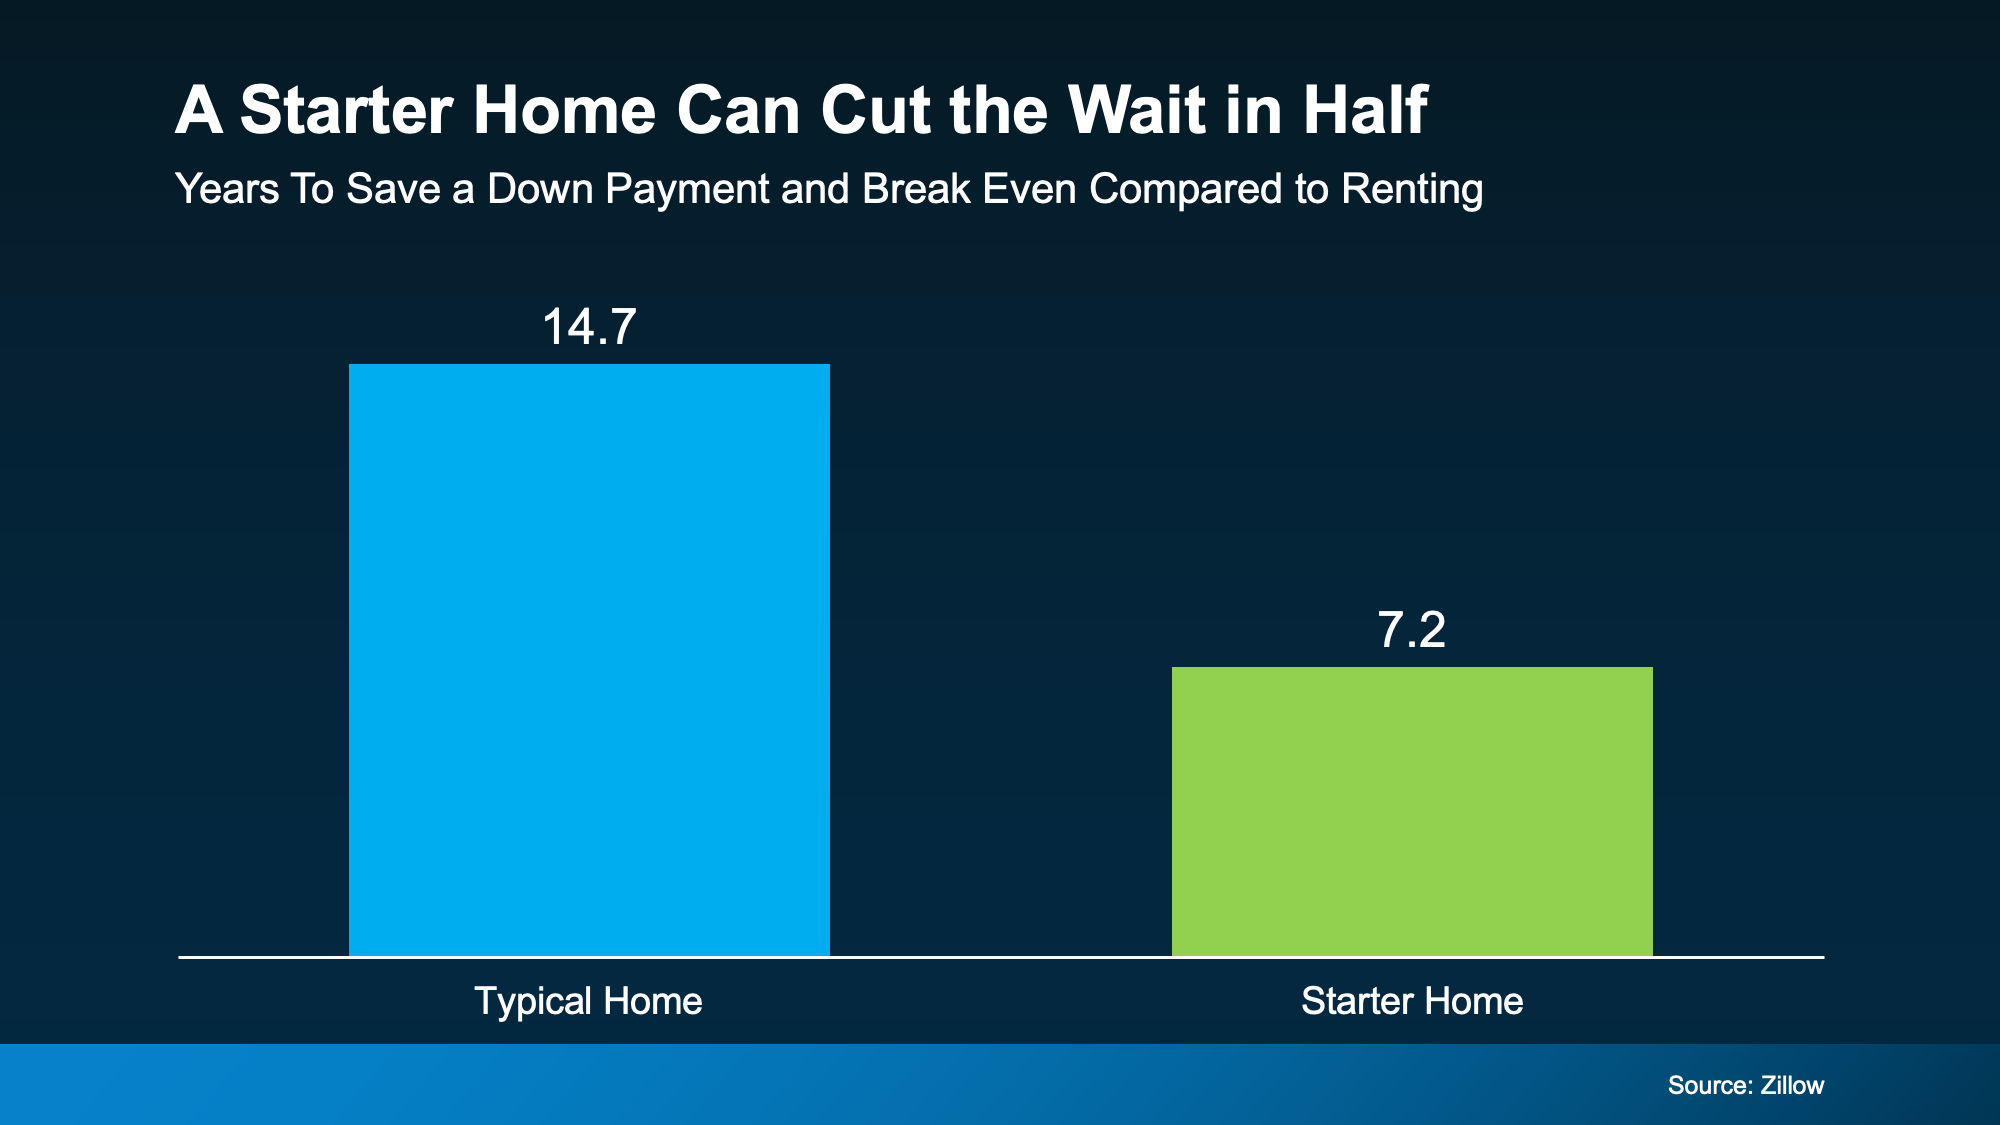
According to Zillow, it usually takes about 8.5 years to save for a 20% down payment, then roughly 6.2 more years before owning costs the same as renting. Together, that's just under 15 years. But that math relies on two assumptions: that you're buying a mid-priced home, and that you're putting 20% down. 

Change either one and your timeline gets shorter. Change both and it can shrink fast. It also varies widely by market, since local prices and rents are different depending on where you live. 

A Starter Home Can Get You There Twice as Fast

A starter home usually means a home in the lower third of local prices. They’re often condos, townhomes, or single-family homes a little smaller or older than others in the area. 

Choosing one over a mid-priced home can cut your wait down by a lot. And while that might sound obvious, you may not realize just how much it shortens your timeline. Because if you’re buying a more affordable home, you don’t have to save up as much or as long.

Zillow found that nationwide, a starter home takes half the time – about 7.2 years – to save for and come out ahead on, compared with renting (see graph below):

a graph of a number of squares

That works out to about 4.6 years to save and 2.6 years to break even. It won't erase every affordability challenge, but it can take years off the wait. And if you’ve already been saving for a while, it could get you closer to making it a reality.

You Usually Don't Need To Put 20% Down

You, like many first-time homebuyers, might assume you need a 20% down payment to even consider buying. But a lot of the time, you don’t. 

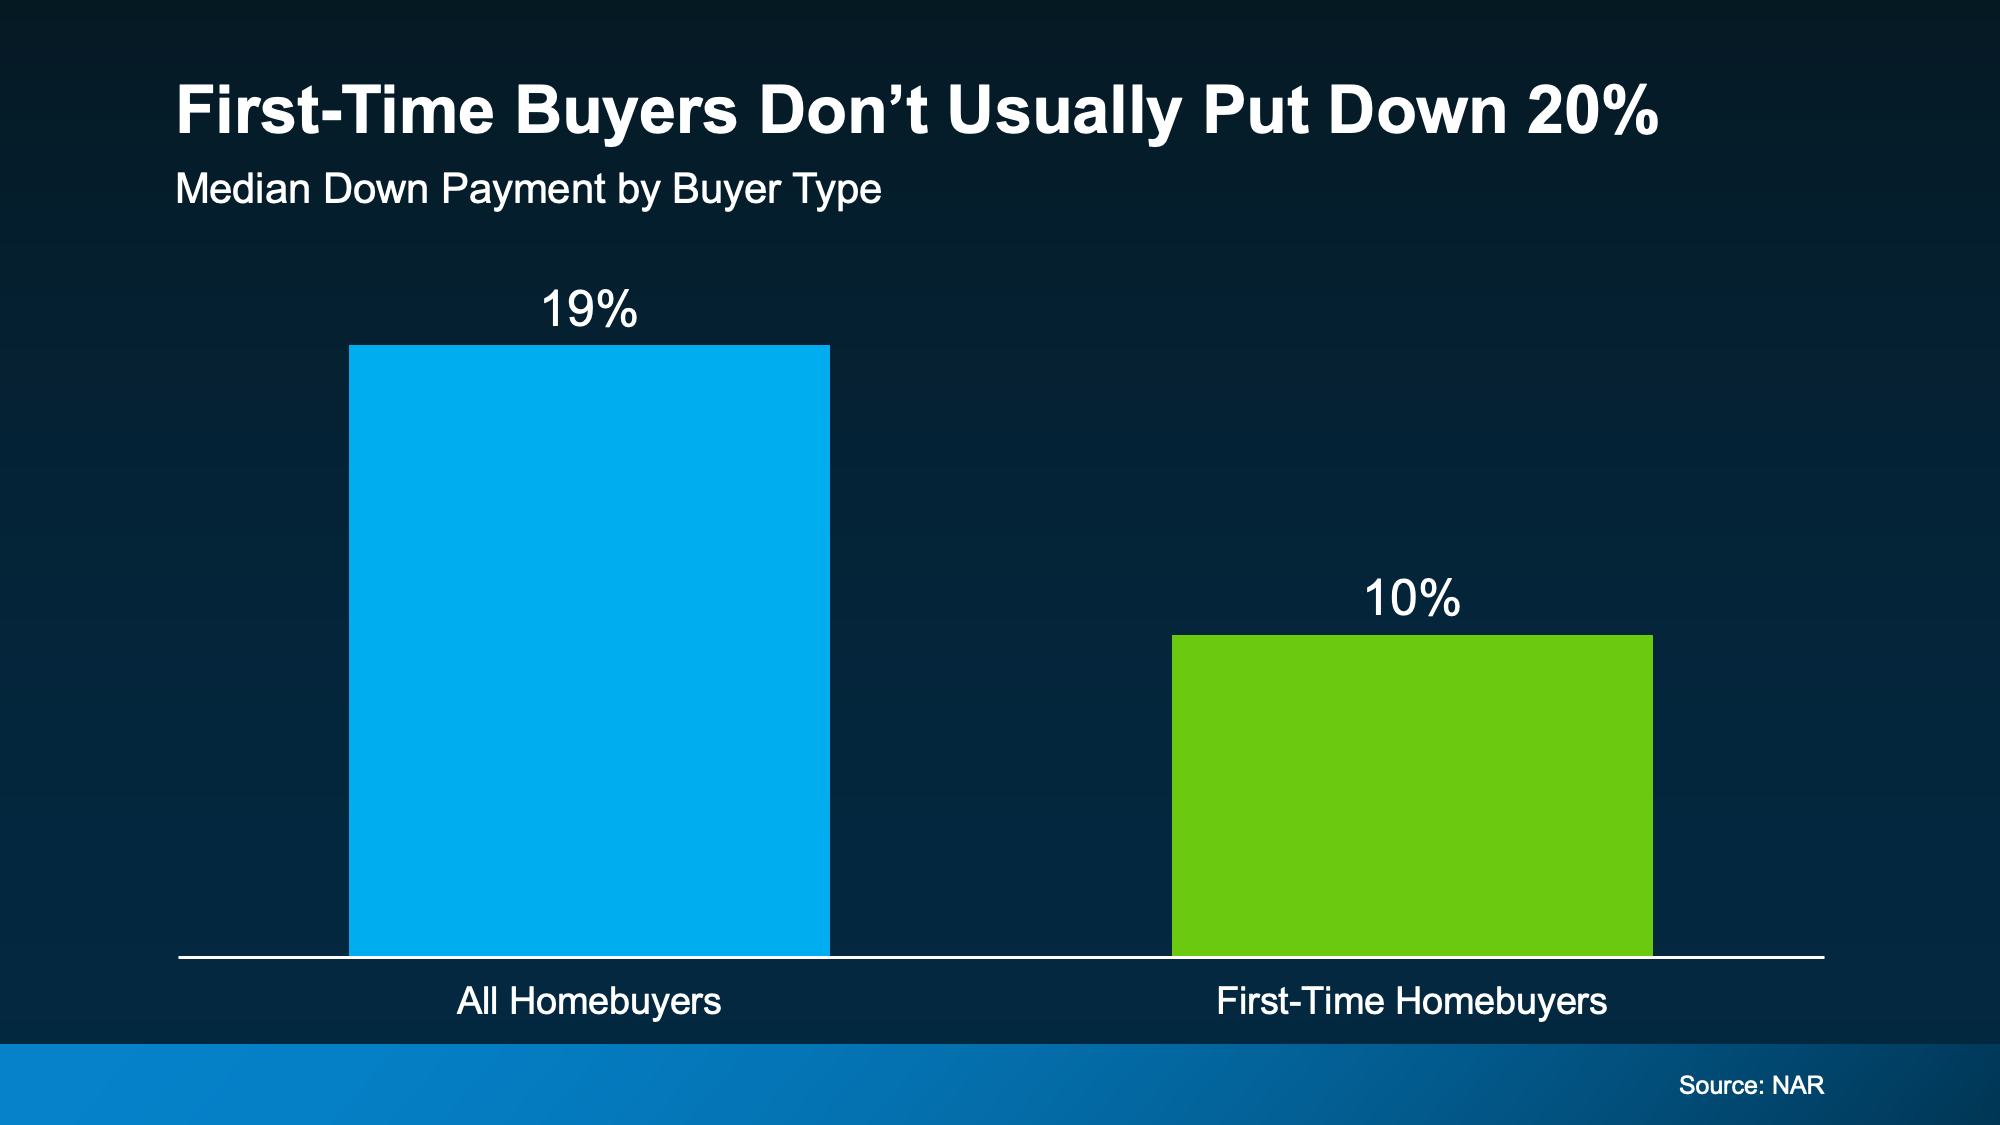
Most first-time buyers don't put down anywhere near that. The National Association of Realtors shows the median down payment for first-time buyers is 10% (see graph below):

a graph of a sales report

And the minimums go lower still. Some buyers put down as little as 3% on a conventional loan or 3.5% on an FHA loan, and eligible veterans or buyers in certain rural areas can put down nothing at all.

There's help with the upfront costs of buying, too. Down Payment Resource counts 2,746 assistance programs nationwide, and some are even stackable:

"Some homebuyers can layer multiple sources of assistance to reduce their upfront costs. Layering means combining more than one eligible source of funding as part of your home purchase."

Put those together – a lower price point, a smaller down payment, and help covering it – and the years you thought you needed start to come down.

Bottom Line

Your first home may not be as far off as it feels. When the numbers make sense for you, buying a starter home and putting down less than 20% can get you there years sooner. 

Want to see which starter homes in our area could fit your budget? Let's connect.

The information contained, and the opinions expressed, in this article are not intended to be construed as investment advice. Keeping Current Matters, Inc. does not guarantee or warrant the accuracy or completeness of the information or opinions contained herein. Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision. Keeping Current Matters, Inc. will not be liable for any loss or damage caused by your reliance on the information or opinions contained herein.

Posted in Market Updates
Sept. 30, 2026

Hoping for (or Dreading) a Housing Crash? The Experts Just Weighed In.

Half the buyers out there are scared home prices are about to crash. The other half are hoping they will.

A recent survey from Clever found 58% of Gen Z buyers are actually rooting for a crash, just so homeownership feels within reach.

So, what do the forecasts actually say?

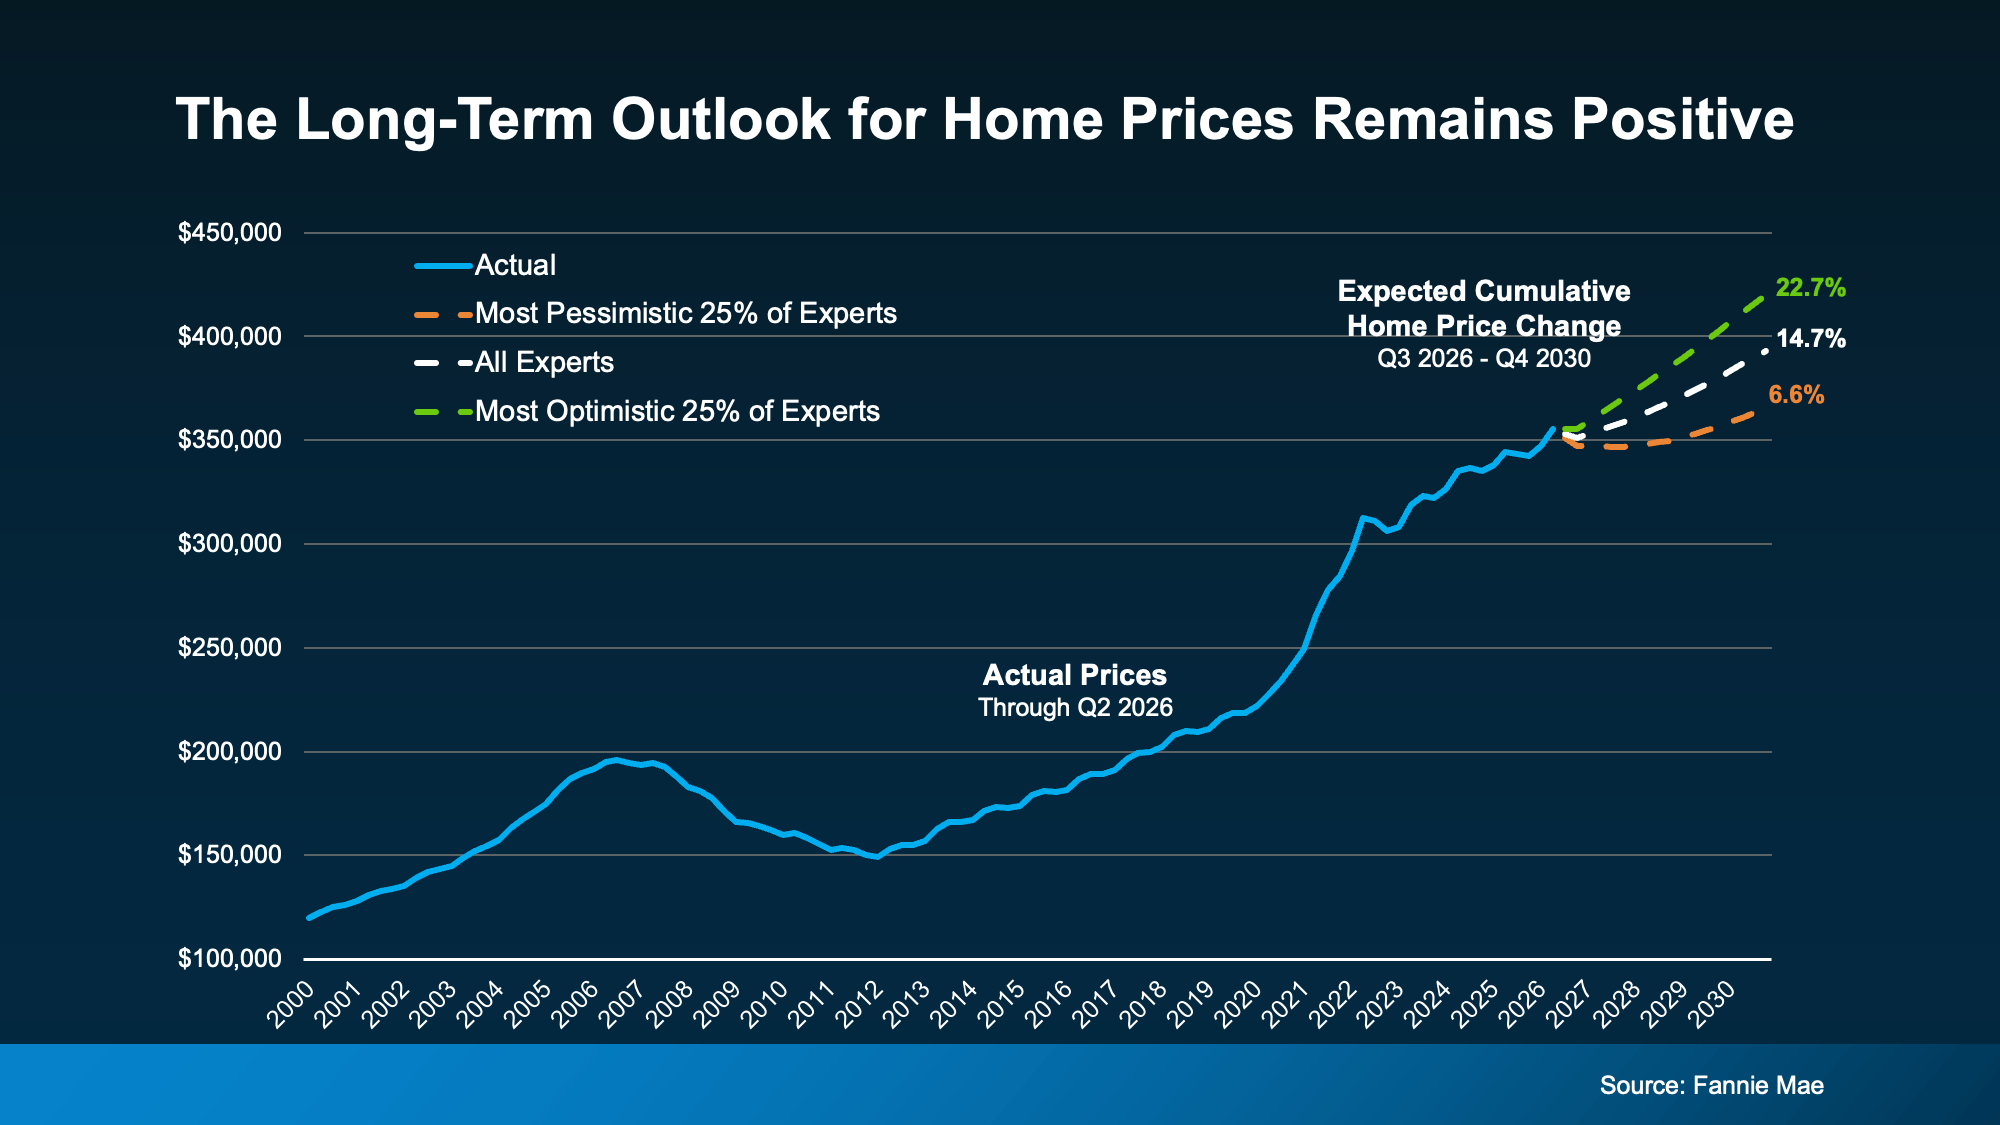
Every quarter, Fannie Mae surveys more than 100 housing experts on where prices are headed. The newest results are in. And spoiler alert: they’re not calling for a crash – not even the pessimists.

What the Newest Numbers Actually Say

The panel's latest forecast has prices climbing every single year through at least 2030.

The panel's average forecast is that prices will rise by 14.7% in the next 5 years. And here’s where it gets really interesting. If you split these experts into optimists and pessimists, even the pessimists still expect prices to increase about 6.6% by the end of 2030 (see graph below):

a graph showing the price of a home

The takeaway? If you've been waiting for prices to fall, you may be waiting a while.

One thing to keep in mind though – these are national numbers. Prices in your area could run a little hotter or a little cooler than this, so it helps to know what’s happening locally, too. But the big picture is prices aren’t crashing. Historically prices usually rise.

How This Quarter Compares to the Past

Here’s something you probably don’t realize. This survey runs 4 times every year, so you can track the panel's mood over time.

A year ago, the panel expected home prices to grow 2.1% this year. Now they’re forecasting 2.5%. That means the near-term outlook actually got more optimistic. But that’s only part of the story. The years after that shifted, too (see graph below):

a graph of growth in a graph

Zoom out to 2027 through 2029 and the mood has cooled a bit. Each of those years is now expected to see a little less growth than the panel thought a year ago. That’s likely a reflection of where we are right now with everything that’s impacting the housing market.

But again, the overall takeaway here is every bar shows an increase in prices – the size of that increase has just moderated due to some of the factors at play.

A slower climb isn’t a bad thing, though. It’s a sign the market is settling into a more normal pace after a few wild years.

A little more growth here, a little less growth there. What hasn't budged once is the idea that home prices will keep growing.

What It Means for Your Next Move

Now, percentages are great, but you probably care more about the actual dollars and cents of your move, so let’s graph that out, too.

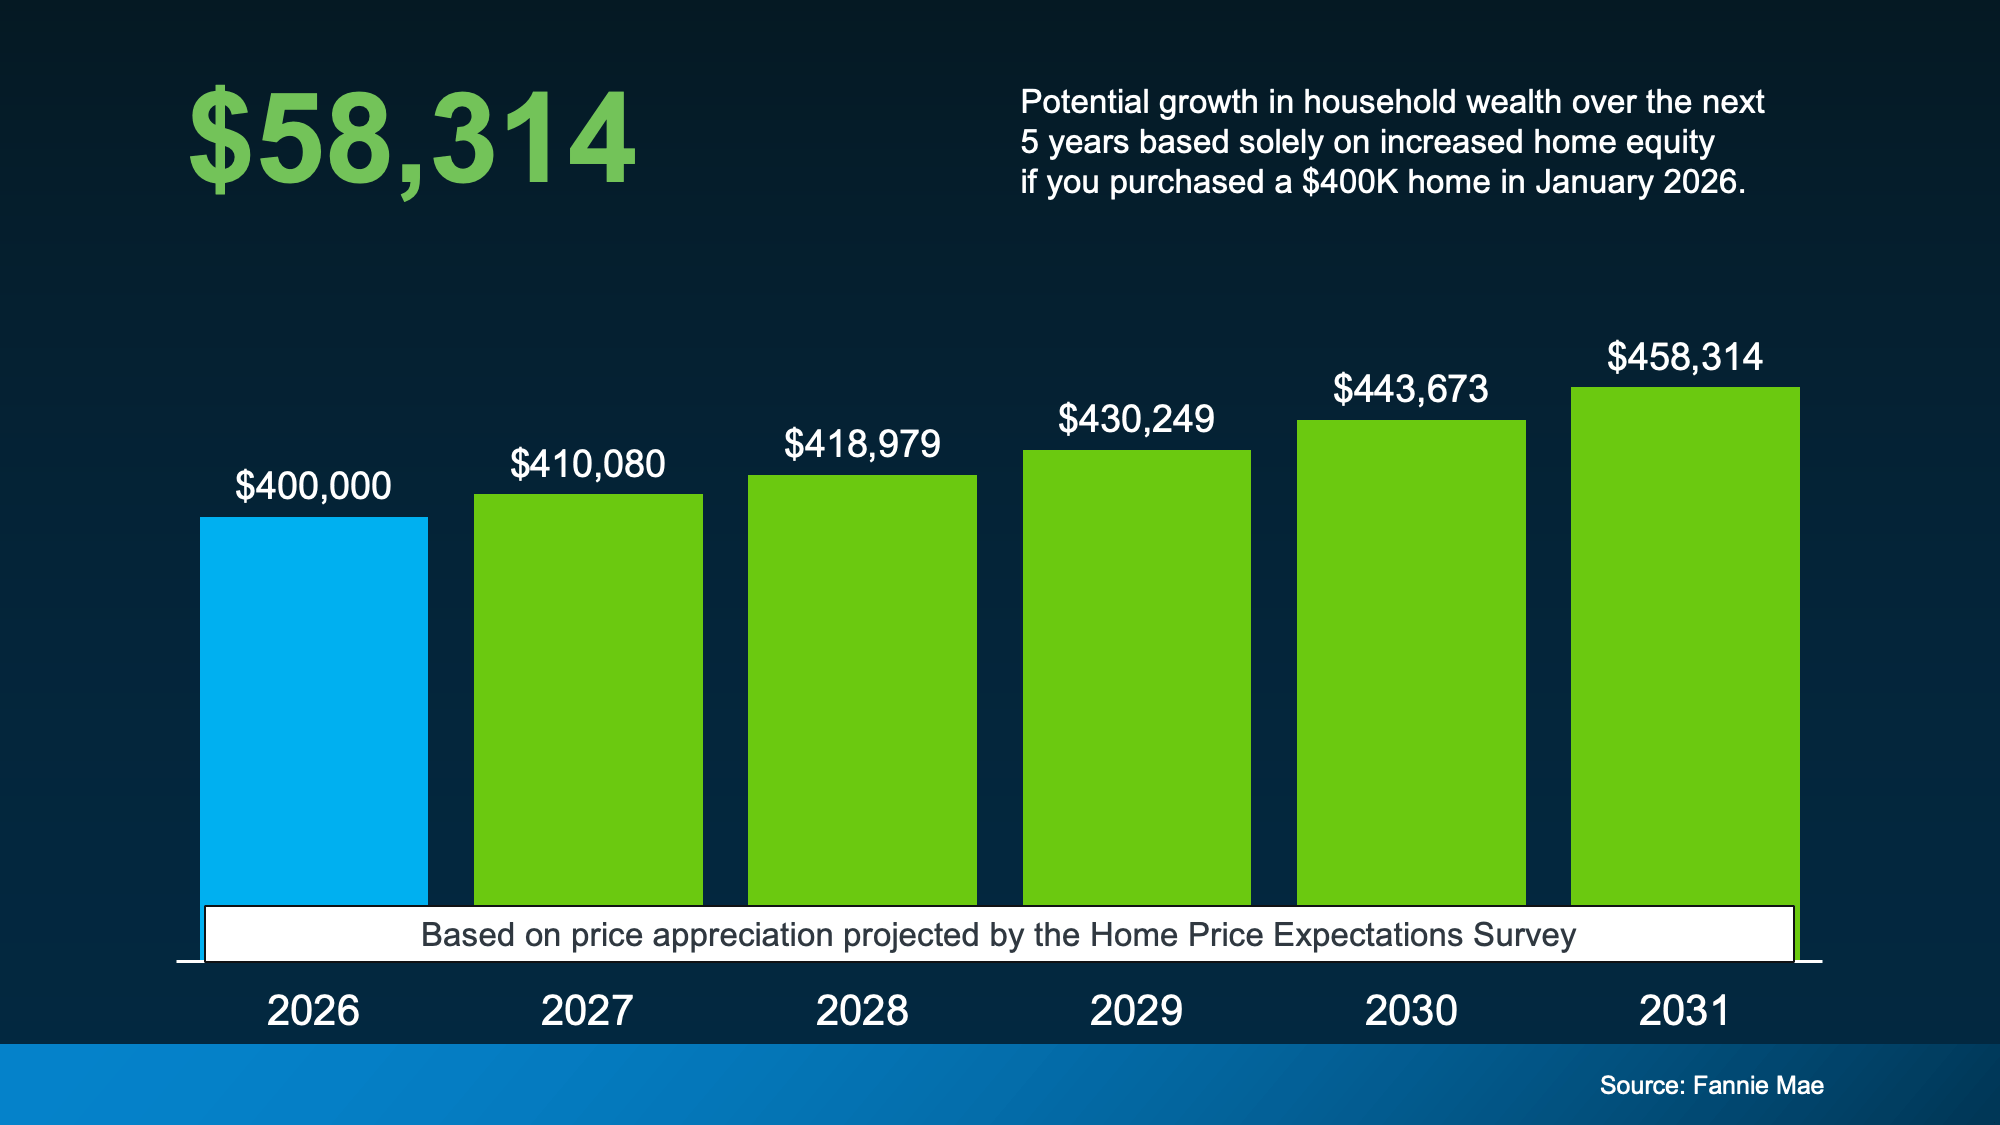
Run the numbers on a $400,000 home bought in January, and the panel's latest forecast puts you up about $58,000 in equity in 5 years just from price growth (see graph below):

a graph of growth in a number of green squares

That’s real wealth you could be building while others sit on the sidelines, waiting for a crash the experts don’t see coming. And with prices expected to keep rising, waiting could mean paying more for the same home later.

Bottom Line

Whether you're bracing for a crash or hoping for one, the verdict is the same – prices are still expected to rise, not fall. Let's talk about what that means for your market and your plans.

The information contained, and the opinions expressed, in this article are not intended to be construed as investment advice. Keeping Current Matters, Inc. does not guarantee or warrant the accuracy or completeness of the information or opinions contained herein. Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision. Keeping Current Matters, Inc. will not be liable for any loss or damage caused by your reliance on the information or opinions contained herein.

Posted in Market Updates
Sept. 29, 2026

Most Homes for Sale Since 2019 Graph

September 29, 2026·

The number of homes for sale just reached its highest point since 2019. And that gives you the most choice you’ve had in 7 years. With affordability still so tight, having that many options opens up your odds of finding a home you love that still works for your budget. Want to see what’s on the market in our area? DM me the price point you’re looking at to get started. #HouseHunting #HomebuyingTips #KeepingCurrentMatters
Posted in Market Updates
Sept. 24, 2026

Why So Many Sellers Are Cutting Their Price Right Now

Why So Many Sellers Are Cutting Their Price Right Now

September 24, 2026·3 min read

Price cuts are turning up everywhere right now, and they read very differently depending on which side of the deal you’re on.

Sellers tend to worry a cut means walking away with less than they hoped. Sometimes that’s true, but more often it just means the market moved faster than the listing did.

Buyers, for their part, often assume a cut means something’s wrong with the house. Most of the time, that’s not it.

This is what's actually driving all those price cuts, and why it matters no matter which side of the deal you're on.

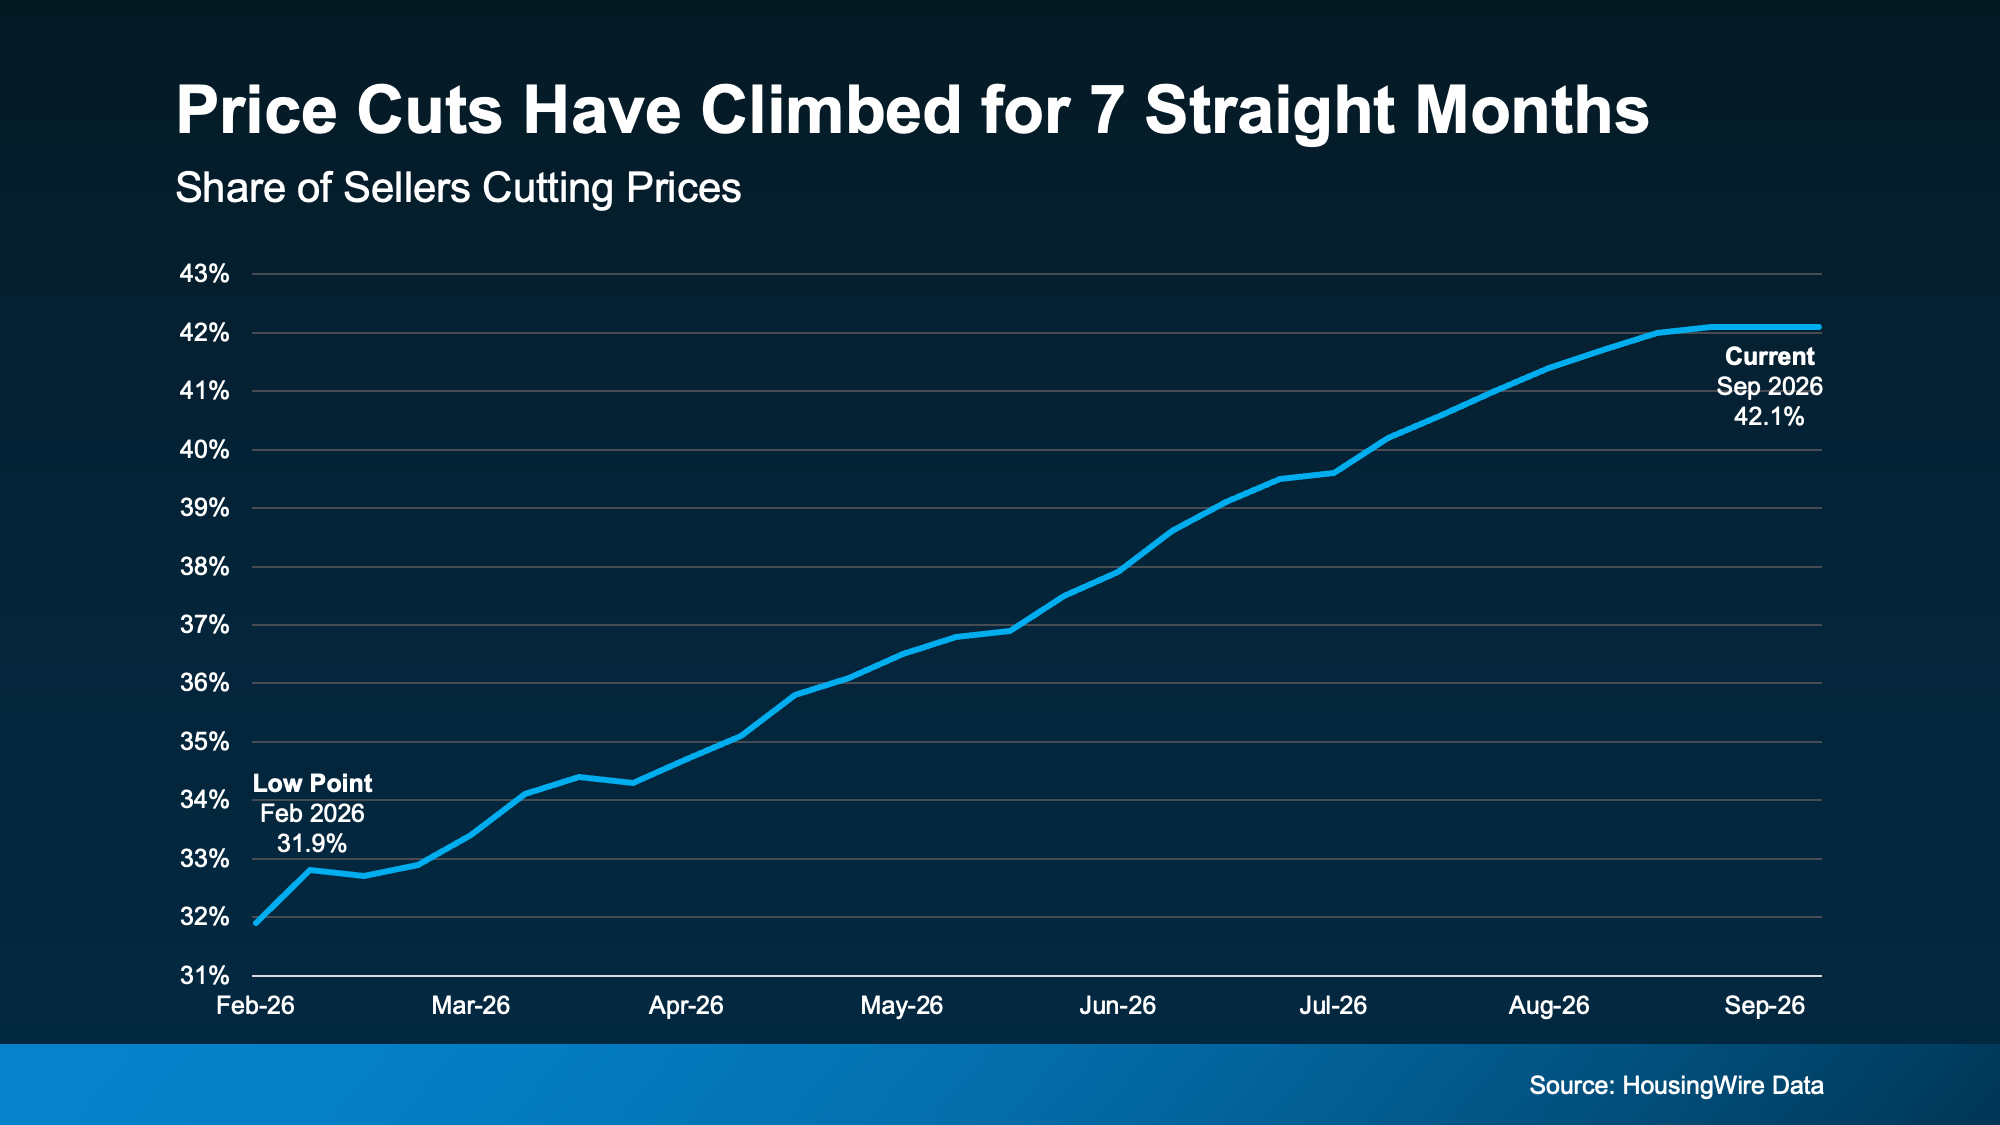
42% of Homes for Sale Are Now Carrying a Price Cut

According to HousingWire Data, the share of sellers cutting their asking price has climbed every month for 7 straight months (see chart below):

a graph showing the growth of a straight month 

Today, more than 4 in 10 active listings have had at least 1 price cut, and the typical seller is cutting about $17,560 off their original number. 

Here’s why that’s happening. With rates still elevated and more homes to choose from, buyers can afford to wait for the right number. So, sellers who don’t start there often end up adjusting anyway.

What does that mean for you?

  • If you're selling, this isn’t a red flag. But it is a sign that pricing it right from day 1 is your best bet. Just know that the market's been shifting fast enough this year that sometimes even a well-priced house can fall behind within a matter of weeks. If that happens to you, dropping your price to catch up to where pricing actually stands today tends to bring in more buyers and helps you sell closer to true market value.

  • If you're buying, it's easy to assume a price cut means something's wrong with the house. But with cuts happening on more than 4 in 10 homes right now, the reality is sellers are just catching up to where the market already is. And with affordability still tight, that's exactly the kind of opening you need to get a better deal.

Why Sellers Are Adjusting Faster than Before

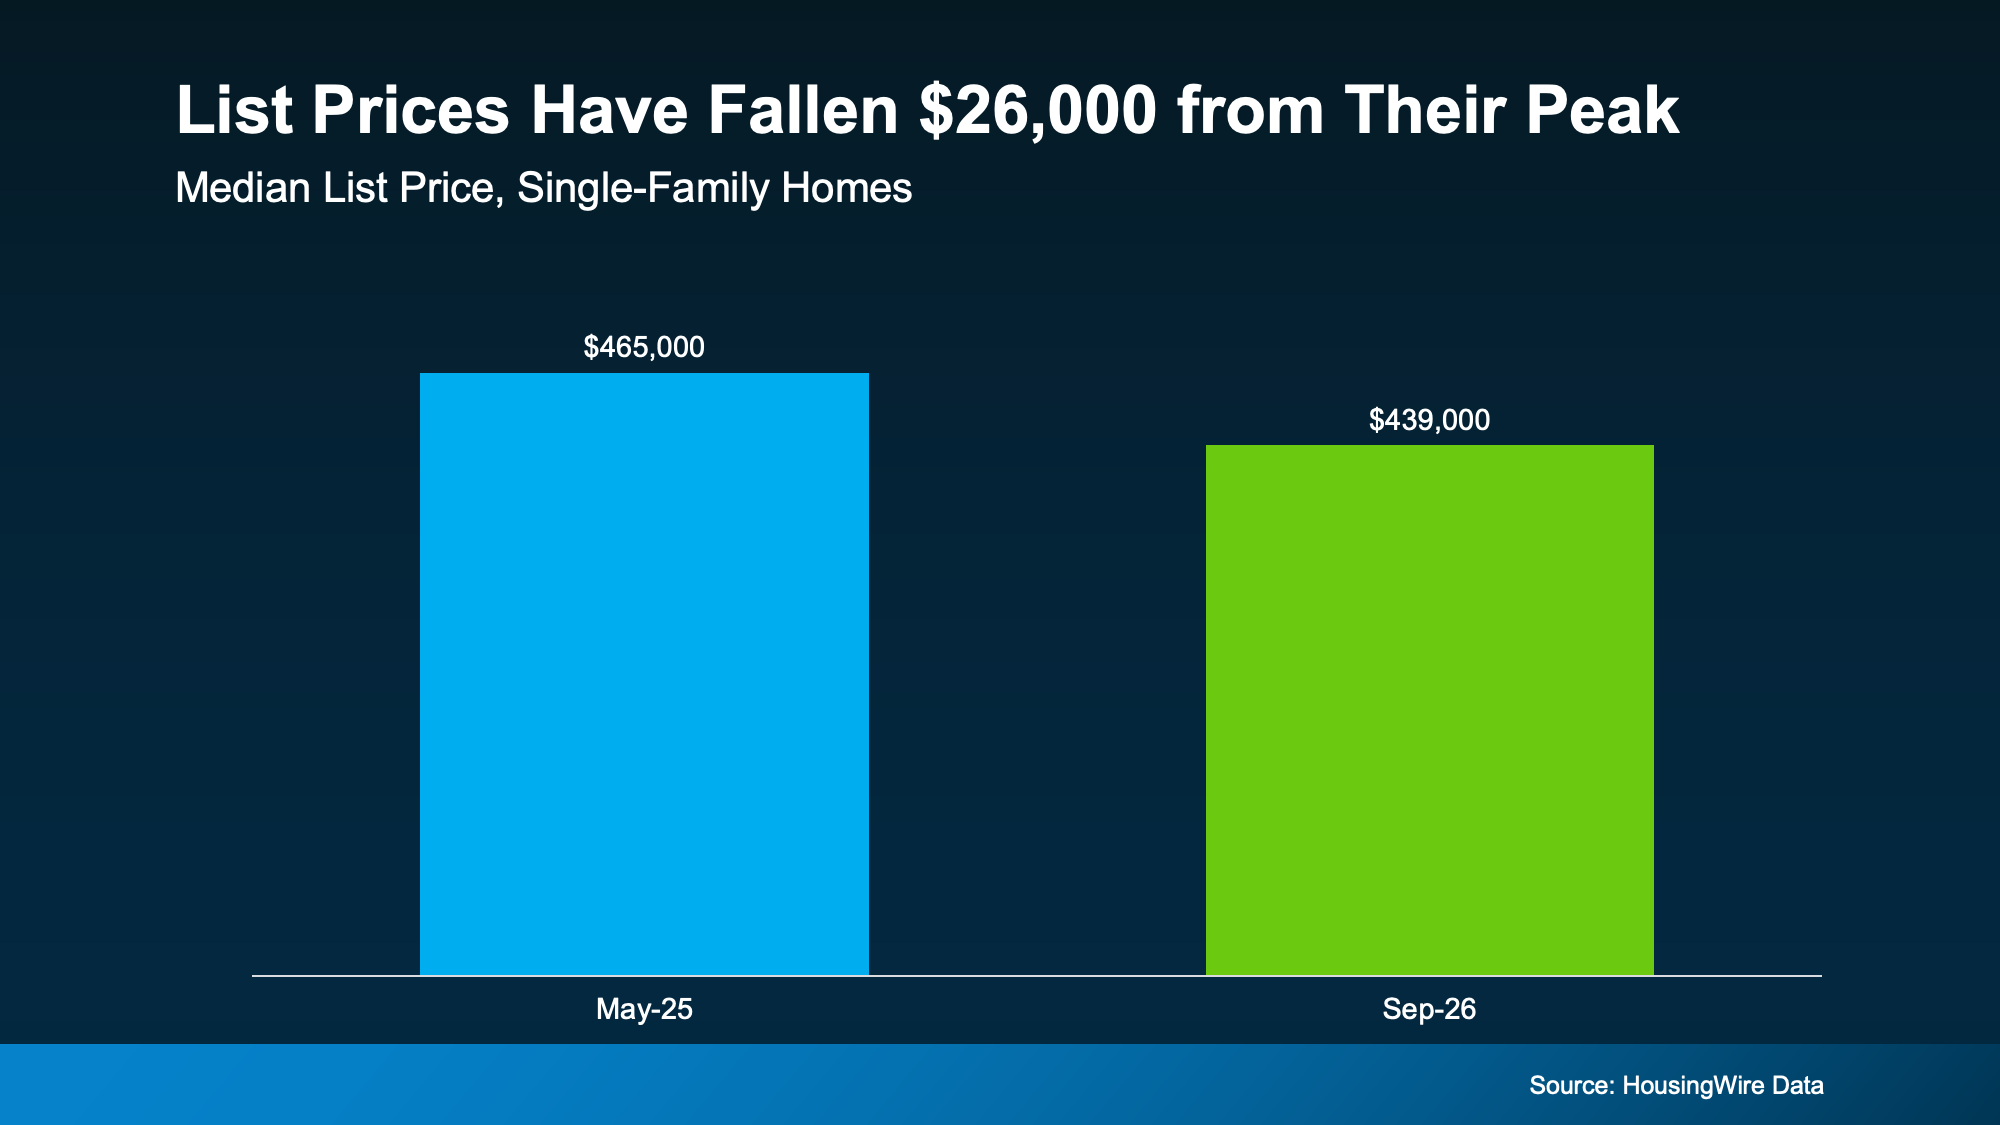
HousingWire Data also shows list prices are trending down nationally. That’s often a sign sellers are pricing more realistically from the start instead of listing high and getting stuck cutting later. List prices have fallen about $26,000 from last year's peak.

Some of that decline is seasonal, since list prices typically soften each winter before rebounding in the spring. So, expect asking prices to keep drifting a little lower before turning back around (see chart below):

a graph of a number of people 

Jake Krimmel, Senior Economist at Realtor.com, explains: 

“That is good news for buyers, who are seeing lower asking prices and more room to negotiate, but it is also good news for sellers: Pricing to today’s demand is helping homes move and keeping more transactions alive in a high-rate environment.”

Translation – with rates still elevated, buyers can only stretch so far. Sellers who meet them where they are instead of holding out for unrealistic prices are the ones actually getting to closing. And doing that up front is always better than chasing the market later.

Buyers, You’ve Got Room To Negotiate Again

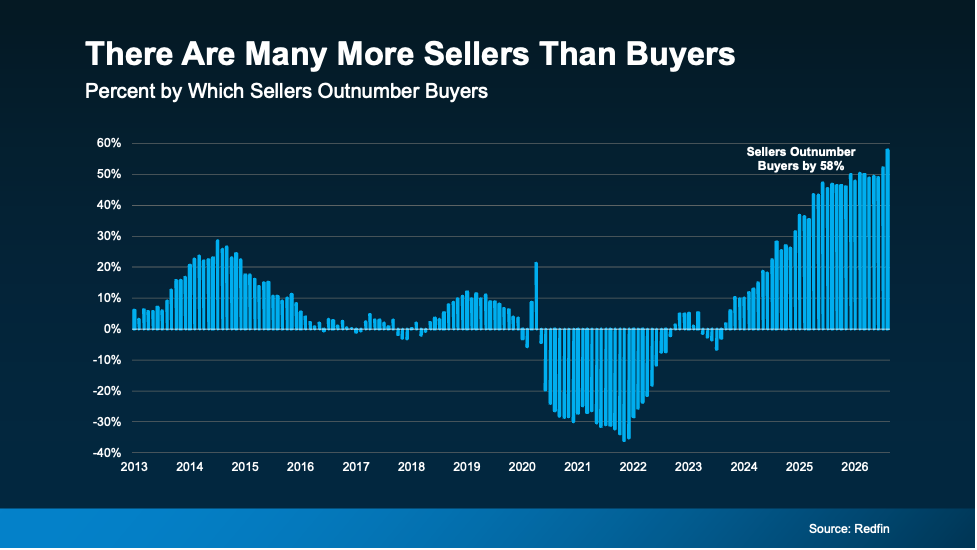
At the same time, Redfin data shows sellers now outnumber buyers by about 58%, the widest gap on record (see chart below):

a graph of sales 

That changes the power dynamics of the market – and impacts how homeowners should price their house. Nationally, about 7 in 10 markets now favor buyers or are trending that way.

  • For sellers, that means standing out matters as much as pricing. With more homes to choose from, buyers are comparing you directly against the competition. So, a little flexibility, like covering closing costs or being open on timing, can be what gets your house picked over another.

  • For buyers, it means more room to ask for a lower price, help with closing costs, repairs after inspection, or some combination of all 3. That’s especially true for homes that have already sat for weeks, where sellers are often the most willing to talk.

Bottom Line

Price cuts are a normal part of today’s housing market, and both buyers and sellers can use them to their advantage. Let's look at what's actually happening with prices in your neighborhood, so you know exactly where you stand before you list or make an offer.

The information contained, and the opinions expressed, in this article are not intended to be construed as investment advice. Keeping Current Matters, Inc. does not guarantee or warrant the accuracy or completeness of the information or opinions contained herein. Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision. Keeping Current Matters, Inc. will not be liable for any loss or damage caused by your reliance on the information or opinions contained herein.

Posted in Market Updates
Sept. 22, 2026

Fall Curb Appeal Tips for Sellers


If you’re selling this season, a little effort out front goes a long way. Because the moment a buyer pulls up to a showing, they're already forming an opinion. But there are a few simple things you can do to nail that first impression. Think tidying up your landscaping, bringing in some seasonal flowers, and sweeping the walkways. Or even just cleaning out the gutters and making sure the path to your door is well lit. You don’t need to do a big overhaul to get buyers’ attention. Let’s chat about what people in our area are looking for right now, and get your house prepped to sell this fall. #SellYourHouse #CurbAppeal #KeepingCurrentMatters


Posted in Market Updates
Sept. 17, 2026

Selling This Fall? You Want To Get These 4 Things Right.

Selling This Fall? You Want To Get These 4 Things Right.

BLOGSeptember 17, 2026

3 min read

Selling your house this fall is absolutely doable. But there’s something you need to know about this time of year. 

Buyer activity typically starts to slow while the number of homes for sale climb – and you need the right strategy to get attention in this type of market.

The good news? There’s a lot you can control.

From how you price and present your house to how you negotiate and respond to feedback. Here are four things you’ll want to get right this fall. 

#1: Price To Get Buyers’ Attention

In the fall, there are typically fewer buyers looking and more homes for them to choose from. So, you want to make the most of every buyer who comes across your house.

And your price is one of the first things that can make them stop and take a closer look – or keep scrolling. 

That’s why this isn’t the time to start high “just to see what happens.”

If buyers think your house is overpriced, they have plenty of other options to move on to. And that could leave you sitting and waiting.

So, if you want to sell before year-end, work with your agent to find the right price for your house and today’s market. That may mean listing at market value – or even slightly below it – to grab buyers’ attention.

Redfin explains how a seemingly small difference can change your buyer pool: 

“Buyers often search in round-number price brackets, so pricing at $499,000 instead of $505,000 can make your home appear in more searches and feel like a better deal.” 

#2: Make a Great First Impression

When buyers had very few homes to choose from, they were often more willing to overlook dated finishes or a house that needed some work. That’s harder to count on now.

With more choices, how your house looks online and in person can determine whether it makes a buyer’s shortlist at all.

That doesn’t mean you need a full renovation before you sell, but you should take care of essential repairs, do what you can to boost curb appeal, and make sure your house photographs well. Maybe that’s some light staging, maybe it’s swapping out faucets or lights, or maybe a fresh coat of paint. Small details can help a lot.

After all, you only get one chance to make that first impression. Make it count.

#3: Stay Open To Negotiating

Some sellers are still expecting the kind of leverage they had a few years ago. But in many markets, buyers have more negotiating power today and there’s a lot more give and take.

The latest data from Redfin shows 46.2% of sellers gave buyers some type of concession. So, consider throwing in a little help with closing costs or covering a repair. Almost half of sellers are.

The takeaway? Playing hard ball may not get you what you want. But being flexible might. The key is not getting so focused on “winning” every individual negotiation that you lose sight of the bigger goal: making your move happen.

Sometimes a small concession is what gets you to the closing table.

#4: Know When It’s Time To Adjust

Sometimes your house tells you when something isn’t working. Maybe you’re getting plenty of online views but very few showings. Or buyers are coming through, but you’re not getting offers. Or maybe buyer feedback has one recurring theme.

Pay attention to those signals. They can help you figure out what needs to change.

Let’s say your price is the most common point of feedback. Talk to your agent about a price drop. It doesn’t have to be a big change to make a big difference. The average price cut right now is 4% according to HousingWire Data. That’s normal.

Now, that doesn’t mean you should panic and slash your price after a week. It means you and your agent should pay attention to what buyers are telling you and adjust if you need to.

Sometimes the smartest move isn’t waiting for the right buyer. It’s making sure you’re giving that buyer a reason to act.

Bottom Line

Selling this fall is absolutely doable. And now you know four of the biggest things to get right.

If you want to sell before the end of the year, let’s make sure you have a winning strategy from day one.

The information contained, and the opinions expressed, in this article are not intended to be construed as investment advice. Keeping Current Matters, Inc. does not guarantee or warrant the accuracy or completeness of the information or opinions contained herein. Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision. Keeping Current Matters, Inc. will not be liable for any loss or damage caused by your reliance on the information or opinions contained herein.

Posted in Market Updates
Sept. 14, 2026

Selling This Fall? You Haven't Missed Your Window

Selling This Fall? You Haven't Missed Your Window

BLOGSeptember 14, 2026


Summer's winding down, and if you've been thinking about selling, you might be wondering if you missed your chance. Better to wait until next year or even next spring, right?

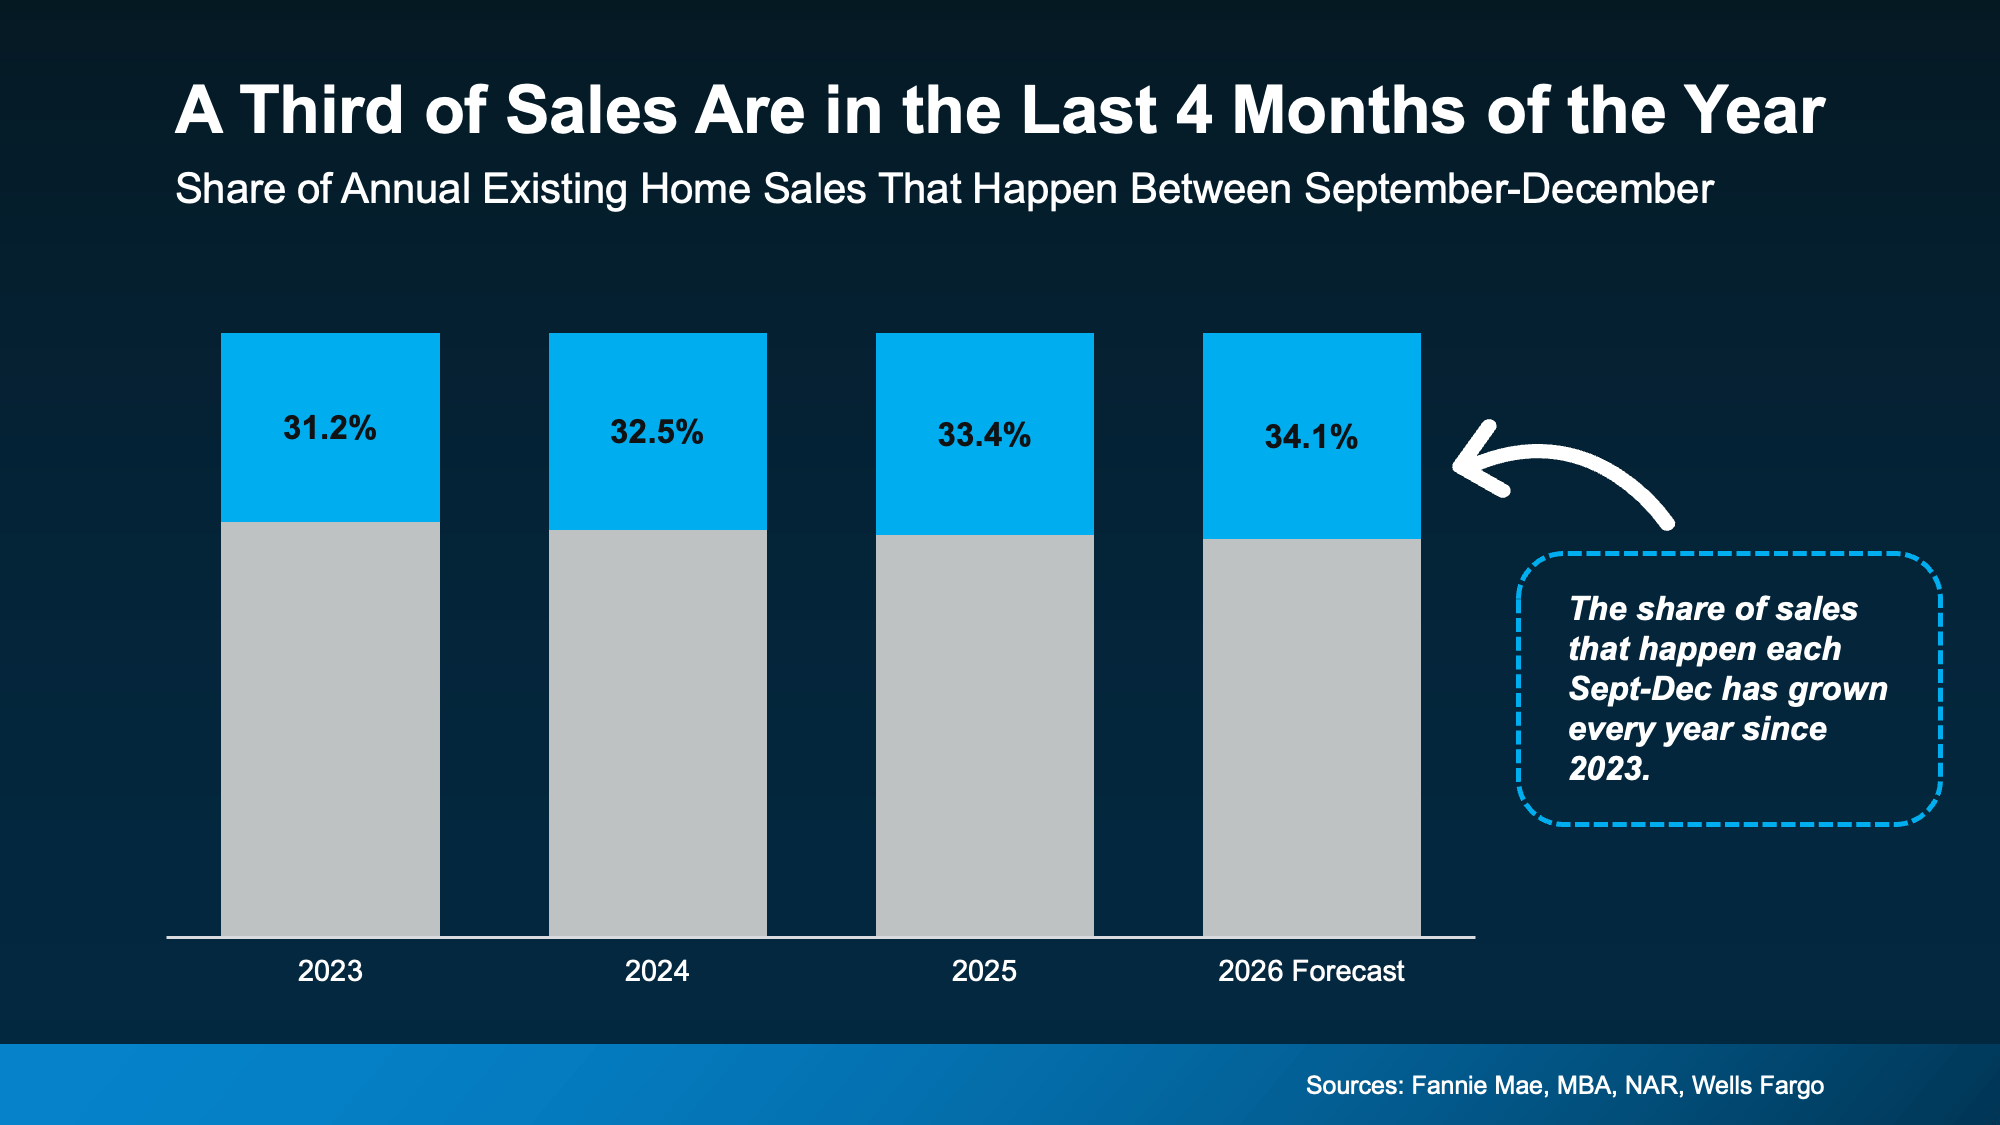
Not so fast. About one in three of all home sales happen in the last four months of the year.

Fall Is Busier than You Think

Data from the National Association of Realtors (NAR) shows around a third of existing home sales happen in the final four months of the year. And that share has grown every year since 2023 (see graph below):

a graph of sales

Here's What That Means for You

According to forecasts from Fannie Mae, the Mortgage Bankers Association (MBA), NAR, and Wells Fargo, there will be about 4.16 million existing home sales this year. Based on how many sales have happened so far, that means roughly 1.4 million sales are expected between now and December.

That's about 11,800 houses selling every single day this fall.

So, the market isn't frozen and you don’t need to put your plans on ice either. Yes, higher rates are keeping some buyers on the sidelines. But hold out for next spring, and you'll sit out months when other serious buyers are ready to move before the new year.

How do you get in front of those buyers who are still out there looking right now? Getting your house sold this season comes down to how well it's priced and presented,  and that's where a local agent shines.

A good agent knows what buyers in your area want right now, prices your house to match this fall's market, and positions it to stand out to the serious buyers shopping before year-end. From the first photo to the final offer, they handle the details that turn your house on the market into one of the 11,800 selling every day.

Bottom Line

Listing this fall doesn't mean your house will sit on the market until spring. Buyers are out there right now, ready to make a move before the new year – and your window is still open.

Let's connect and make yours one of the homes that sells this season.

The information contained, and the opinions expressed, in this article are not intended to be construed as investment advice. Keeping Current Matters, Inc. does not guarantee or warrant the accuracy or completeness of the information or opinions contained herein. Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision. Keeping Current Matters, Inc. will not be liable for any loss or damage caused by your reliance on the information or opinions contained herein.

Posted in Market Updates